


EN
Should Lowered Earnings Guidance Require Action From CRH (CRH) Investors?
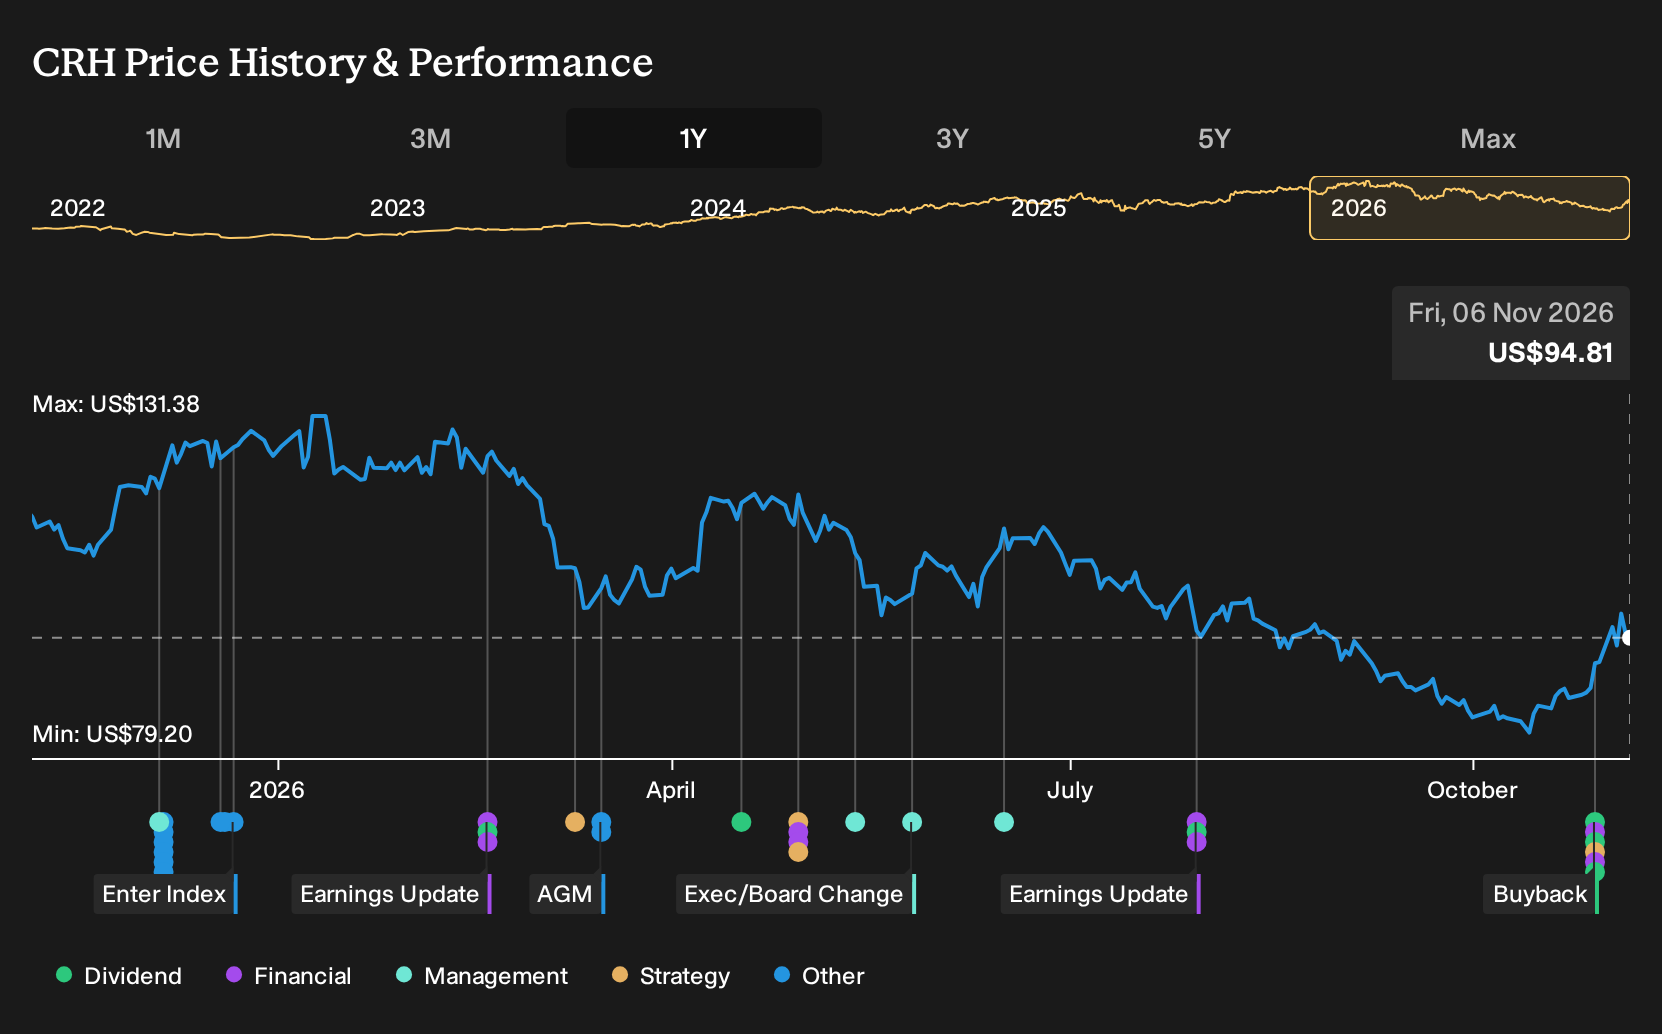
- CRH plc reported mixed third quarter 2026 results, with revenue of US$11,396 million and lower net income and earnings per share year on year, while also affirming a higher quarterly dividend of US$0.39 per share payable in December 2026.
- The group coupled reduced full year 2026 net income and EPS guidance with higher asset impairments and a new multi year US$6b buyback authorization, creating a tension between near term profit pressure and ongoing capital returns.
- We now look at how CRH's cut to 2026 earnings guidance may reshape the investment narrative investors have been relying on.
Compare CRH's mix of lower earnings guidance, higher dividend and fresh buyback with a hand picked group of construction related peers by scanning the list of solid balance sheet and fundamentals (25 results) for potential alternatives.
CRH Investment Narrative Recap
To stay comfortable as a CRH shareholder, you need to believe the core infrastructure story still holds while short term profitability gets reset. The lowered 2026 net income and EPS guidance points to a softer earnings path as impairment charges rise and residential exposure and integration risks remain in focus.
The key near term catalyst is execution on large U.S. infrastructure, utility and data center projects, because that is where volume and pricing power can still support the aggregates led model. The main risk right now is that any slowdown or funding shift in publicly backed projects hits demand just as earnings expectations have come down.
The new multi year US$6b share repurchase authorization is the announcement that matters most alongside the guidance cut. It signals that CRH still plans to commit sizeable capital to equity reduction over time, even after a period when leverage has been elevated and impairments have increased.
For you as an investor, that plan only really works if cash generation from infrastructure heavy operations and acquisitions like Arcosa holds up against the new, lower earnings range. Execution on project backlogs, cost discipline and integration will decide whether buybacks remain a support for per share metrics or become constrained by balance sheet risk.
CRH's current analyst script points to forecast 2029 revenue of US$44.7b and earnings of US$4.9b, based on 5.0% yearly revenue growth and an earnings increase of about US$1.1b from US$3.8b today.
Uncover why CRH's fair value indicates a 29% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on CRH’s capital deployment plan as the key catalyst, rather than just U.S. infrastructure projects. Before this guidance cut and dividend increase, the bullish camp was working off forecasts of roughly US$47.7b of 2029 revenue and US$5.5b of earnings, so this latest update may trigger meaningful reassessments.
Explore 5 other CRH fair value estimates, including one that suggests as much as 77% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CRH research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CRH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CRH's overall financial health at a glance.
Looking For More Ideas Beyond CRH?
If this CRH update has sharpened your view on the construction and infrastructure space, it can be useful to line that thinking up against a wider watchlist. The Simply Wall St Screener lets you quickly filter the market by quality, balance sheet strength and income potential so you can see which other companies fit the profile you care about most.
- If you want resilient businesses with room to compound steadily over time, scan through 31 resilient stocks with low risk scores that may better match your tolerance for volatility.
- If income is your priority right now, check out 7 dividend fortresses that focus on higher yielding payers with robust dividend profiles.
- If you are searching for less crowded opportunities with strong fundamentals, review 19 high quality undiscovered gems that might deserve a spot on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com