


EN
First Advantage (FA), Why Is Its Latest Update Drawing Attention?
First Advantage (FA) has just put fresh numbers on the table, with Q3 2026 results showing a move from a prior net loss to profitability and a higher full year revenue outlook.
On the market, First Advantage has been in the spotlight, with a 1-day share price return of 1.73% and a 7-day move of 8.99% around the Q3 release and raised guidance. This has fed into a 30-day share price return of 23.58% and a year-to-date gain of 65.12%, alongside a 1-year total shareholder return of 76.78%. Taken together, these figures point to strong momentum after a tougher patch earlier in the year, when the 90-day share price performance was roughly flat.
See how First Advantage's rebound compares with other companies showing strong momentum and fundamentals in our curated list of 38 high quality undervalued stocks.
The rebound in First Advantage has already been powerful, yet the stock still trades at a material discount to some intrinsic estimates and to analyst targets. How much of the potential re rating has actually been used up by this move?
Most Popular Narrative: 10.4% Undervalued
On the most followed narrative, First Advantage screens as undervalued, with a fair value of $26.25 against a last close of $23.53, leaving some implied upside if the thesis holds.
Ongoing investments in proprietary AI enabled technology, automation and integrated platforms are now anchored by more than 960 million criminal records, 135 million verification records and a SmartHub AI router. U.S. criminal fulfillment is already 70 to 75% automated and targeted toward roughly 90%, which supports the case for continued net margin and earnings expansion as volumes build on this fixed cost base.
See why 3 investors see First Advantage as 10% undervalued.
Result: Fair Value of $26.25 (UNDERVALUED)
Still, the First Advantage narrative can break if hiring volumes weaken again, or if margin and capital efficiency targets prove harder to reach than analysts expect.
Find out about the key risks to this First Advantage narrative.
Another View: What First Advantage’s P/E Ratio Signals
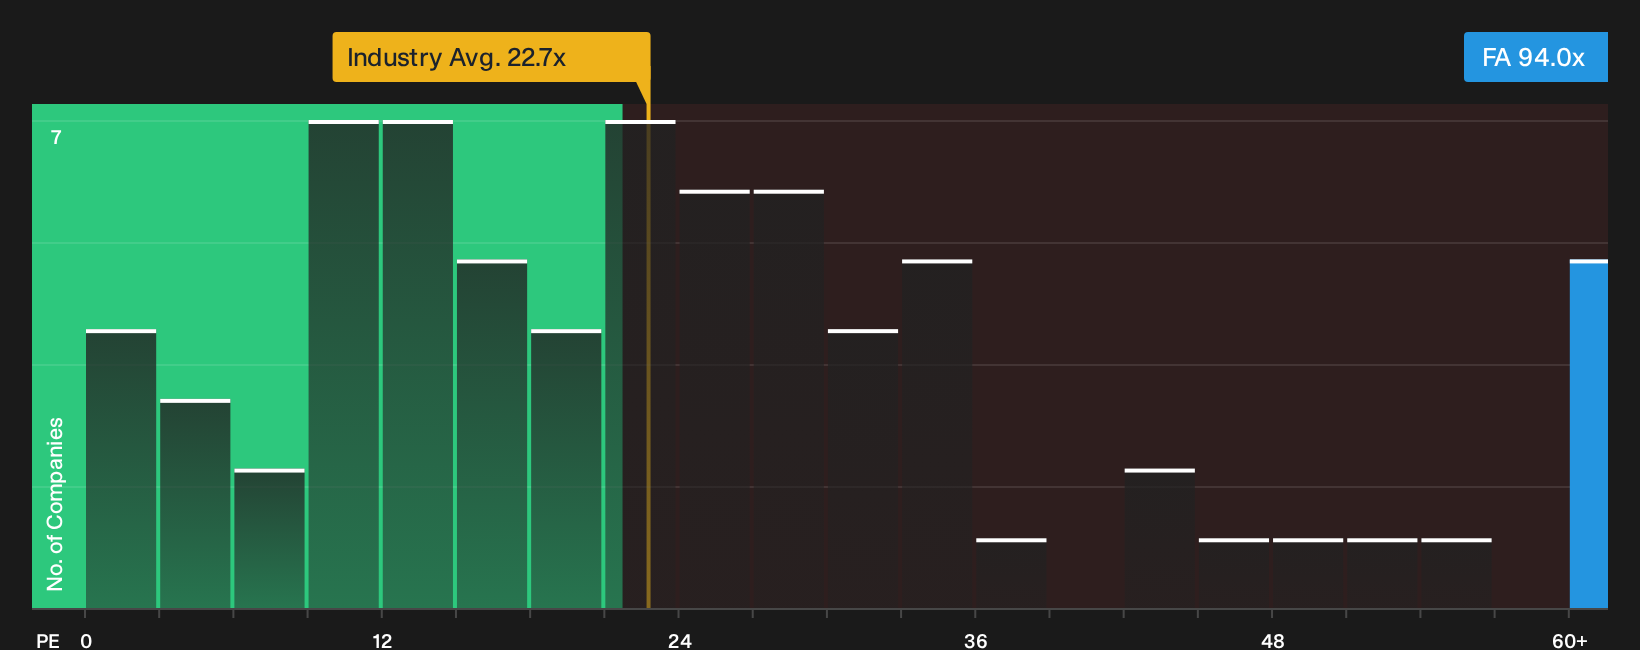
On a cash flow based lens, First Advantage screens as undervalued, yet the earnings multiple tells a sharper story. The stock trades on a P/E of 94x, versus about 22.7x for the US Professional Services group and a 19.7x peer average, while the fair ratio sits at 43.9x.
That gap suggests investors are already paying a premium that roughly doubles the fair ratio and more than quadruples the sector mean. This raises the risk that any wobble in execution or earnings expectations could hit the share price harder than the DCF view alone implies.
For a closer look at how this earnings multiple stacks up against sector norms and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on First Advantage is split, with strong momentum on one side and valuation questions on the other. Move quickly and stress test the thesis against your own risk tolerance and time horizon by weighing the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond First Advantage?
If First Advantage has your attention, do not stop here. Broaden your watchlist with other opportunities that match your goals and risk comfort.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Spot potentially mispriced opportunities by running through the 38 high quality undervalued stocks.
- Stack your income watchlist with payout focused candidates by checking out the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com