


EN
DraftKings (DKNG.US) was predicted to be “stolen” from the market, profits and quarterly losses exceeded expectations by 5 times, and Wall Street institutions such as Goldman Sachs cut target prices
The Zhitong Finance App learned that the core of the US sports betting operator DraftKings (DKNG.US)'s sharp drop in stock prices last Friday can be described as predicting that customer value brought about by market expansion has yet to be realized, yet profit pressure has entered the company's financial report ahead of schedule. The company's stock price rose by about 10.1% in October and still rose 1.77% on November 5 when technology stocks fell sharply; however, after the financial report and conference call, the closing price of US stocks fell 21.3% to 18.51 US dollars as of November 6. The NASDAQ 100 and Philadelphia Semiconductor Index rebounded 1.35% and 4.21% respectively on the same day, indicating that the selling pressure was mainly due to the company's own reset of profit expectations.
According to financial data, DraftKings' revenue increased 16% in the third quarter, but predicted market size expansion such as Polymarket and increased promotional investment in the online casino business caused revenue, profit, and subsequent guidance to fall short of expectations. Goldman Sachs's November 8 research report is still optimistic about the operating efficiency of the core business and predicts the long-term expansion space of the market. However, it lowered the 12-month target price from 34 US dollars to 26 US dollars, a decrease of 23.5%; compared with the closing price of 18.51 US dollars, the potential increase space is about 40.5%. Based on static estimates of existing share capital, the corresponding market value is about 12.96 billion US dollars. This latest target price cut also reflects Goldman Sachs's trade-off — acknowledging DraftKings' long-term growth opportunities while reducing the valuation of payments to meet the uncertainty of profits.
Customers are still growing, but profits are being consumed early: predicting the market rewrites the pace of profit release
The first contradiction Goldman Sachs is concerned about is that there is a clear disconnect between user growth and current profit. Third-quarter revenue of US$1,329 million was lower than the market forecast of US$1,387 million in the research report; Adjusted EBITDA (Adjusted EBITDA) loss was about US$317 million, and the market originally anticipated a loss of about US$60 million.
However, the net revenue of the core sports betting business increased by 36% and betting volume increased by 12%, which did not support the judgment that “traditional business has been completely eroded by predictive markets such as Polymarket”. The online casino business (iGaming) saw a 76% increase in new customers, but net revenue only increased by about 2%, indicating that customer acquisition promotions are depressing current revenue conversion.
At the performance conference call, management further explained that about 60% of the gap in the annual profit forecast reduction for the core business came from sports results beneficial to customers, and the rest was mainly due to iGaming customer acquisition investment.
The second contradiction is that profits generated by the core business are funding the expansion of new businesses. The company lowered its 2026 revenue guidance to US$6.35 billion to US$6.55 billion, and adjusted EBITDA to profit of US$175 million to US$275 million. Disaggregated according to the median value, the core business profit is about 900 million US dollars, after deducting the estimated net EBITDA drag of about 675 million US dollars, leaving about 225 million US dollars; the “investment” here is a net drag on profit caliber, not data center capital expenses.
In 2027, the company expects revenue of 7.35 billion to 7.75 billion US dollars, and the adjusted EBITDA is 800 million to 1 billion US dollars: the median value is equivalent to the core business of 1.2 billion US dollars, after deducting the forecast market loss of 300 million US dollars. From this perspective, profit recovery in 2027 depends not only on increasing profits from core business, but also on forecasting narrowing of market business losses. The latter has not yet entered the full profit stage.
Goldman Sachs retains the “purchase”, but at the same time revises profits and multiples: the revaluation depends on the customer's return on cost
Goldman Sachs's key to maintaining a positive judgment is to predict that the market has already shown financial benefits for customers worth tracking: more than 1.6 million customers participated in the year, and the retention performance was close to sports betting. Customers acquired in 2026 are expected to recover customer acquisition costs in about 20 months, which is better than the two-year target.
However, the recycling cycle is calculated by management, and it still takes time to confirm revenue and realize profits. The phone call revealed that marketing spending is still likely to increase slightly in 2027. The narrowing of losses mainly relies on existing customers to generate more gross profit, rather than simply cutting promotion budgets.
Goldman Sachs retained its long-term growth judgment based on this, while lowering the adjusted EBITDA forecast for the fourth quarter by 60% to US$226 million, and the 2027 and 2028 forecasts by 21%, 18% to 906 million and US$1,306 million, respectively; of these, the 2027 revenue forecast was only reduced by about 1%, indicating that this revaluation mainly occurred at the level of how much the growth would cost and how long it would take to turn into profit. Its free cash flow forecast also reflects the same pace: outflows of approximately US$181 million in 2026, and inflows of approximately $534 million and US$902 million in 2028, respectively.
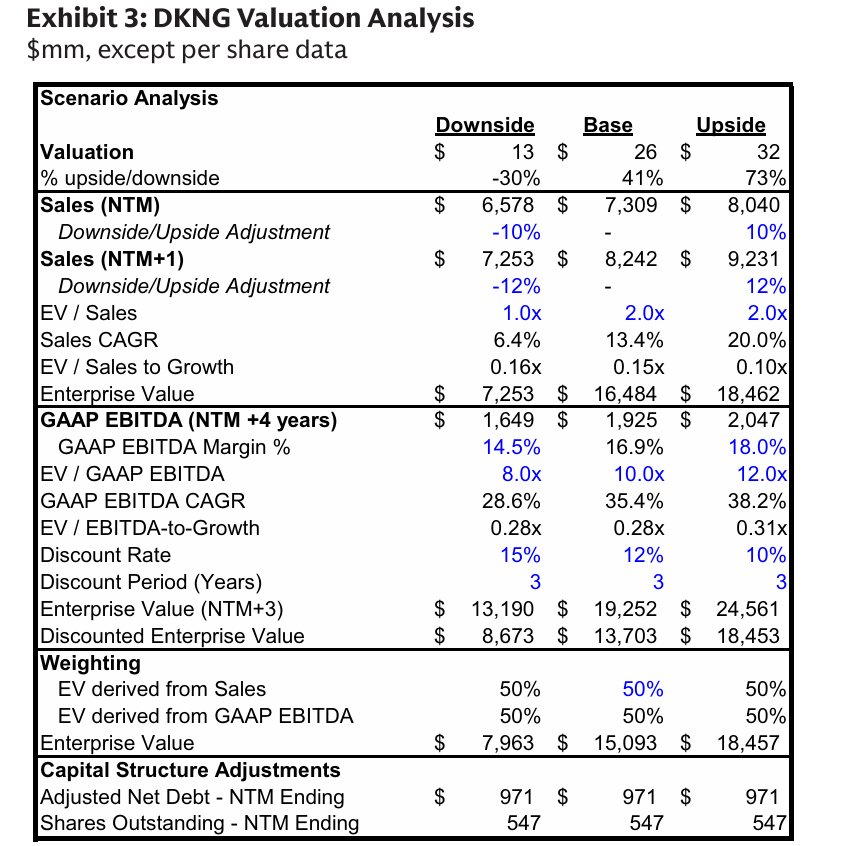
Target price adjustments further reflect this prudence. Goldman Sachs uses a method of revenue valuation and forward profit discounting of 50% each: the revenue side maintains 2 times the corporate value/revenue, while the profit side reduces the forward enterprise value/GAAP EBITDA ratio from 13 times to 10 times, and reverses it for 3 years at a 12% discount rate. In other words, the target price of $26 also includes a reduction in profit forecasts and compression of valuation multiples; the 12% discount rate has not been increased.
Furthermore, the downside, benchmark, and upward scenarios presented by Goldman Sachs Research are $13, 26, and 32, respectively, which is about − 29.8%, +40.5%, and +72.9% compared to $18.51. What determines which side the valuation approaches is customer retention after promotions decline, core business cost efficiency, and the impact of sports event contract regulation, NSW legalization, gaming taxes, and marketing restrictions on customer returns.
How big is the predicted market shock? Compete for customer entry and impact profit release first
DraftKings' main business includes online sports betting (Online Sports Betting), online casinos, Daily Fantasy Sports (Daily Fantasy Sports), as well as lottery-related services and an expanding prediction market.
The economic model of sports betting is determined by bet size, odds, results, and product mix: bet amounts deduct payouts to form gross gaming revenue, then deduct customer promotions to form net revenue, and then bear gaming taxes, payments, data, and operating costs. Therefore, an increase in betting amounts does not automatically equal a simultaneous increase in profits; product portfolios such as collusion, pricing power, and promotion intensity will change how much profit each dollar bet leaves in the end. The “sports consumer transaction amount” disclosed by the company also includes predictive market transactions and cannot be completely equivalent to traditional Sportsbook betting amounts.
Predictive markets such as Polymarket organize demand through tradable event contracts. The platform obtains revenue from brokerage, exchange, and related market making businesses. Its competitiveness depends on user size, contract abundance, transaction liquidity, and customer acquisition efficiency. The impact on DraftKings includes not only the continued diversion of potential customers, but also increased investment to maintain customer entry.
Companies can use the brand, customer base, and cross-product sales to expand new business, but these advantages need to be proven through customer retention and return on capital. At this stage, core sports betting is still growing, and it is not yet possible to predict that the market has seriously disrupted its main business; what has clearly happened is that the profits that the company has gradually released are being re-invested in a new round of customer competition. What Goldman Sachs is betting on is that this group of customers will continue to contribute revenue in the future, so that current customer acquisition costs will gradually be diluted, rather than the fact that the larger the transaction volume, the more profitable it will be.
Prediction markets (prediction markets) such as Kalshi and Polymarket can be described as popular all over the world since the US presidential election at the end of 2024. At that time, almost everyone was keen to use real money to bet on who Trump or Harris would win the US presidential election on the paid prediction market platform Polymarket. This also meant that the “everything can be gamble” trend began to sweep the financial market. Bets related to the Iran war have also pushed Polymarket geopolitical contracts to record highs, highlighting that the prediction market is showing a “everything can be gamble” trend, but at the same time quickly hit the red line of regulation and ethics.
Wall Street is still willing to be bullish, but the transaction price it is willing to pay has dropped significantly
After the financial report was announced, Wall Street institutions generally retained positive ratings for DraftKings, but they lowered their target prices one after another, reflecting that long-term growth opportunities are still being recognized, yet the uncertainty of recent profit delivery is depressing valuations. The following potential increases are all based on the closing price of $18.51 on November 6, while the market value corresponding to the target price is estimated at approximately 498.3 million shares of existing Class A common stock unchanged.
Bank of America maintained a “buy” rating and lowered the target price from $27 to $23, corresponding to a potential increase of about 24.3% and a market value of about US$11.46 billion. The bank believes that the company's 2027 profit forecast has been reset more than expected, sports event contracts still face regulatory risks, and large-scale promotion investment has heightened investors' concerns about profitability, so stricter expenditure control is needed. BMO Capital, on the other hand, maintained an “outperforming market” rating, drastically lowering the target price from $50 to $26, focusing on revenue falling short of expectations in various businesses and the erosion of profits from expansion investment; Truist also focused on increasing quarterly losses and revising full-year guidelines, but maintained a “buy” rating and a target price of $26. The target prices of the latter two institutions both correspond to a potential increase of about 40.5% and a market value of about US$12.96 billion.
Jefferies and Macquarie also chose to keep positive ratings and lower target prices. Jefferies maintained a “buy” and lowered the target price from $44 to $28; Macquarie maintained “outperforming the market” and lowered the target price from $34 to $28, all corresponding to a potential increase of about 51.3% and a market value of about US$13.95 billion. Jefferies believes that the adjustment of guidelines exceeding expectations is an important reason why stock prices are under pressure. It is predicted that the economic model of the market may still change in the next two years; however, demand for digital gaming in the US has not been fully developed, and DraftKings' ability to attract customers and achieve profitable customer acquisition through product innovation still provides support for long-term growth.
Other agencies' adjustments also reflect similar trade-offs. Canaccord Genuity maintained a “buy”, reducing the target price from $40 to $30, corresponding to a potential increase of about 62.1% and a market capitalization of about $14.95 billion; Barclays maintained an “increase”, reducing the target price from $34 to $27, corresponding to a potential increase of about 45.9% and a market value of about $13.45 billion; Freedom Capital maintained a “buy” and lowered the target price from $28.50 to $25, corresponding to a potential increase of approximately $12.46 billion. These adjustments show that the agency still believes that there is room for repair in stock prices, but it has adopted more careful pricing to predict how much profit market expansion can contribute and when it will be realized.