


EN
3 Indian Growth Stocks With At Least 28% Revenue Growth
Higher U.S. Treasury yields have pushed investors worldwide to rethink risk, and Indian high growth companies are squarely in that spotlight. When safer assets pay more, the bar rises for any business that wants your capital. That is where financially sound, fast expanding Indian firms can become interesting for long term portfolios. This article highlights three stocks from this growth focused screener that may be worth a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to financially sound businesses with healthy high growth potential. However, if you want the strongest names, these 53 best high growth potential stocks are at the top of the list.
Timex Group India (BSE:500414)
Overview: Timex Group India designs, manufactures, and sells Timex and licensed branded wristwatches across India and abroad, targeting growth through wider retail and e commerce reach.
Market Cap: ₹70.9b
Timex Group India fits the Healthy high growth potential theme through its branded watch business, with earnings forecast to rise about 29.8% a year and recent Q2 FY26 revenue of ₹3,591.7m alongside net income of ₹471.1m. Growth leans heavily on product launches and expanding distribution. This keeps future earnings power closely linked to how that single pillar performs under different conditions.
That single growth engine makes the story binary, so it is worth reading the 2 key rewards and 2 important warning signs (1 is major!) before deciding how much concentration risk you want.

Jyoti CNC Automation (NSEI:JYOTICNC)
Overview: Jyoti CNC Automation manufactures metal cutting CNC machines that serve capital intensive sectors, directly tying its core equipment line to the Healthy high growth potential theme.
Market Cap: ₹236.6b
Jyoti CNC Automation appeals to this screener because its CNC machine portfolio is closely linked to rising demand from capital heavy industries that rely on automation to lift productivity. The current phase of capacity build out is where that theme really starts to bite.
"The management’s move to lift annual capacity from about 6,000 to 16,000 machines through the new 10,000 machine facility, which is largely ready with commissioning targeted by end September and foundry by October, positions Jyoti CNC Automation to convert an order book of about ₹4,848 crore and high utilisation into higher revenue and better operating leverage on fixed costs."
What happens to earnings power depends heavily on how one unseen pressure shapes the balance between higher volume and future margin resilience.
That tension around future margins is exactly what the full narrative for Jyoti CNC Automation unpacks, showing where accelerating capacity could amplify earnings power or quietly compress profitability.
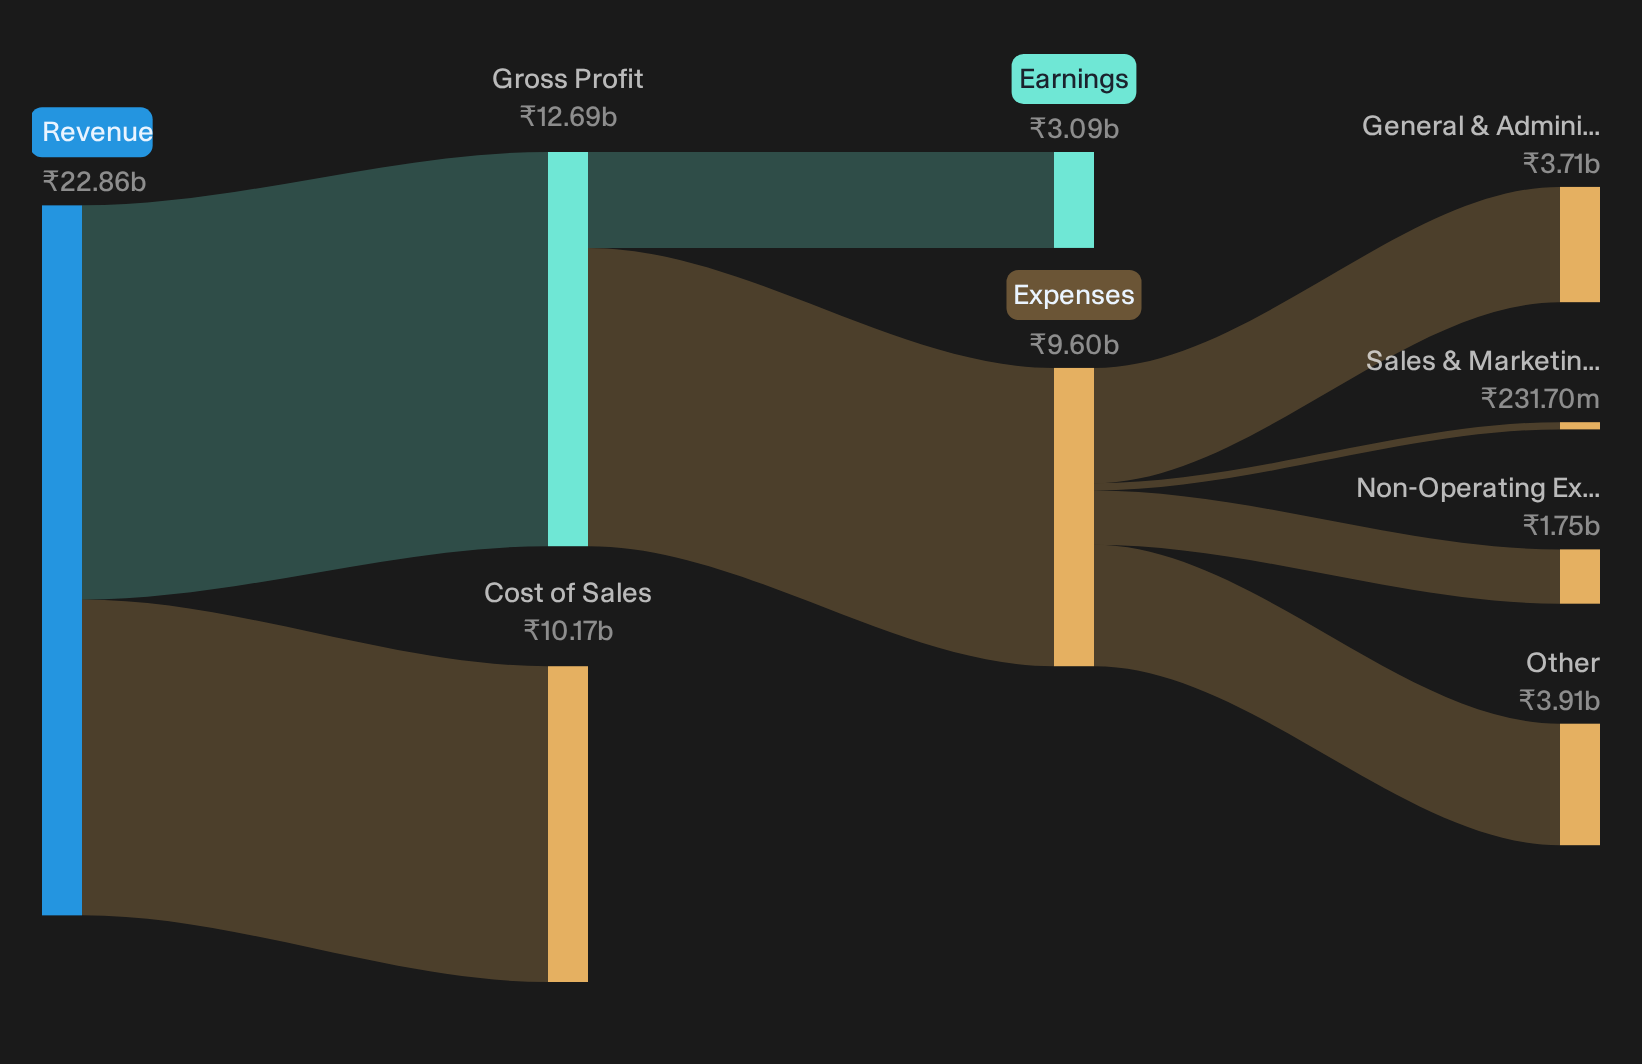
Schneider Electric Infrastructure (NSEI:SCHNEIDER)
Overview: Schneider Electric Infrastructure designs and services medium voltage grid equipment and digital energy management systems for utilities and infrastructure projects.
Market Cap: ₹266.5b
For the Healthy high growth potential theme, Schneider Electric Infrastructure matters because its grid equipment and digital platforms sit directly in the path of electrification and grid upgrade spending.
"Order momentum in emerging segments, with H1 FY27 orders of INR 2,180 crore up 25% and Q2 FY27 orders of INR 1,265 crore up more than 50%, creates headroom for Schneider Electric Infrastructure to secure larger ticket projects in high specification power distribution for data centers and semiconductors, which can support revenue growth and a richer project mix."
What ultimately happens to Schneider Electric Infrastructure’s earnings depends on how pricing pressure shapes the link between this richer mix and future margins.
That margin puzzle is exactly what the full narrative for Schneider Electric Infrastructure unpacks, showing where accelerating grid demand could mask risks or set Schneider Electric Infrastructure up for a stronger earnings profile.

Seeking Alternatives Before The Crowd Moves
Fresh opportunities rarely stay quiet for long. Once momentum builds, prices can move fast and ideal entry ranges can move higher. Scan these curated ideas while it matters and consider them early.
- Target income streams that can help steady your portfolio and review a curated mix of higher yielding companies in the 228 dividend fortresses before others pursue the same payouts.
- Identify early movers in digital assets and examine a focused set of stocks tied to real-world blockchain adoption with the 19 cryptocurrency and blockchain stocks while they remain less widely followed.
- Review opportunities linked to power infrastructure and assess companies geared to long term electrification trends using the 41 power grid technology and infrastructure stocks before they attract more short-term trading activity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com