


EN
Is Earnings And Raleigh Groundbreaking Altering The Investment Case For Life Time (LTH)?
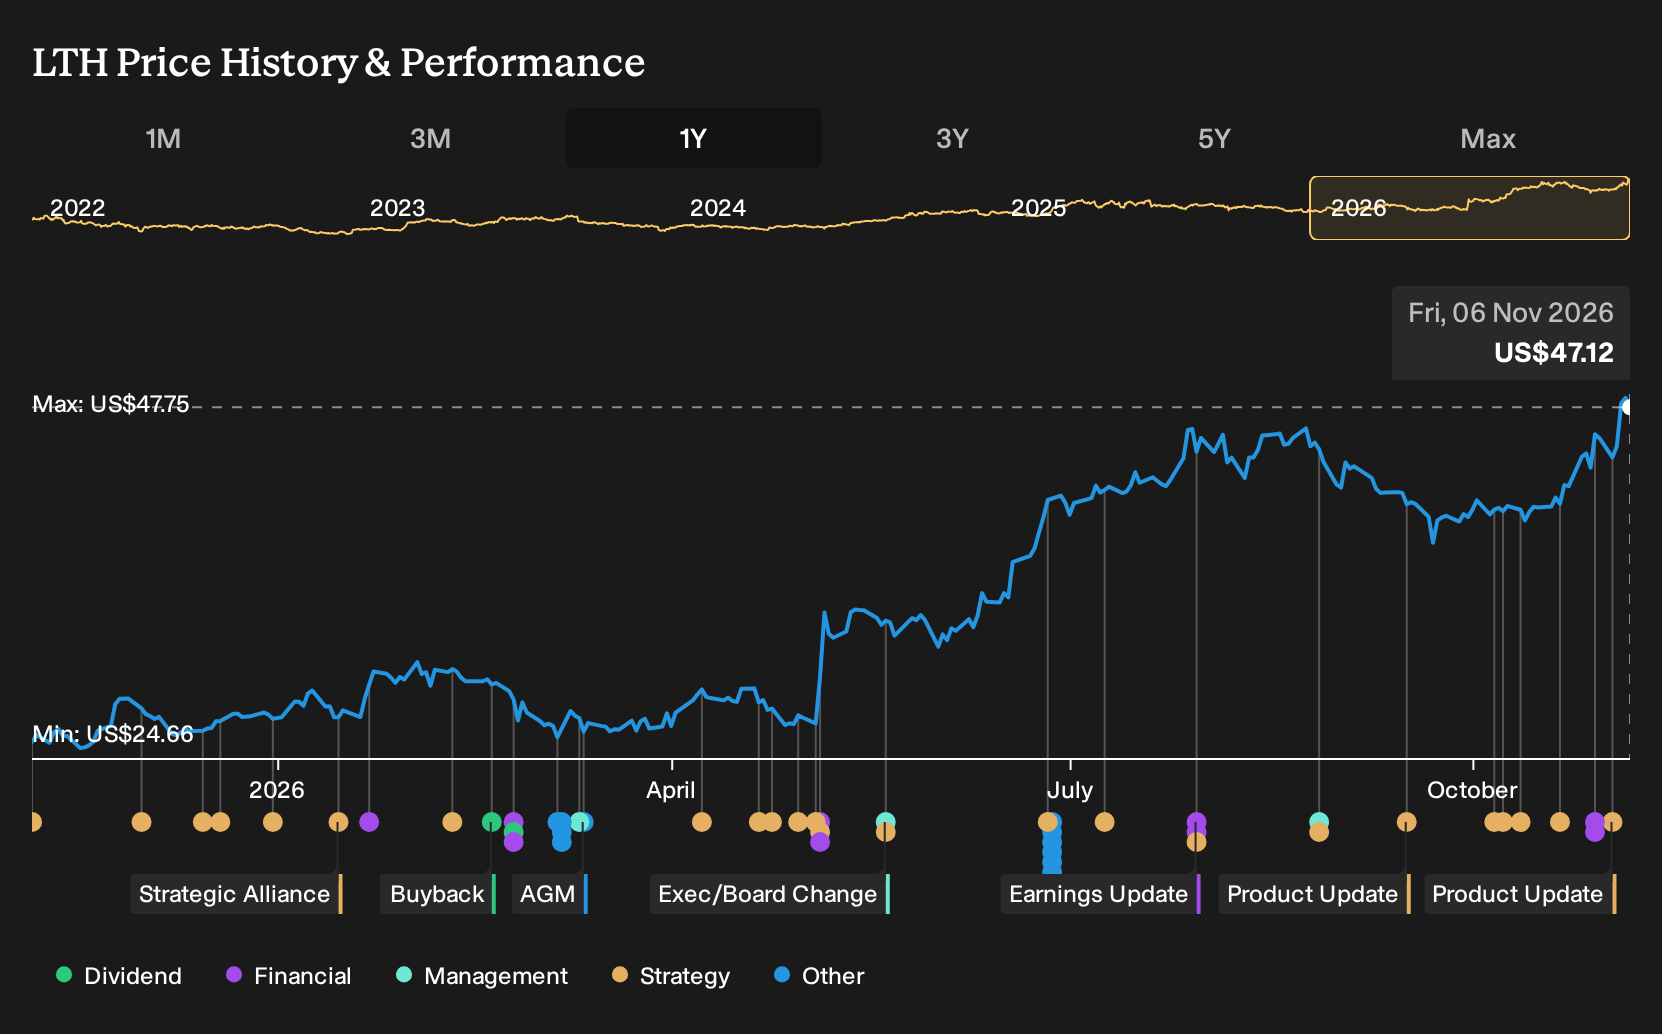
- Life Time Group Holdings reported third quarter 2026 revenue of US$893.52 million and net income of US$106.49 million, updated full year guidance, and advanced its Life Time Living at The Exchange Raleigh project with an official groundbreaking for a large mixed use wellness and residential complex.
- The vertically integrated Life Time Living tower in Raleigh, with luxury apartments built directly alongside an 80,000 square foot athletic club and a 40,000 square foot rooftop beach club, illustrates how Life Time Group Holdings is tying premium wellness experiences to real estate driven membership and ancillary spending opportunities.
- This article examines how Life Time Group Holdings' investment narrative is influenced by the Raleigh Life Time Living groundbreaking in combination with the updated revenue guidance.
Scan for other premium wellness and experiential lifestyle stocks that echo the Life Time Group Holdings story by jumping into our hand picked 19 high quality undiscovered gems list.
Life Time Group Holdings Investment Narrative Recap
To own Life Time Group Holdings, you need to buy into a premium wellness model that ties high-end clubs, in-center services and now residential projects into one ecosystem. The key short term swing factor is still execution on the current club pipeline and ancillary spend, not the Raleigh groundbreaking itself, which feels more like a long dated proof point.
The biggest near term risk remains heavy capital expenditure and reliance on sale leasebacks, especially with guidance implying tight guardrails around revenue and net income. Slightly higher revenue guidance and a narrowed net income range do not materially change that risk reward balance, but they keep attention squarely on cash generation and project returns.
The most relevant update around this Raleigh project is the 2026 guidance tweak, where Life Time Group Holdings lifted expected revenue to US$3.38b to US$3.39b and tightened net income to US$358m to US$360m. That kind of fine tuning sets the bar the firm will be judged against while it layers on long build projects like Life Time Living.
For you as an investor, that means the catalyst to watch stays simple. Will new clubs and higher value services support those revenue and earnings ranges while heavy development like The Exchange Raleigh and other Life Time Living sites progress on time and on budget? Any slip on returns or timing would land quickly in cash flow and leverage.
Life Time Group Holdings' current analyst storyline points to revenues of US$4.6b and earnings of US$513.3 million by 2029, built on an assumed 11.4% yearly revenue growth rate and an earnings increase of about US$94.4 million from US$418.9 million today.
Uncover why Life Time Group Holdings' fair value indicates a 22% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view focuses less on Life Time Living at The Exchange Raleigh as a future growth engine and more on the risk that heavy multi year construction spend squeezes margins. The most cautious analysts were modelling roughly US$4.4b of revenue and US$496.6 million of earnings by 2029 before this news, which is below consensus. That group tells a more pessimistic story around Life Time Group Holdings, assumes slightly slower 10.4% yearly top line growth and a profit margin closer to 11.2%. You do not need to pick a side today. Use this Raleigh milestone as a moment to compare these lower expectations with the baseline view and decide which narrative you find more convincing.
Explore 3 other Life Time Group Holdings fair value estimates, including one that suggests as much as 34% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Life Time Group Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Life Time Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Life Time Group Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Life Time Group Holdings?
Once you have a handle on Life Time Group Holdings, it can help to compare that story with other opportunities that match your own risk tolerance, income needs, and balance sheet preferences using the Simply Wall St Screener.
- If you want potential income plus a focus on resilience, start with a shortlist of high yielding payers by reviewing 7 dividend fortresses that already clear strict criteria on payout levels.
- For investors who care most about financial strength and durability, filter for companies with cleaner balance sheets through a curated list of solid balance sheet and fundamentals (25 results) that keeps debt and funding risk in view.
- If you prefer to keep downside risk front of mind, use a pre built 31 resilient stocks with low risk scores that highlights businesses scoring well on stability and financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com