


EN
Learn Why The Bull Case For Amphenol (APH) Could Change Following Raised Sales Guidance
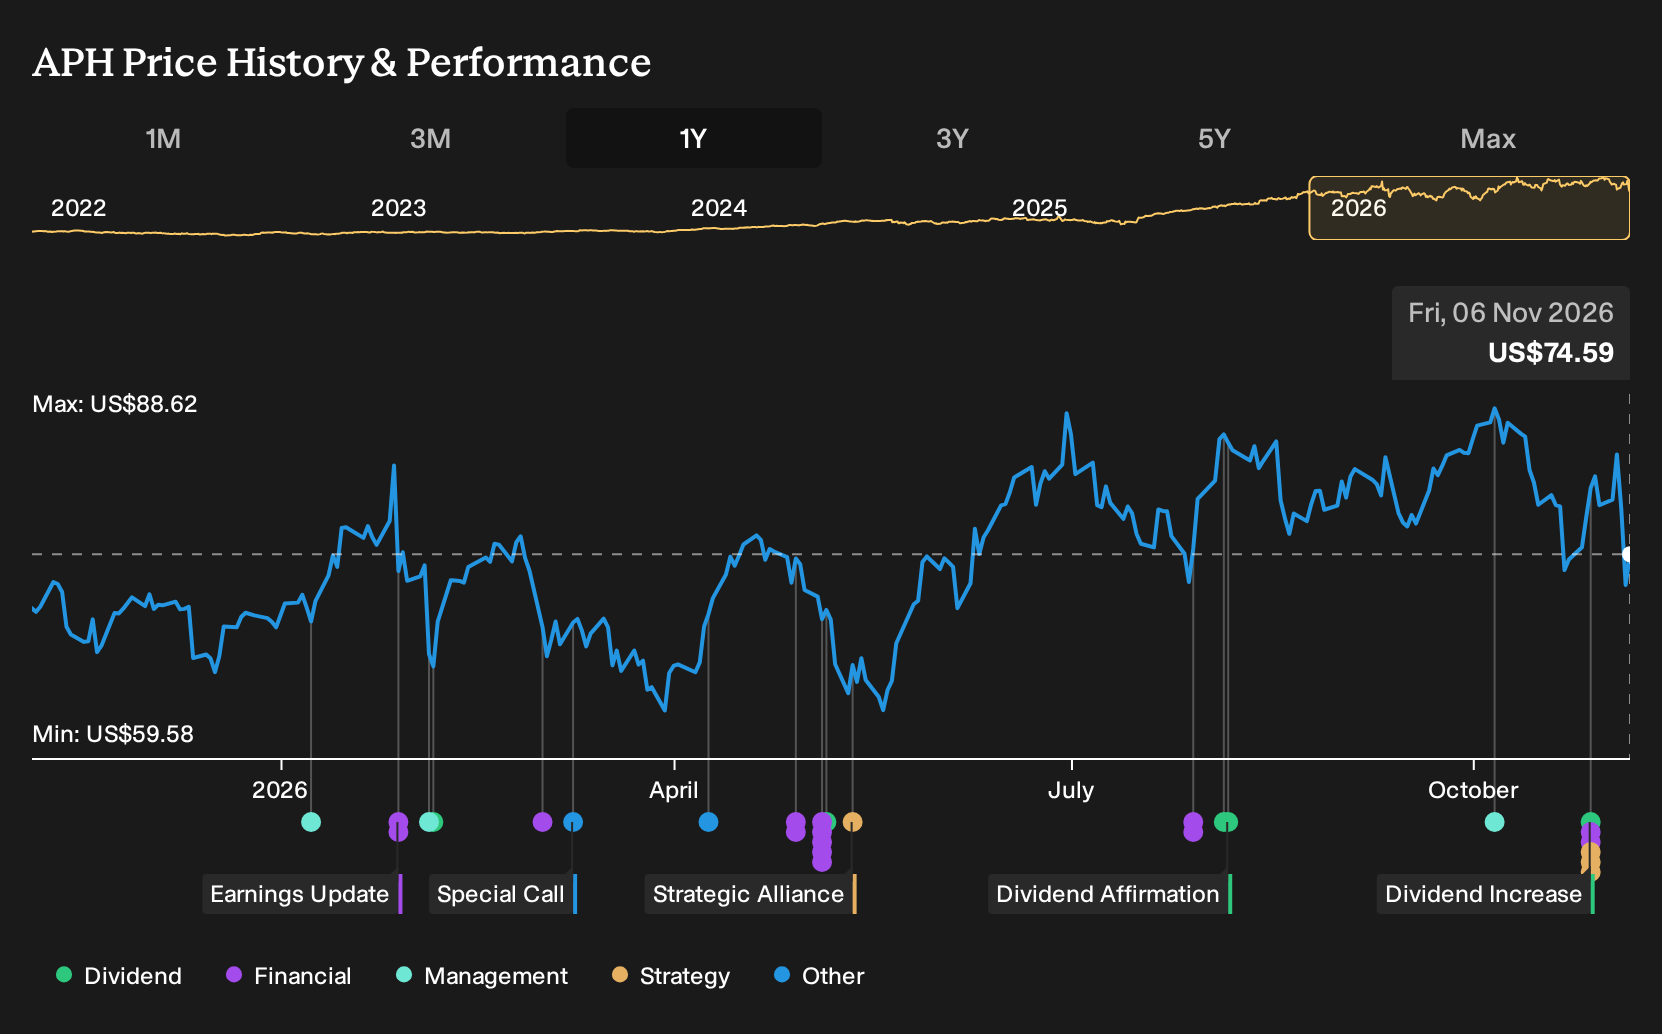
- Amphenol reported third quarter 2026 sales of US$10.2b and net income of US$2.0b, issued fourth quarter and full year guidance implying about 60% higher sales than the prior year, and the board approved a 20% increase in the quarterly dividend to US$0.15 per share.
- The combination of strong reported earnings, guidance for materially higher full year 2026 revenue and earnings per share, and a higher cash payout suggests Amphenol is leaning on current operating strength to support both reinvestment and shareholder returns.
- We will now look at how Amphenol's sharply higher 2026 sales guidance could reshape the existing investment narrative around growth and margins.
Scan hand-picked peers that may be similar to Amphenol's mix of rapid top line expansion and rising cash returns through our 38 high quality undervalued stocks.
Amphenol Investment Narrative Recap
To own Amphenol, you need to believe that high demand for interconnects in AI data centers, defense and industrial equipment can support both strong volumes and solid margins for a long time. The latest 2026 guidance, with about 60% higher sales expected versus last year, keeps that growth story intact and strengthens the near term revenue catalyst.
The near term risk still sits in any cooling of AI related IT datacom or slower integration benefits from CommScope at today’s scale. Higher ongoing taxes could also bite into net income. The new guidance does not remove these issues, but it does not materially worsen them either.
The most relevant update for that thesis is the new 2026 outlook. Management now expects US$10.3b to US$10.5b of fourth quarter sales and US$36.9b to US$37.1b for the full year, with GAAP EPS of US$0.80 to US$0.82 for Q4 and US$2.64 to US$2.66 for 2026.
For investors, the key question is whether Amphenol can execute at those levels while keeping margins and cash generation healthy, especially with high exposure to AI focused IT datacom and a meaningful debt load. That guidance turns into a near term test of operational discipline and demand resilience rather than a reset of the whole story.
Amphenol's narrative projects US$53.0b revenue and US$11.7b earnings by 2029. This assumes revenue grows at 17.0% per year and earnings rise by about US$5.8b from US$5.9b today.
Uncover why Amphenol's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts more weight on pressure in legacy communications networks. Before this Amphenol update, the lowest analysts were modelling around US$53.4b of 2029 revenue and about US$10.1b of earnings, with limited P/E expansion. That group paints a more cautious story, so it can be useful for you to compare several angles before deciding what this new guidance might mean.
Explore 6 other Amphenol fair value estimates, including one that suggests it could be worth just $85.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own research and judgment.
- A great starting point for your Amphenol research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amphenol. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amphenol's overall financial health at a glance.
Looking for more investment ideas beyond Amphenol?
Once you have a view on Amphenol, it can help to widen your opportunity set and compare it with other businesses that fit different risk and income profiles. The Simply Wall St Screener lets you do that in a structured way using fundamentals rather than headlines.
- If you want potential upside with strict quality filters, scan a curated group of financially strong opportunities through our 19 high quality undiscovered gems.
- For readers who care most about capital preservation and steadier profiles, focus on companies that screen well on resilience using the 31 resilient stocks with low risk scores.
- If you prefer balance sheet strength and solid fundamentals as your starting point, build a shortlist straight from the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com