


EN
Stanley Black & Decker (SWK) Lifts 2026 Outlook As Buyback Fuels Debate Over Fair Value
Stanley Black & Decker (SWK) is back in focus after stronger than expected third quarter results, tariff refunds and a higher 2026 earnings outlook, combined with a fresh US$1b share repurchase authorization.
Recent news appears to have reset expectations around Stanley Black & Decker, with the share price climbing 29.67% over the past month and 50.19% year to date, while the 1-year total shareholder return of 75.45% contrasts with a 5-year total shareholder return that is still down 29.78%, signaling strong recent momentum after a tougher multi year stretch.
Scan for other industrial stocks showing similar momentum and capital return stories with our hand picked 38 high quality undervalued stocks, which pairs balance sheet strength with cash flow support.
After a 50% year to date jump and a fresh US$1b buyback in play, the question around Stanley Black & Decker now is simple: Is most of the upside already priced in, or not yet?
Most Popular Narrative: 15% Overvalued
The most followed view on Stanley Black & Decker compares a fair value of $100 to the last close at $114.85, which puts the stock at a clear premium and makes execution on its margin plan critical.
The multi-year supply chain transformation has progressed into a margin program where adjusted gross margin reached 33.7% in Q2 2026. Management is now targeting 34% to 35% in the second half of 2026 and 35% to 37% by the end of 2028. Product platforming, lean labor productivity and manufacturing footprint consolidation are expected to support net margin and earnings expansion.
See why 39 investors see Stanley Black & Decker as 15% overvalued.
Result: Fair Value of $100 (OVERVALUED)
Still, the Stanley Black & Decker story can wobble if footprint cuts disrupt factories or if the ongoing securities class action reduces cash and diverts management’s focus.
Find out about the key risks to this Stanley Black & Decker narrative.
Another View: What Stanley Black & Decker’s P/E Is Saying
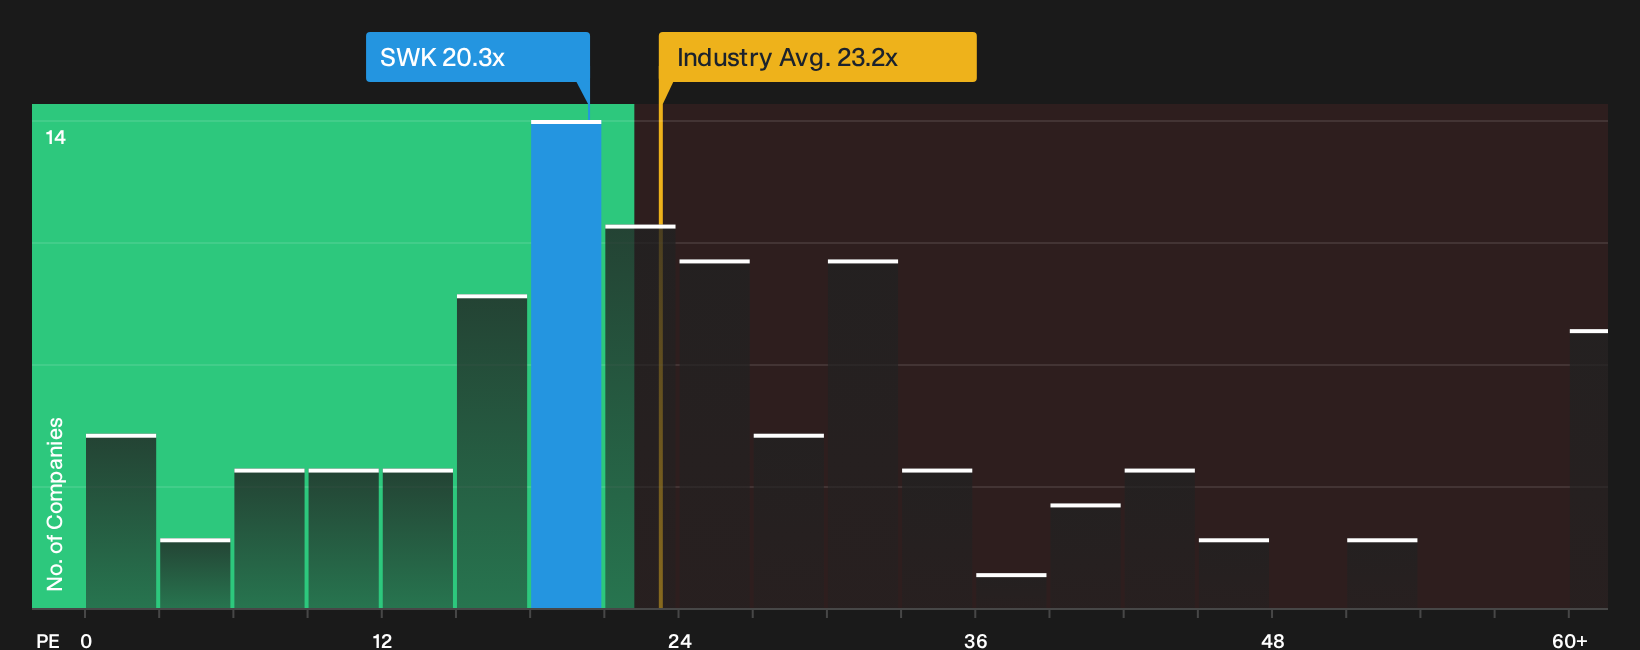
On price targets and fair value models, Stanley Black & Decker looks around 15% overvalued. On earnings multiples, the picture shifts. SWK trades on a P/E of 20.3x, while the Machinery industry sits at 23.2x and direct peers average 26.7x.
The fair ratio for SWK is 22.9x, which is above today’s 20.3x. That gap suggests the market is paying less for each dollar of earnings than both peers and the level the fair ratio points to. Is that a margin of safety or a signal that expectations on growth and returns are still cautious?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Stanley Black & Decker are clear. If you care about both the upside story and the red flags, move fast and stress test the thesis against the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Stanley Black & Decker?
If you are serious about building a stronger portfolio, do not stop at Stanley Black & Decker. Use focused screeners to surface ideas you might otherwise miss.
- Target potential mispricing by scanning a curated list of companies with strong fundamentals using our 38 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused set of high yield opportunities through the 7 dividend fortresses.
- Prioritise resilience by searching for companies with robust financial footing via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com