


EN
Strong Earnings Report Might Change The Case For Investing In Raymond James Stock (RJF)
- Raymond James Financial reported fourth quarter 2026 revenue of US$4,739 million and net income of US$666 million, with full year revenue of US$17,539 million and net income of US$2,368 million, all higher than the prior year period.
- The firm completed a US$949.28 million share repurchase program covering 6,117,504 shares, indicating active capital return alongside rising earnings per share from continuing operations.
- Next, the focus shifts to how Raymond James Financial's higher quarterly and full year earnings may shape the broader investment narrative.
Compare Raymond James Financial's latest earnings and buyback activity with other companies returning capital to shareholders by scanning the 7 dividend fortresses for income-focused ideas with staying power.
Raymond James Financial Investment Narrative Recap
To own Raymond James Financial, you need to be comfortable with a business that is heavily tied to client activity, capital markets conditions and net interest income from its bank segment. The latest quarter shows higher revenue and earnings alongside growing full year figures, which supports that core wealth and banking franchise. The key near term swing factor remains market volatility, since deal flow and trading can shift quickly.
The biggest risk still sits in external shocks that hit investment banking, fixed income trading and client sentiment at the same time. Legal and professional costs are another pressure point if they stay elevated. The recent results do not remove those issues, although solid earnings give the firm more room to keep funding technology, adviser recruitment and its banking expansion.
The most relevant recent announcement is the completion of the US$949.28 million buyback covering 6,117,504 shares, including US$50 million of repurchases in the September quarter. For an investor, the key link is between that capital return and the higher basic and diluted earnings per share from continuing operations that the latest quarter and full year report.
Share count moving lower can amplify the effect of any future earnings progress, but only if the core operations continue to hold up against the risks around deal activity, interest rate shifts and legal spend. When you weigh Raymond James Financial today, it is really a question of how you view that combination of adviser led growth, bank scale and ongoing repurchases against those operational and market sensitivities.
Raymond James Financial's narrative projects US$18.7b revenue and US$2.8b earnings by 2029. That profile lines up with analysts assuming revenue growth of 5.7% per year and an earnings increase of about US$0.4b from US$2.4b today.
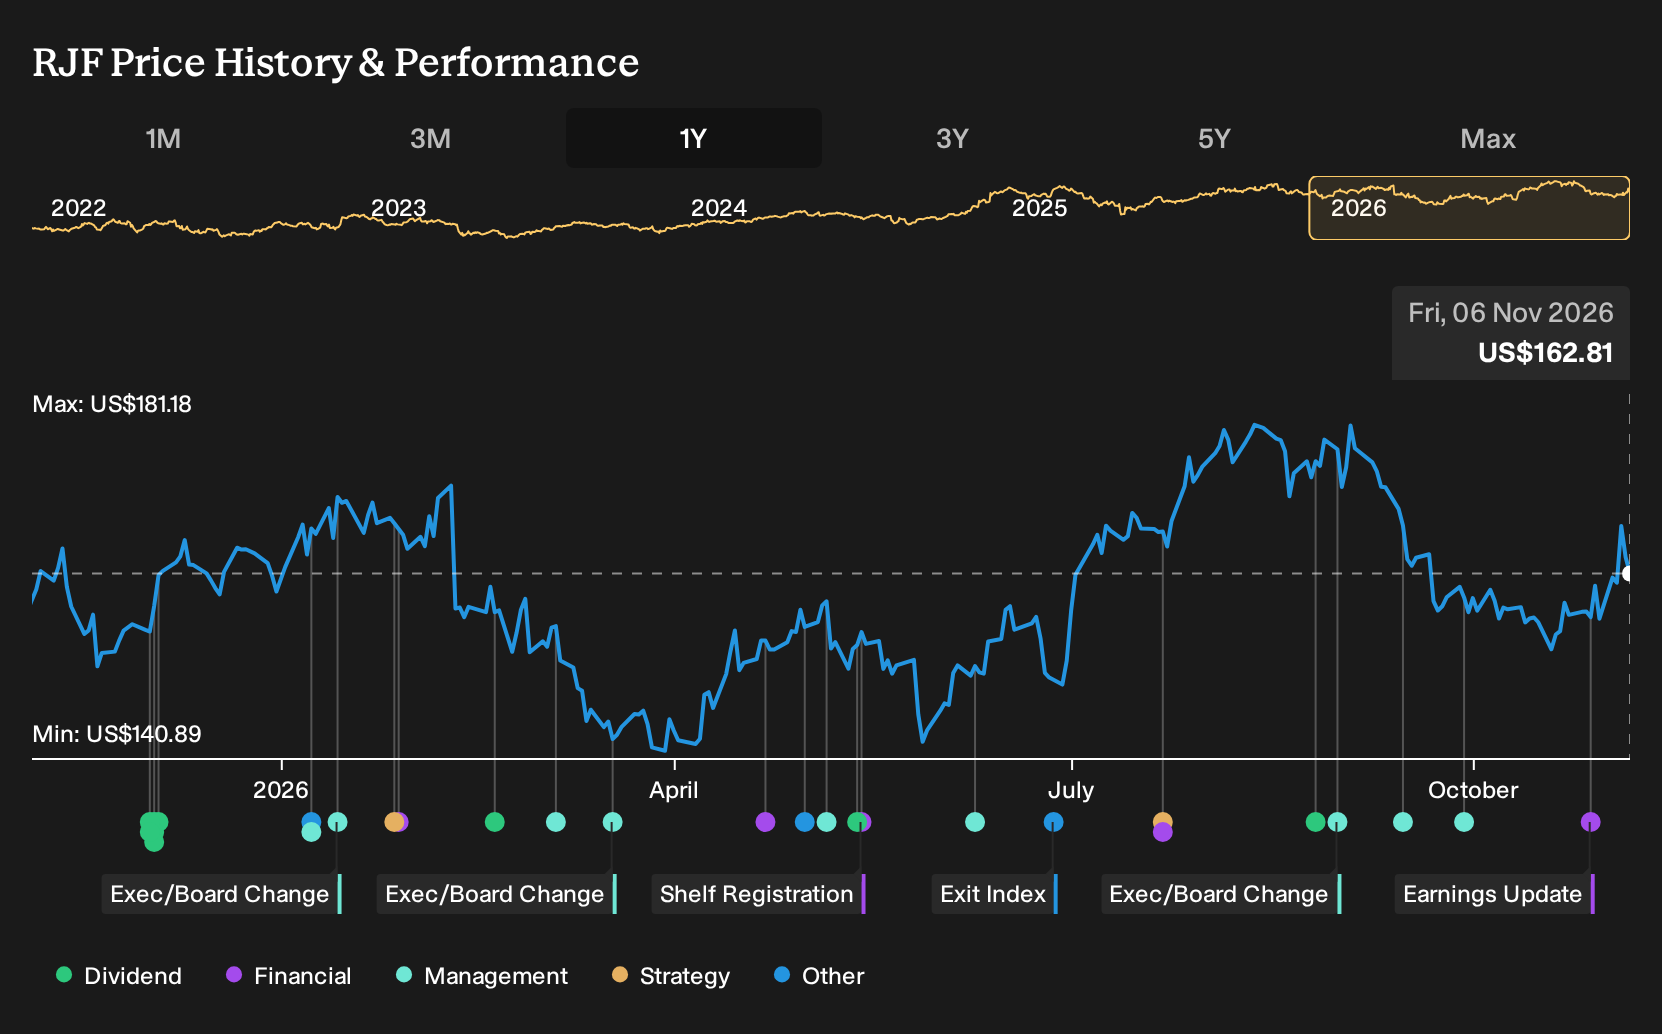
Uncover why Raymond James Financial's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$182 at the low end to about US$282 at the top, which already shows how far opinions on Raymond James Financial can spread. Compare those crowd estimates with tariff and interest rate uncertainty and rising legal costs, then decide which narrative you find more convincing.
Explore another Raymond James Financial fair value estimate, including one that suggests potential upside of as much as 73% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Raymond James Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Raymond James Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Raymond James Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Raymond James Financial?
Once you have a view on Raymond James Financial, it can help to compare that thesis with other opportunities that match the kind of risk, income, or balance sheet profile you prefer. The Simply Wall St Screener lets you quickly line up different companies against the same criteria so you can pressure test your thinking across a broader watchlist.
- If you care most about durability and consistent cash generation, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially resilient businesses.
- For investors who want a bit more upside potential without ignoring quality, scan a 19 high quality undiscovered gems to uncover companies that may not yet be widely followed.
- If your priority is keeping volatility in check, filter for defensiveness through a 31 resilient stocks with low risk scores that screens for stocks with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com