


EN
How Strong Earnings Growth Will Impact TowneBank (TOWN) Stock
- TowneBank reported third quarter 2026 net interest income of US$196.21 million and net income of US$81.78 million, with basic EPS from continuing operations at US$0.89.
- The bank reported higher earnings for both the quarter and the first nine months of 2026 while absorbing a sharp rise in net charge offs to US$2.45 million.
- This article examines how TowneBank's earnings performance in the face of higher credit costs may influence the investment narrative for the business.
Scan how TowneBank's latest quarter stacks up against peers by reviewing a hand picked list of solid balance sheet and fundamentals (25 results) that reflects this mix of higher earnings and rising credit costs.
What Is TowneBank's Investment Narrative?
TowneBank's story today is about a fairly traditional regional bank model that is currently generating strong earnings. The third quarter print, with US$196.21 million in net interest income and US$81.78 million in net income, suggests the lending and deposit engines are working efficiently. For many shareholders, the belief is simple: management can keep turning that core banking machine into solid profits while maintaining a 3.08% dividend and a P/E of 9.3x that sits below both peer and industry averages.
The sharp move in net charge offs to US$2.45 million brings the real tension into focus. Credit costs are no longer a rounding error, even if earnings and net interest income for the first nine months of 2026 remain strong at US$554.27 million and US$315.96 million respectively. In the short term, the key question is whether TowneBank can hold this earnings power if revenue and profit are forecast to decline over the next three years while also managing shareholder dilution that has already occurred.
Yet the more interesting part of the TowneBank story is the single operational pressure point that could turn this solid quarter into a warning sign...
There's only one way to know the right time to buy, sell or hold TowneBank. Head to Simply Wall St's company report for the latest analysis of TowneBank's Fair Value.
Exploring Other Perspectives
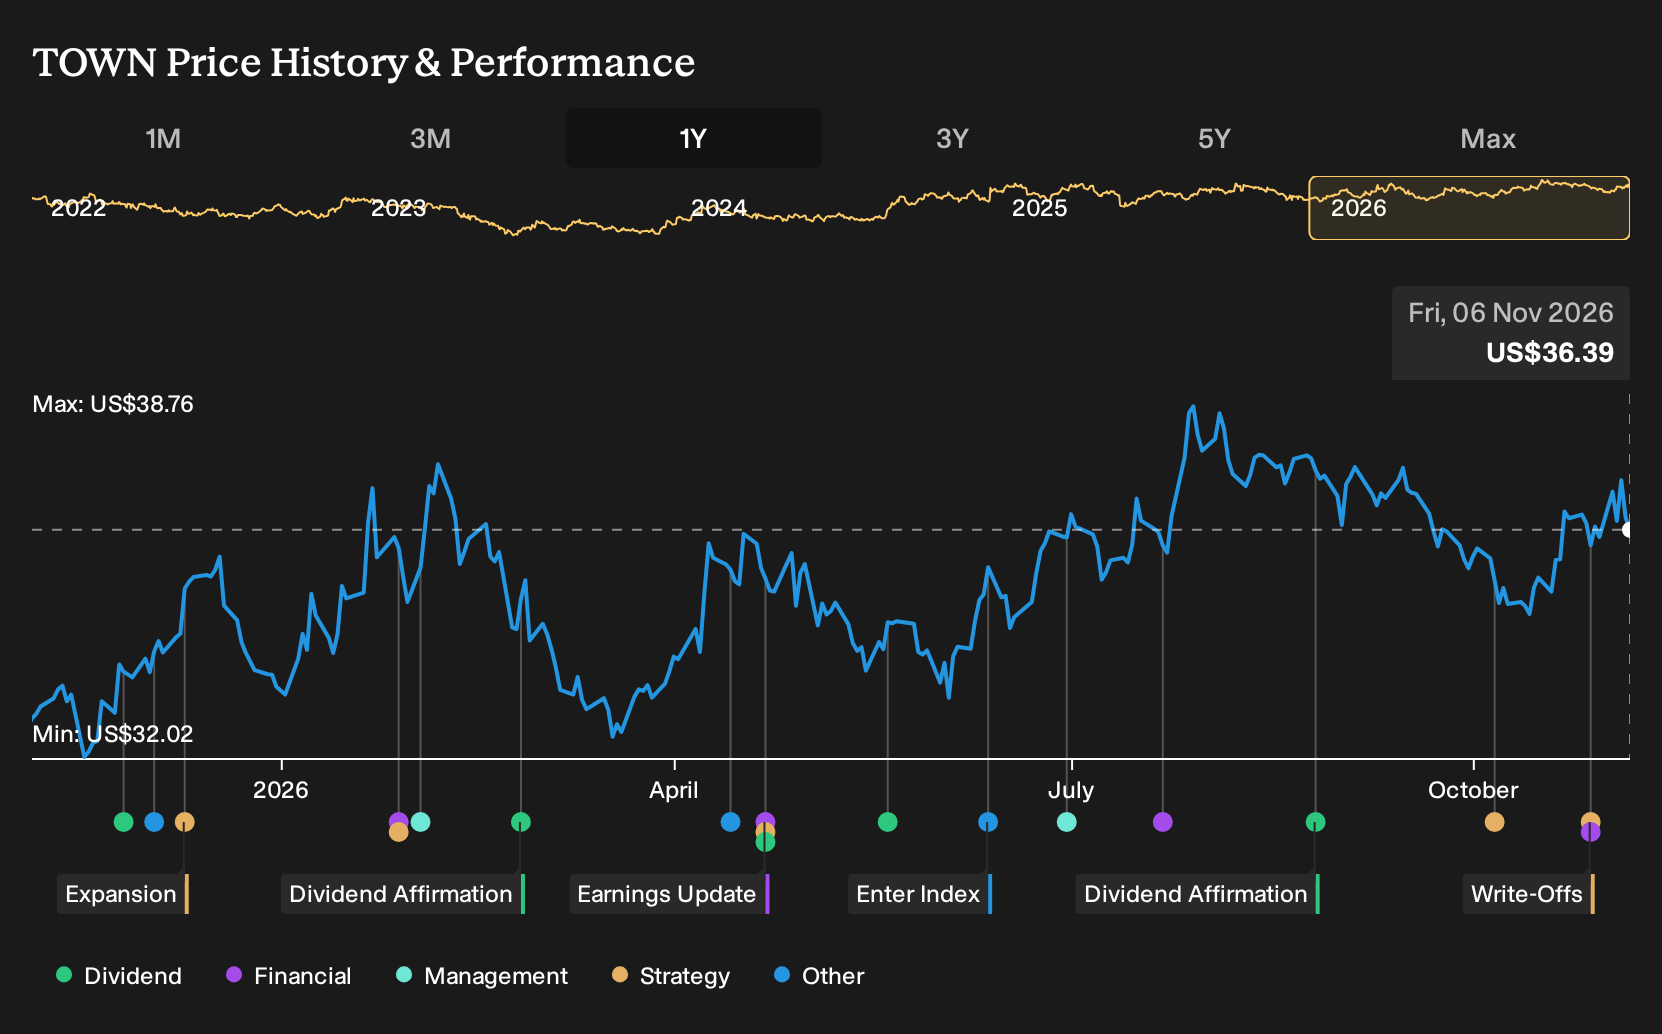
TowneBank attracts only 2 fair value estimates from the Simply Wall St Community, clustered in a tight US$39.33 to US$40 band. You are seeing a narrow slice of opinion. The sharp jump in net charge offs to US$2.45 million, reported on 28 October 2026, gives you a fresh reason to compare more viewpoints before deciding what this earnings profile really means.
Explore another TowneBank fair value estimate, including one that suggests upside of as much as 10% from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TowneBank research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TowneBank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TowneBank's overall financial health at a glance.
Looking For More TowneBank Style Investment Ideas?
If TowneBank's mix of earnings strength and credit costs has you thinking about portfolio balance, it can help to look at a wider field of opportunities with similar financial traits using the Simply Wall St Screener.
- For investors who want income that is backed by robust cash generation, consider a curated set of high yield payers with resilient fundamentals through the 7 dividend fortresses.
- If capital preservation and steadier risk profiles matter most to you, focus on companies that show resilient financial health and relatively lower risk scores via the 31 resilient stocks with low risk scores.
- When you are hunting for companies with strong balance sheets and solid underlying business quality, broaden your watchlist using a carefully filtered 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com