


EN
IMAX (IMAX) Could Be 19% Undervalued As Earnings Reset The Valuation Debate
IMAX earnings surge puts focus on box office power
IMAX (IMAX) just posted third quarter 2026 earnings that drew attention, with revenue of US$174.55 million and net income of US$113.81 million, tied to strong box office performance and a wider theater footprint.
IMAX shares have cooled off in the short term, with the 7 day share price return down 5.81% and the 30 day share price return down 6.16%. At the same time, the year to date share price return sits at 32.34% and the 3 year total shareholder return reaches 171.62%. This points to long term momentum but a recent reset in expectations as investors reassess box office strength, expansion plans and what they are willing to pay for the story at US$47.67 a share.
Seize this earnings momentum theme by screening for other premium, experience driven media stocks using our hand picked 19 high quality undiscovered gems.IMAX just delivered blockbuster quarterly numbers yet the share price has cooled off, which leaves a simple fork in the road. Is most of the upside already reflected, or is the market still discounting this earnings reset?
Most Popular Narrative: 19% Undervalued
On the most followed view, IMAX is worth $59.17 a share using a 9.06% discount rate, compared with the latest close at $47.67. That gap frames the earnings jump as part of a longer story built around screens, content and cash generation rather than a one quarter surprise.
Rapid acceleration of new system installations and a replenishing, geographically diverse backlog supported by an estimated addressable market of 4,500 screens versus about 1,800 currently in operation points to further IMAX network expansion that could lift box office driven revenue and recurring cash flows as more locations contribute.
See why 9 investors see IMAX as 19% undervalued.
Result: Fair Value of $59.17 (UNDERVALUED)
Still, if streaming and gaming keep pulling viewers from cinemas, or a thin blockbuster slate returns, the IMAX earnings story investors are paying for could fray.
Find out about the key risks to this IMAX narrative.
Another View: IMAX on earnings multiples
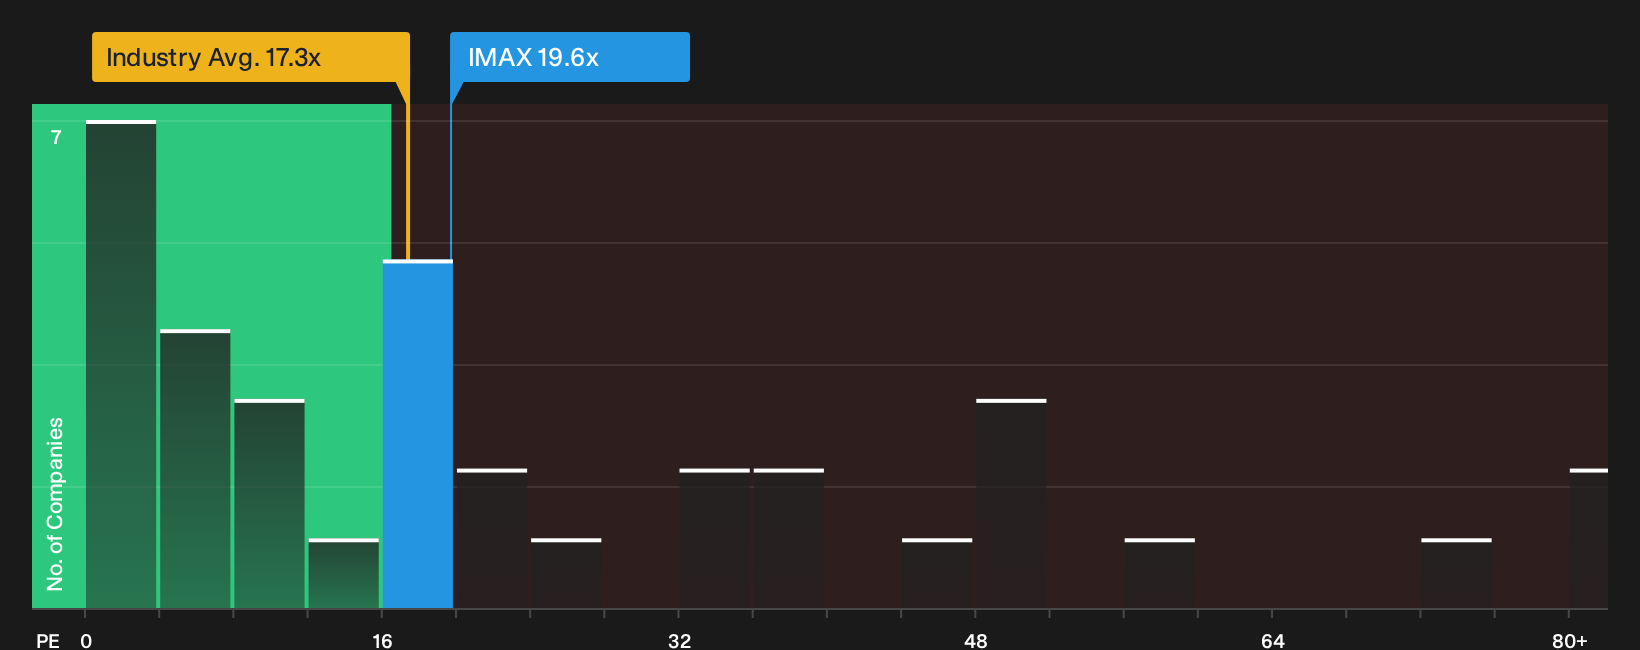
The story looks different when you swap the cash flow lens for simple earnings math. IMAX trades on a P/E of 19.6x, above the US Entertainment industry on 17.3x and roughly double its own fair ratio of 9.5x. That gap points to richer expectations. Is that premium comfort or risk to you?
See what the numbers say about this price in our valuation breakdown, then compare how IMAX stacks up against similar stocks using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this IMAX story appears finely balanced between promise and risk, consider acting while the data is fresh and pressure test it yourself with 3 key rewards and 3 important warning signs.
Looking for more IMAX style investment ideas?
IMAX might have your attention today, but your next compelling opportunity probably sits elsewhere on the market, and you do not want to spot it late.
- Hunt for mispriced quality and scan our universe of solid fundamentals using the 38 high quality undervalued stocks.
- Lock in income potential while checking balance sheet strength by reviewing the 7 dividend fortresses.
- Reduce portfolio stress and focus on sturdier businesses by filtering for the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com