


EN
Missed Dentsu Group's Run? What Holders Had To Believe
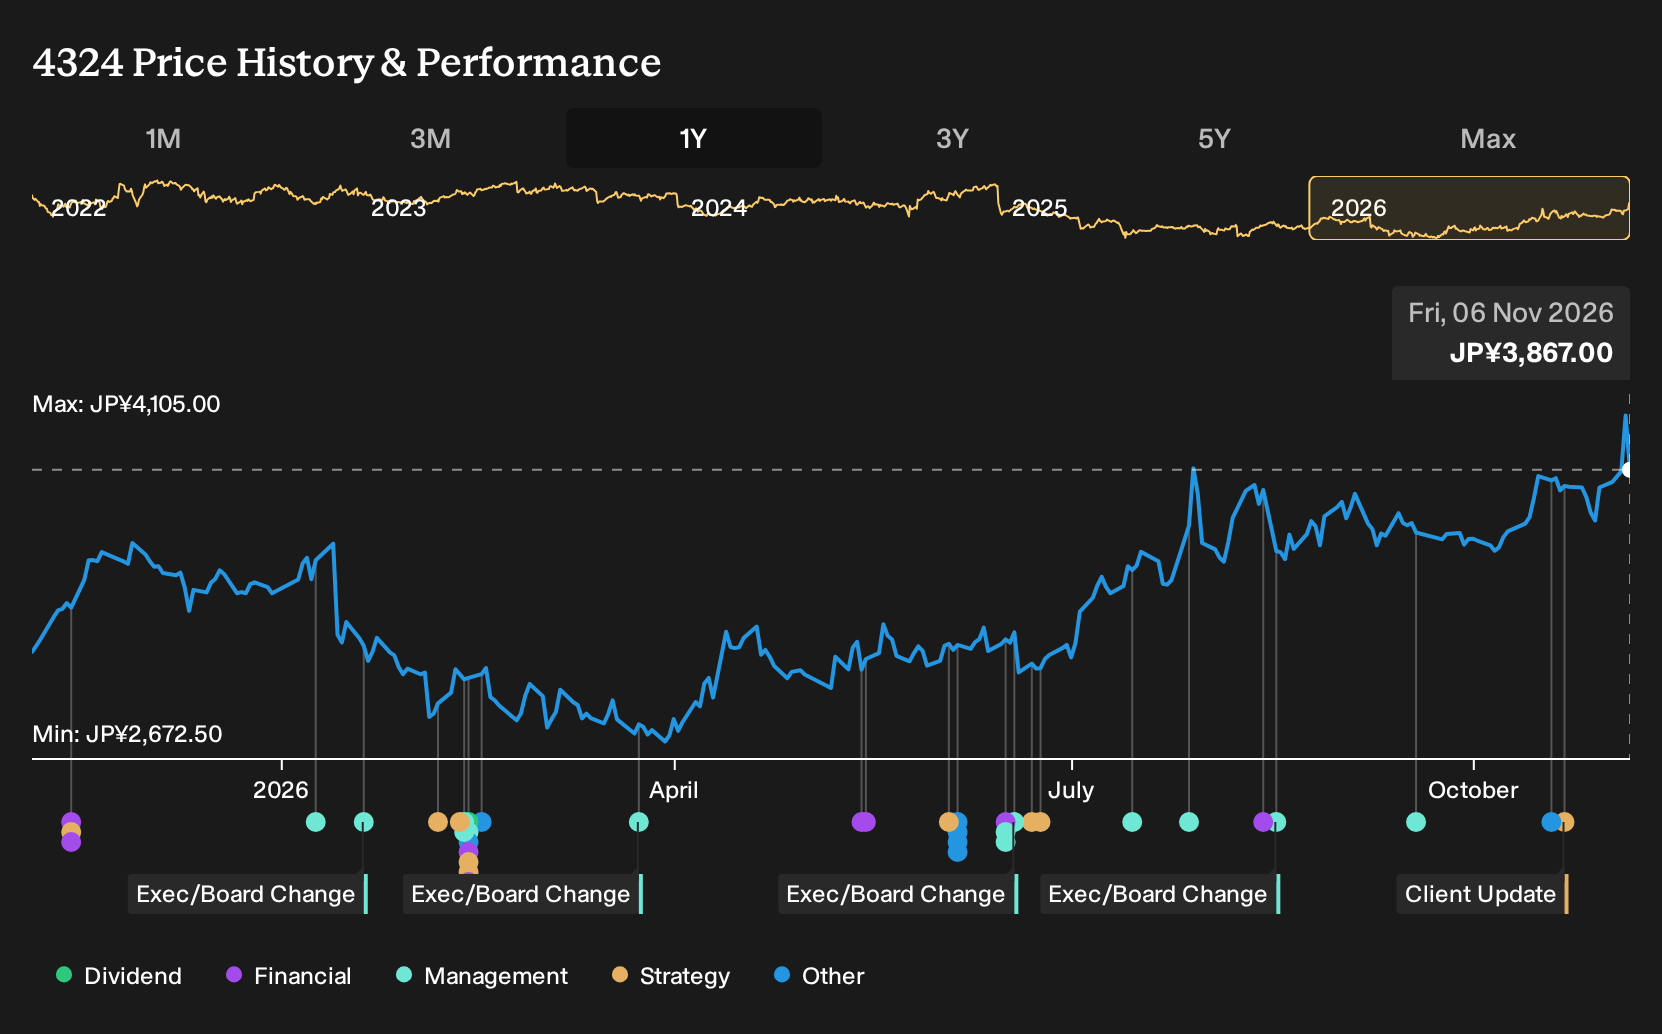
If you only glanced at Dentsu Group’s headlines over the past year, the payoff from simply sitting still might come as a surprise. Investors who held Dentsu Group over the past year are up 23.8%, including dividends. If you had been weighing those sharply different analyst views in November 2025, with bulls leaning on AI and APAC growth and bears focused on privacy and in-housing risks, what exactly did that outcome test about the business story you were buying into?
If the move has made Dentsu Group harder to judge, start where the gap is still open and scan 26 high quality undervalued stocks.
The Two Stories Investors Were Really Choosing Between On Dentsu Group
The shares cost ¥3,087 at the start of the period, and anyone buying Dentsu Group then had to decide which future felt more believable.
On the bullish side, the Digitalization And AI Integration Will Fuel APAC Expansion Globally story pointed to a Fair Value of ¥4,600, a price level implied by assumptions of faster AI driven margin gains and earlier earnings recovery. That view leaned heavily on proprietary data, automated platforms, and APAC exposure as engines for higher revenue and profit margins.
The bearish narrative, Rising Privacy Regulations Will Cripple Digital Advertising, anchored on a Fair Value of ¥2,400 based on more cautious expectations. This perspective focused on the possibility that tougher privacy rules, brands bringing media buying in house, and big tech competition could steadily weaken Dentsu Group’s access to data, compress fees, and limit long term digital growth.
What The Results Put To The Test For Dentsu Group
Dentsu Group’s Q2 2026 numbers gave the bullish profit recovery story some backing, with revenue at ¥360,223m and net income swinging from a loss of ¥79,916m in Q2 2025 to a ¥6,124m profit. Net margin moved from a -23.6% loss to a 1.7% profit, so profitability improved but stayed modest, meaning the optimistic margin case is only partly supported.
The takeaway is simple. When a thesis leans on margin repair, you track net income direction and net margin closely, then judge how far they move toward the target profile analysts were promoting.
What Dentsu Group’s Current Price Already Assumes
Dentsu Group now trades at ¥3,867. The selected Narrative’s Fair Value sits below the current price, presented as a view that today’s level already reflects a successful earnings rebuild.
That depends on international operations turning restructuring and AI tools into steadier growth and healthier margins. How does the risk of prolonged overseas weakness affect that assumption?
"The main thing that has to go right is that Dentsu Group turns its multi-year restructuring, cost reductions and AI deployment into a sustained margin rebuild, while reinvesting enough to stabilise media and CXM growth outside Japan. The current valuation implies Dentsu Group is priced for successful recovery in overseas growth and profitability despite extended timing on margin targets, goodwill write-downs and an absence of dividends."
One Narrative disagrees with today's price. → See where this Narrative says Dentsu Group should trade
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 43% below our estimate - offers low code tools that replace spreadsheet workflows for internal business processes.
- Company 2 - 22% below our estimate - expands recurring maintenance contracts while layering remote diagnostics and media services into elevators.
- Company 3 - 24% below our estimate - sells regional sweets through branded outlets and related products while also broking insurance policies.
Those are three of them. See the full list of 23 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com