


EN
Azenta (AZTA) Expands GENEWIZ With New Deals, Is The Recovery Already Priced In?
Why Azenta’s latest move matters for GENEWIZ and synthetic biology
Azenta (AZTA) has put fresh capital and attention into its GENEWIZ unit by striking an exclusive DNA technology license with Elegen and buying SynPlexity to widen its synthetic biology toolkit.
The announcement gives GENEWIZ access to cell free DNA manufacturing, sequence verified constructs, and pooled gene libraries that support larger experiment sets, including AI generated designs, across drug discovery and protein engineering workflows.
Azenta’s latest GENEWIZ deal arrives with the share price at US$39.16, supported by a 17.5% 90 day share price return and a 33.3% total shareholder return over the past year. However, the 3 and 5 year total shareholder returns show sizeable declines, so recent momentum contrasts with a weaker long run record.
See how other lab-tech and synthetic biology players are positioning for AI-driven discovery with a curated list of 35 healthcare AI stocks.
Azenta has just equipped GENEWIZ with new tools, and the share price already reflects a strong 1-year rebound. Is there still significant upside potential ahead, or has most of it already appeared in the chart?
Most Popular Narrative: 19% Overvalued
Azenta closed at $39.16 while the most followed narrative anchors fair value at $33.00. The story leans toward the market baking in a recovery that still needs to be earned.
The main thing that has to go right is that Azenta converts its higher recurring revenue mix, Multiomics overhaul, and refocused portfolio into consistent organic growth without further guidance resets or governance setbacks.
The numbers around guidance cuts, goodwill write downs, and the stock reaction to the August 2026 CEO resignation imply that the current share price already assumes a recovery that this narrative views as too optimistic, leaving Azenta overvalued and exposed if execution disappoints.
See why 0 investors see Azenta as 19% overvalued.
Result: Fair Value of $33 (OVERVALUED)
Still, a tighter focus on gene synthesis and early traction in higher margin multiomics workflows could soften the impact of goodwill write downs and weaker FY26 guidance.
Find out about the key risks to this Azenta narrative.
Another View: What Azenta’s multiples are implying
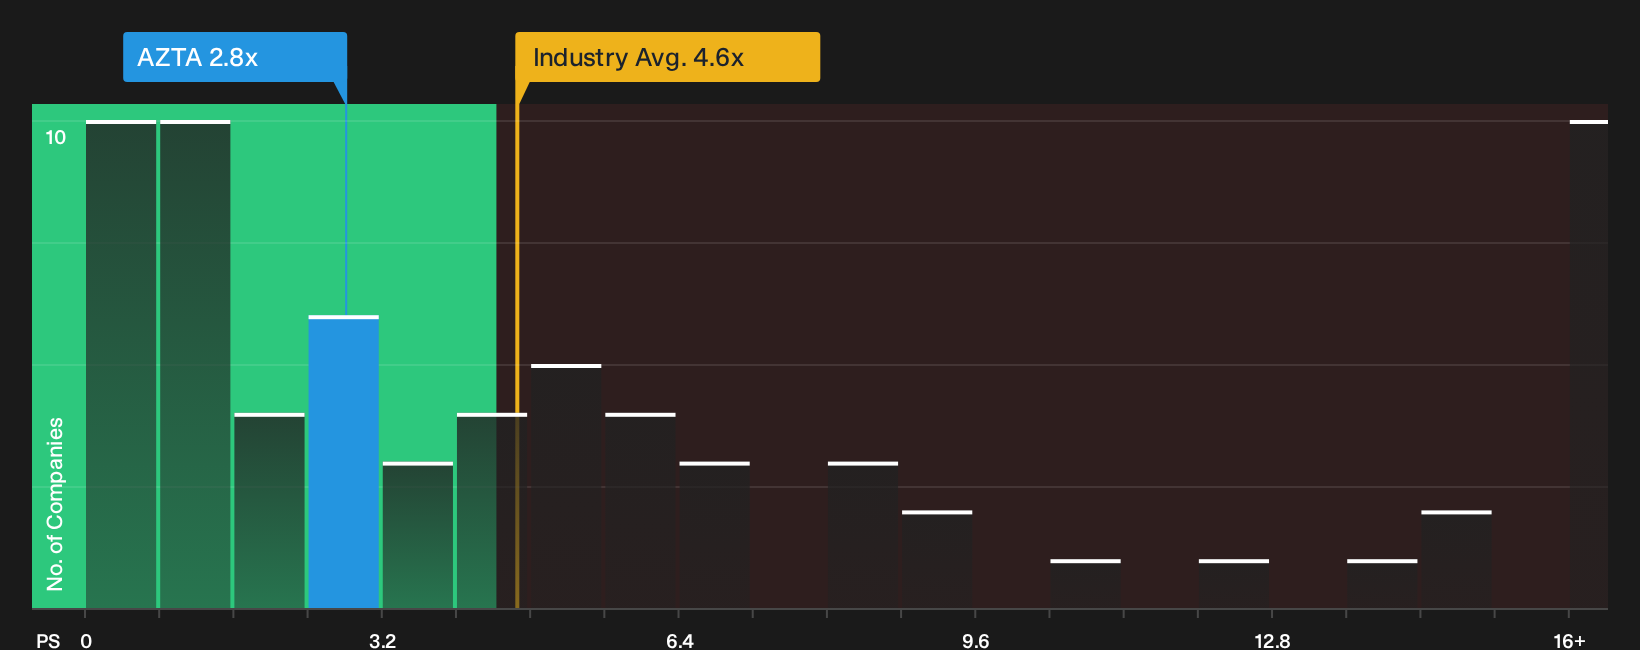
That bearish fair value of $33 from the narrative sits awkwardly next to how Azenta is actually priced on sales. The P/S ratio sits at 2.8x, while peers trade around 11.1x and the wider US Life Sciences group sits near 4.6x. The fair ratio is 3x, which is only a small step above where the stock is now. For investors, that gap suggests less of a clear mispricing and more of a debate. Is the discount a cushion against execution risk, or a signal that expectations still need to cool further?
For a deeper look at what the numbers imply about this pricing gap, including how the fair ratio could shift as new data arrives, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data so far. If you want to move fast but think independently and weigh the risks, then see what our work highlights through 2 key rewards.
Looking for more Azenta investment ideas?
If Azenta has you thinking more broadly about opportunities, do not stop at one ticker. Use targeted screeners to surface new ideas before they show up on most radars.
- Target potential mispricings by running through a focused shortlist of quality stocks that trade below fair value with the 38 high quality undervalued stocks.
- Prioritise resilience by scanning companies that pair sturdy finances with measured risk using the 31 resilient stocks with low risk scores.
- Hunt for under-the-radar opportunities that already have solid fundamentals by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com