


EN
Argan (ENXTPA:ARG) Just Gave Investors Something To Think About
Argan (ENXTPA:ARG) just cut the ribbon on a 41,000 sqm logistics hub in Vendenheim for PUMA’s B2B flows in France, putting fresh attention on the warehouse landlord’s regional footprint.
Against this new Vendenheim asset, Argan’s share price has softened over the last three months, with a 90 day share price return down 8.16%, even though the year to date share price return is up 3.85% and the 1 year total shareholder return is 7.27%. This suggests recent momentum has faded even as longer term holders have still seen a positive outcome.
Scan beyond Argan and this new PUMA hub by reviewing a curated group of logistics and real estate landlords with resilient balance sheets in the list of solid balance sheet and fundamentals (193 results).
Argan’s shares have cooled even as it adds assets like Vendenheim and trades below published analyst targets. Is the recent pullback setting up more upside, or did most of the rerating already occur?
Most Popular Narrative: 17% Undervalued
The most followed narrative pegs Argan’s fair value at €81 versus a last close of €67.5, so it treats the recent share pullback as an entry at a discount.
The planned merger with WDP to form a €13b+ logistics platform across eight countries, with a medium term ambition to reach €20b in assets, could widen Argan’s tenant base and deal pipeline. This may support rental revenue and EPRA EPS growth for the combined group.
Expected 3% EPRA EPS accretion from the first full year of combined operations in 2028, driven by €10m of anticipated annual cost synergies and €250m of projected non core disposals, is presented as a clearer route for earnings growth relative to Argan’s current standalone P/E multiple.
See why 1 investors see Argan as 17% undervalued.
Result: Fair Value of €81 (UNDERVALUED)
Still, the Argan story hinges on the WDP merger delivering the planned synergies, and on today’s rich P/E multiple not compressing if sentiment cools.
Find out about the key risks to this Argan narrative.
Another View: Argan Through Our DCF Lens
The analyst narrative sees Argan as 17% undervalued at a fair value of €81, yet the SWS DCF model points in the opposite direction. On that cash flow view, Argan at €67.5 sits above an estimated value of €50.23, which frames the shares as overvalued rather than cheap. Which story do you trust more: the earnings multiple or the cash flow math?
To unpack how this cash flow based result is built and what would need to change for Argan to look cheaper on this lens, Look into how the SWS DCF model arrives at its fair value.
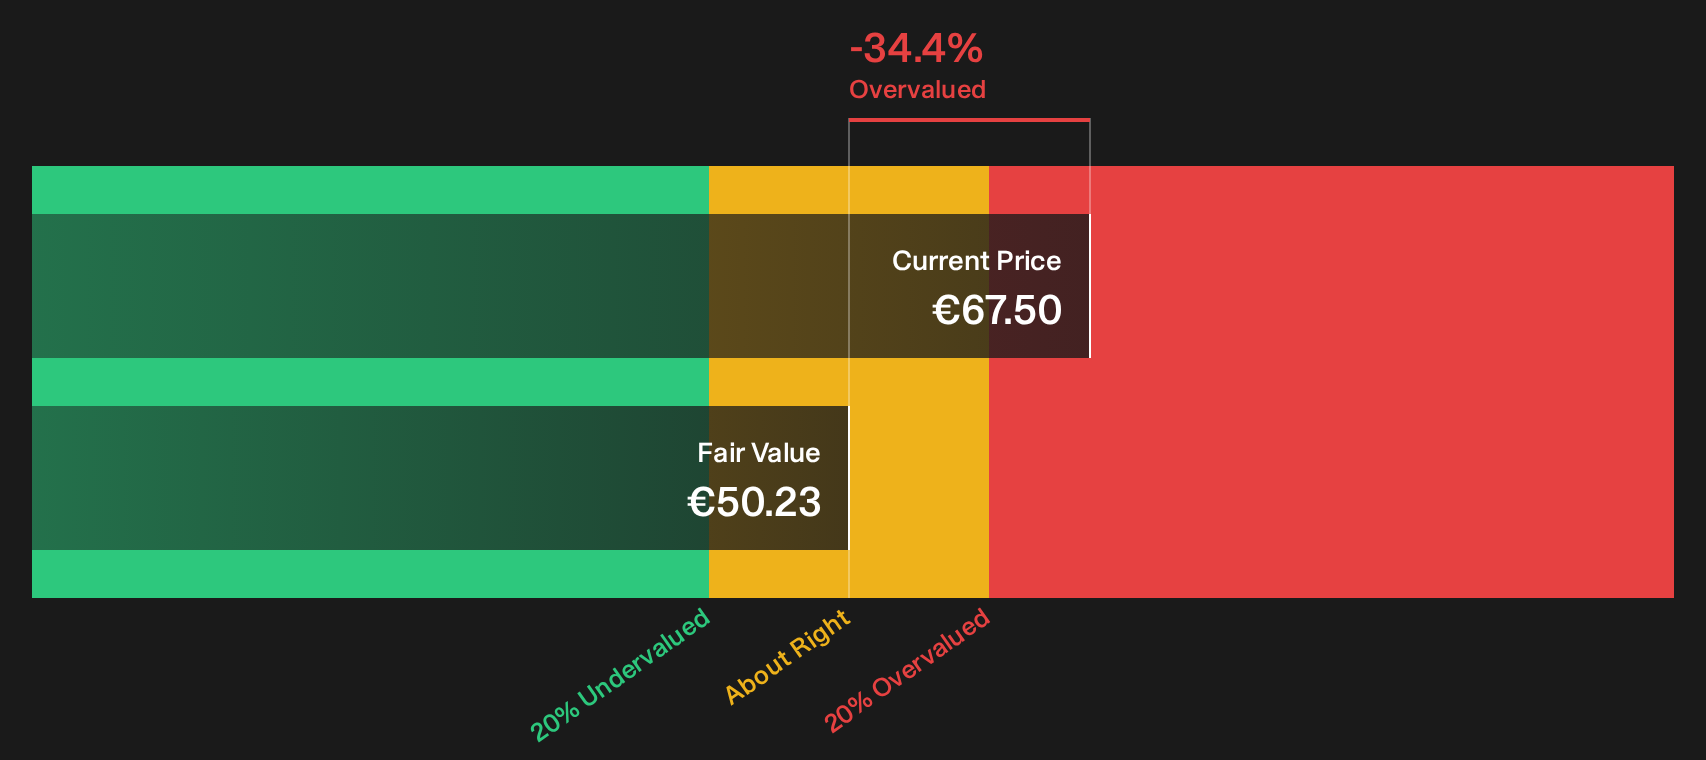
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Argan for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 226 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Argan’s valuation can be confusing. Consider reviewing the underlying data for yourself, then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Argan?
Do not stop your research with Argan. Fresh opportunities often appear where capital has not fully paid attention yet, and missing them can hurt long term returns.
- Target resilient performers that aim to protect capital through different conditions by reviewing a curated 208 resilient stocks with low risk scores.
- Hunt for mispriced potential where quality and valuation intersect by scanning the 573 high quality undiscovered gems.
- Build a watchlist of potential future compounders by checking a focused 126 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com