


EN
Earnings And Dividend May Change The Case For Investing In Restaurant Brands International (QSR)
- Restaurant Brands International reported third quarter 2026 revenue of US$2,525 million and net income of US$542 million, alongside a declared fourth quarter dividend of US$0.65 per share payable in January 2027.
- The combination of higher quarterly earnings and continued cash returns through dividends reflects solid cash generation across Restaurant Brands International's franchised quick service portfolio.
- The next step is to examine how Restaurant Brands International's investment narrative aligns with this stronger earnings report and reaffirmed dividend commitment.
Restaurant Brands International Investment Narrative Recap
For a shareholder in Restaurant Brands International, the core belief is that a global, franchise heavy fast food platform can keep turning system wide sales into dependable earnings and cash. The latest quarter delivered US$2,525 million of revenue and US$542 million of net income, which supports that thesis without radically changing it.
The near term swing factor still sits in day to day execution at Burger King U.S. and Popeyes U.S., where beef inflation and softer traffic have been pressure points. Strong recent earnings soften those worries a bit but do not remove the risk that higher costs or sluggish U.S. demand squeeze margins.
The most relevant fresh data point is the third quarter 2026 earnings release. Revenue for the quarter was US$2,525 million and net income reached US$542 million, with diluted earnings per share from continuing operations at US$1.54. For the first nine months, Restaurant Brands International reported US$7,309 million of revenue and US$1,387 million of net income.
Those numbers matter because they show how the business is converting its international expansion, Burger King U.S. refresh and Tim Hortons menu work into profit while still carrying meaningful debt and commodity cost exposure. Stronger recent earnings give management more room to keep funding remodels and store growth, which ties directly into the key catalysts investors are watching.
Restaurant Brands International Analyst Growth Blueprint
Restaurant Brands International's narrative projects US$10.1b revenue and US$2.2b earnings by 2029. This rests on analysts assuming 1.5% yearly revenue growth and an earnings increase of about US$800m from around US$1.4b today.
Uncover why Restaurant Brands International's fair value indicates an 11% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
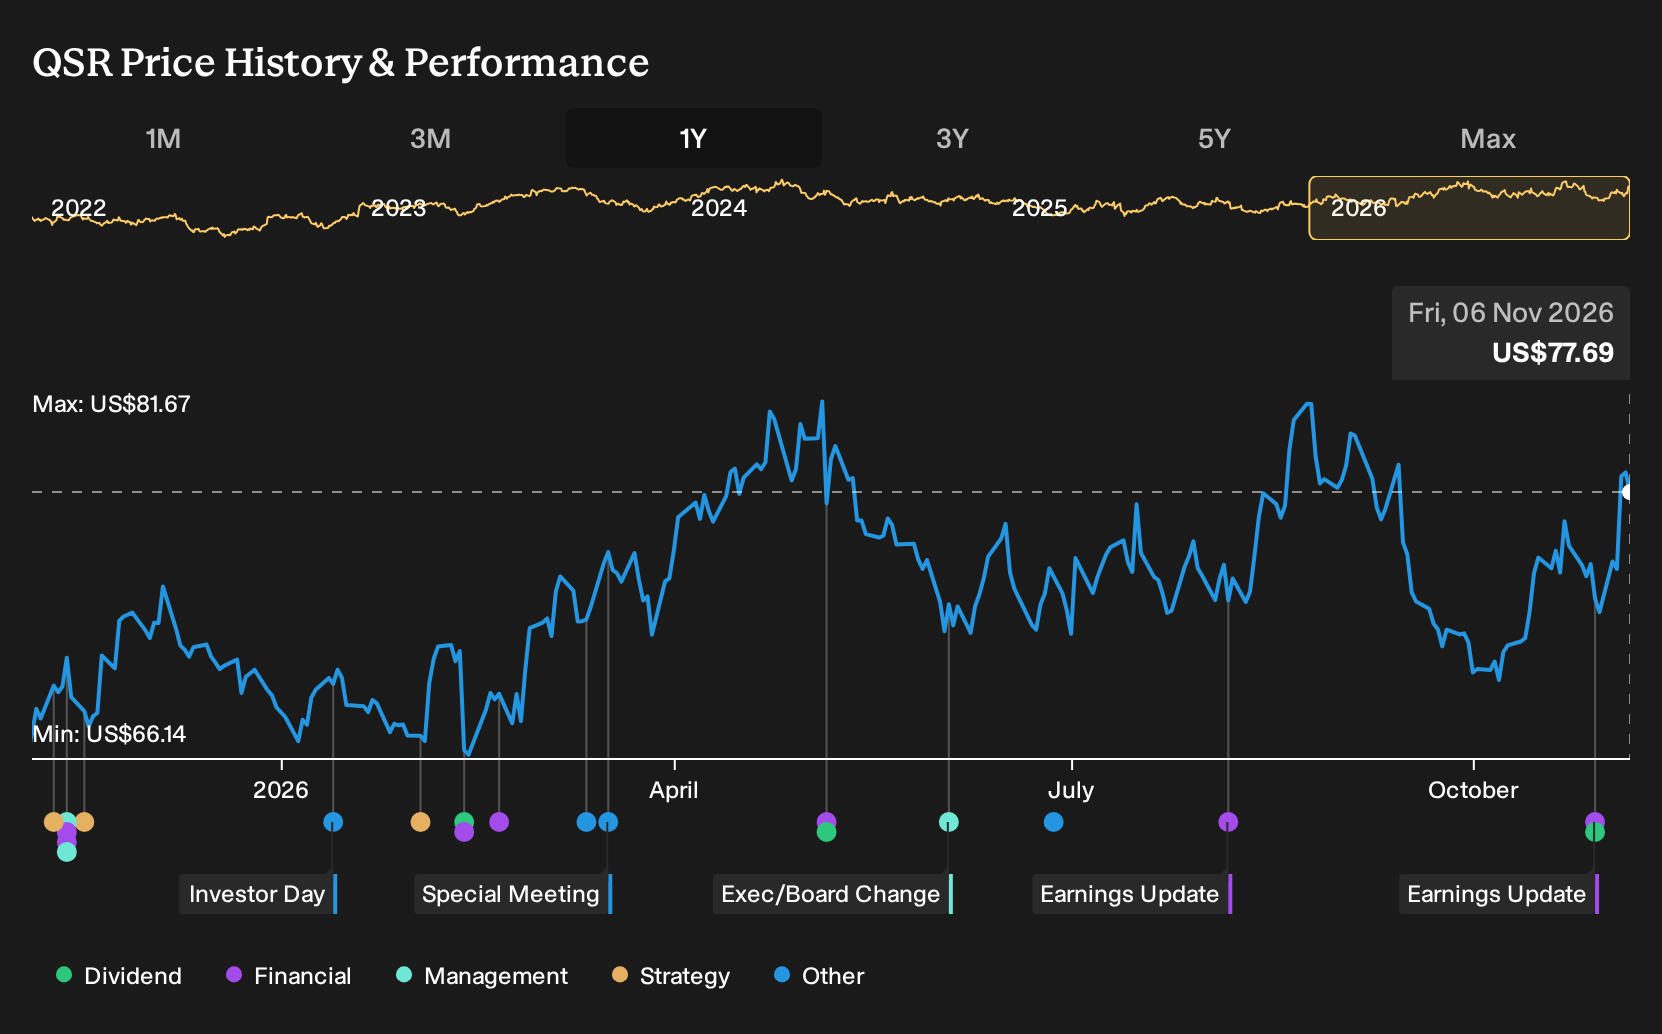
Three fair value estimates from the Simply Wall St Community cluster between about US$78 and US$86 per share, so private investors are not treating Restaurant Brands International as wildly mispriced. You now need to weigh that against fresh earnings strength, the affirmed US$0.65 dividend, and ongoing pressure from U.S. traffic and beef costs.
Explore 2 other Restaurant Brands International fair value estimates, including one that suggests up to 11% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Restaurant Brands International research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Restaurant Brands International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Restaurant Brands International's overall financial health at a glance.
Looking for more investment ideas beyond Restaurant Brands International?
If this latest update on Restaurant Brands International has sharpened your view on income and value, you can use that same lens across the wider market. The Simply Wall St Screener can help you quickly sort through listed businesses so you can focus on the ones that best match your risk tolerance, income goals, and quality filters.
- If capital protection is front of mind, you can start with resilient candidates using our 31 resilient stocks with low risk scores, which are designed to help keep volatility in check while still giving you equity exposure.
- If you want income plus balance sheet strength, you can compare Restaurant Brands International's profile with a curated list of solid balance sheet and fundamentals (25 results) that filters for robust financial footing and consistent fundamentals.
- If you are hunting for potential mispriced opportunities, you can broaden your watchlist with a 38 high quality undervalued stocks that blends quality metrics with valuation checks to highlight ideas for further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com