


EN
BJ's Restaurants (BJRI) Could Be 26% Undervalued Following Raised Guidance
BJ's Restaurants (BJRI) just turned in its ninth straight quarter of same-store sales and traffic gains, plus an eighth consecutive period of profit growth, and used that momentum to lift full-year guidance while trimming net debt.
Even with the upbeat quarter and higher guidance, BJ's Restaurants shares have pulled back sharply in the short term, with the 7-day share price return down 10.97% and the 90-day share price return down 18.91%. However, the 1-year total shareholder return of 59.19% and 3-year total shareholder return of 106.11% point to stronger momentum over a longer stretch.
Scan other consumer-facing stocks showing strong execution and fresh momentum in our handpicked list of 19 high quality undiscovered gems that sit alongside stories like BJ's Restaurants recent run.
BJ's Restaurants now pairs a sharp pullback with stronger guidance and a cleaner balance sheet. Do you lean into that reset today, or wait and hope the valuation gets cheaper?
Most Popular Narrative: 26.2% Undervalued
The most followed narrative on BJ's Restaurants pegs fair value at $75.43, well above the recent $55.67 close. This puts the recent pullback against a still generous valuation gap built on traffic, margins and store economics.
Ongoing menu renovation across key categories such as pizza, burgers and chicken sandwiches, which already account for roughly 25% of sales and carry higher dollar margins after more than US$1.5 million reinvested into quality, provides a visible pipeline to influence sales mix, restaurant-level margins and earnings over the next 12 to 18 months.
See why 1 investors see BJ's Restaurants as 26% undervalued.
Result: Fair Value of $75.43 (UNDERVALUED)
Still, the BJ's Restaurants story can unravel if digital ordering and off premise demand remain underdeveloped or if rising costs squeeze its already thin margins.
Find out about the key risks to this BJ's Restaurants narrative.
Another View on BJ's Restaurants Valuation
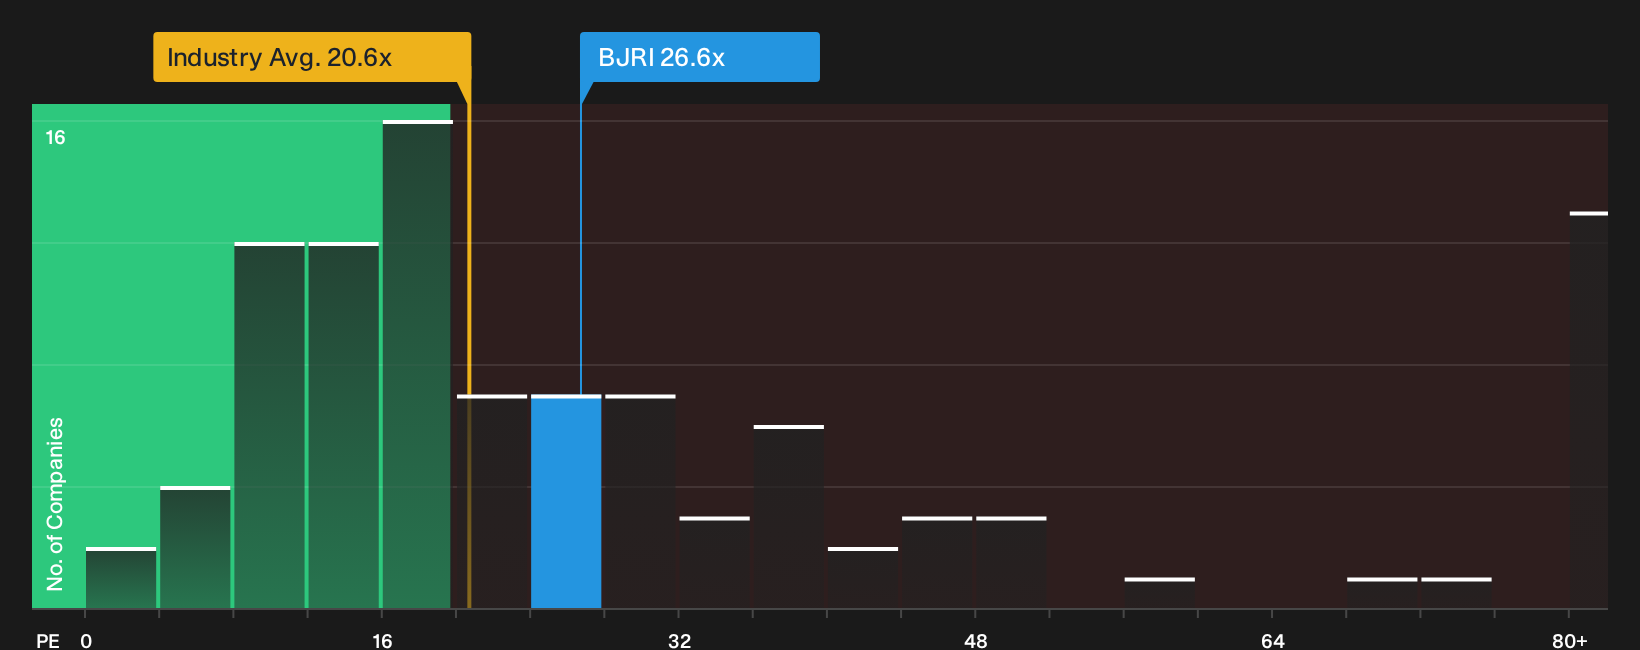
The analyst narrative leans on a fair value of $75.43, yet the simple P/E snapshot tells a different story. BJ's Restaurants trades on 26.6x earnings, above the US Hospitality average of 20.6x and above a fair ratio of 18.8x. That premium can reward conviction or punish anyone buying too late.
To pressure test that gap using earnings multiples instead of story driven forecasts, take a close look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Does the mixed mood around BJ's Restaurants leave you encouraged or cautious? Review the full picture quickly and weigh both the upside and the downside in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BJ's Restaurants?
If BJ's Restaurants has sharpened your focus, do not stop here. Use the screener to hunt for fresh opportunities before others catch on.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that surfaces sturdier businesses when conditions get tougher.
- Zero in on value by scanning the 38 high quality undervalued stocks that highlights companies trading below their estimated worth based on current fundamentals.
- Stack potential income streams by reviewing the 7 dividend fortresses that filters for higher yielding payers with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com