


EN
How Strong Earnings At Hamilton Lane (HLNE) Has Changed Its Investment Story
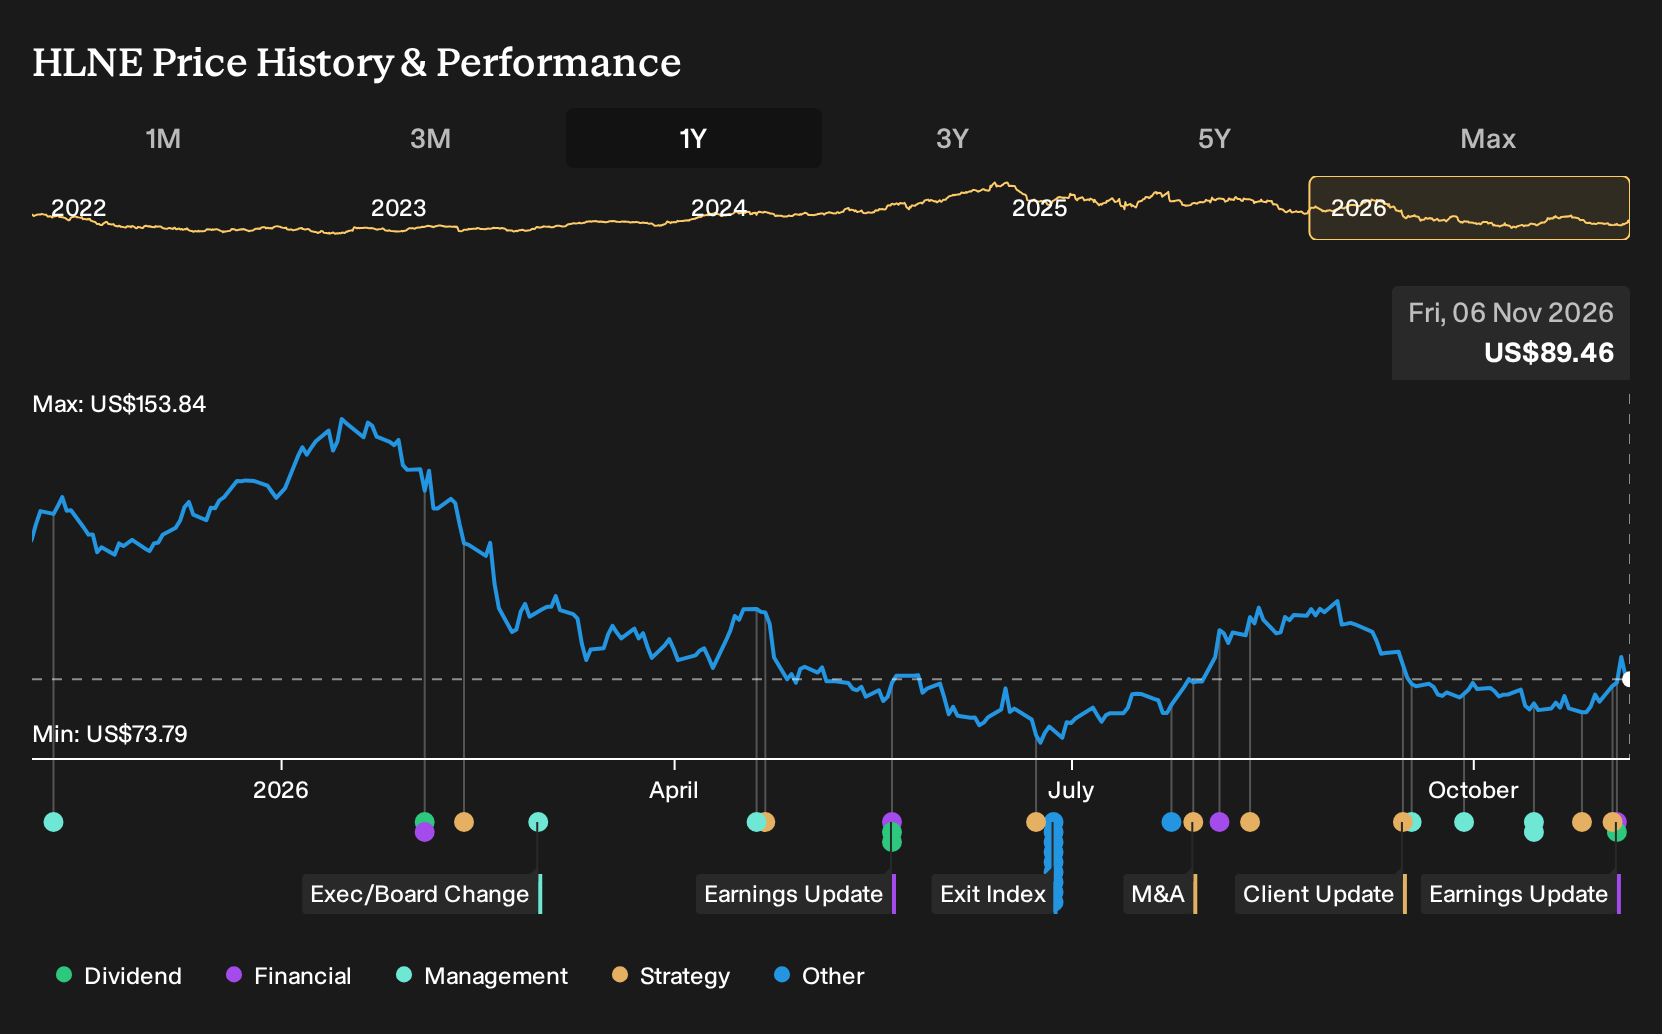
- Hamilton Lane reported past second quarter revenue of US$204.43 million and net income of US$77.49 million, alongside an affirmed quarterly dividend of US$0.60 per Class A share, with a full year dividend target of US$2.40, and a data partnership with FactSet.
- The FactSet agreement embeds Hamilton Lane’s private markets dataset directly into a major portfolio analytics platform, which could deepen relationships with institutions that want integrated public and private portfolio tools.
- We will now look at how Hamilton Lane’s investment narrative could be influenced by its higher dividend and FactSet data partnership.
Hamilton Lane Investment Narrative Recap
To own Hamilton Lane, you need to be comfortable with a specialist in private markets that leans on fee based revenue, data capabilities and long term client relationships. The latest quarter shows revenue of US$204.43 million and net income of US$77.49 million. The near term swing factor remains client appetite for private market allocations and how that translates into fee earning assets.
The biggest operational risk still sits around fee pressure and rising costs from regulation and more complex products. The recent earnings and data news do not remove that. They simply suggest the firm is leaning into scale and technology at a time when competition and pricing pressure could intensify.
The FactSet partnership is the announcement that most directly links to Hamilton Lane’s core catalysts. The arrangement puts its private markets dataset into a widely used portfolio analytics platform. That helps position the business as a data and solutions provider, not just an allocator, which can matter when investors compare fee levels across managers.
For you, the key question is whether this integration helps deepen wallet share with existing institutions and supports newer channels like wealth platforms without adding disproportionate complexity. Execution risk is real. Expanding technology enabled offerings and distribution can lift operating costs quickly if client adoption and pricing do not keep pace.
Hamilton Lane’s current analyst narrative points to forecast revenue of US$1.2b and earnings of US$478.8 million by 2029, based on an assumed 12.5% yearly revenue growth rate, with earnings rising by about US$202.9 million from US$275.9 million today.
Uncover how Hamilton Lane's fair value indicates a 38% potential upside to its current price before that discount to the market narrative closes.
Exploring Other Perspectives
One alternate view focuses on liquidity pressure from Hamilton Lane’s Evergreen funds. The most cautious analysts were already assuming roughly US$1.2b of revenue and US$486.6 million of earnings by 2029, yet assigning only a US$95.0 price target. That is a much harsher story. Treat this quarter’s data and dividend news as fresh input and explore how your own expectations compare.
Explore 7 other Hamilton Lane fair value estimates, including one that suggests it could be worth just $95.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Hamilton Lane research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hamilton Lane. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hamilton Lane's overall financial health at a glance.
Looking For More Ideas Beyond Hamilton Lane?
Once you have a view on Hamilton Lane, it can help to widen your watchlist and compare it with other businesses that fit different risk and income profiles. The Simply Wall St Screener gives you a structured way to do that across thousands of listings.
- If you want potential income with staying power, start by reviewing a set of dependable yield opportunities through 7 dividend fortresses.
- For investors who care most about resilient balance sheets and fundamentals, filter for financially robust companies using the list of solid balance sheet and fundamentals (25 results).
- If you prefer opportunities that the wider market may be overlooking, scan a focused pool of under-followed candidates via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com