


EN
3 Indian Growth Stocks With Up To 61% Earnings Growth
Rising US Treasury yields, linked to concerns about growing government debt, have pushed investors to think harder about where future returns could come from. Growth stories that are closely owned and monitored by their own founders and executives can look more appealing when broad markets feel fragile. This article highlights three Indian fast growing companies with high insider ownership from our screener that fit that profile.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the standouts, these 44 high growth high conviction stocks are the most outstanding.
Tonbo Imaging India (NSEI:TONBO)
Tonbo Imaging India develops electro optical and infrared systems for defense, surveillance, and security, including thermal weapon sights, targeting units, and missile guidance, aligning closely with fast growing defense EO/IR demand. The business has a market cap of about ₹85.2b.
Tonbo Imaging India plugs directly into the screener theme, with earnings forecast to rise 45.7% a year and revenue expected to advance 31.8% as defense focused EO/IR products gain traction. Interest is warranted, although a rich P/E near 140x and one unresolved pressure on margins and returns could influence how that growth is ultimately valued.
That premium only really makes sense if you understand what insiders see, so tap into the analysis report for Tonbo Imaging India to see what might be driving that confidence.

Bajel Projects (NSEI:BAJEL)
Bajel Projects runs EPC contracts for extra high voltage transmission lines and turnkey power transmission and distribution infrastructure, which fits the screener’s focus on scalable, high-visibility projects with strong management oversight. The business is relatively young, incorporated in 2022, and has a market cap of about ₹18.8b.
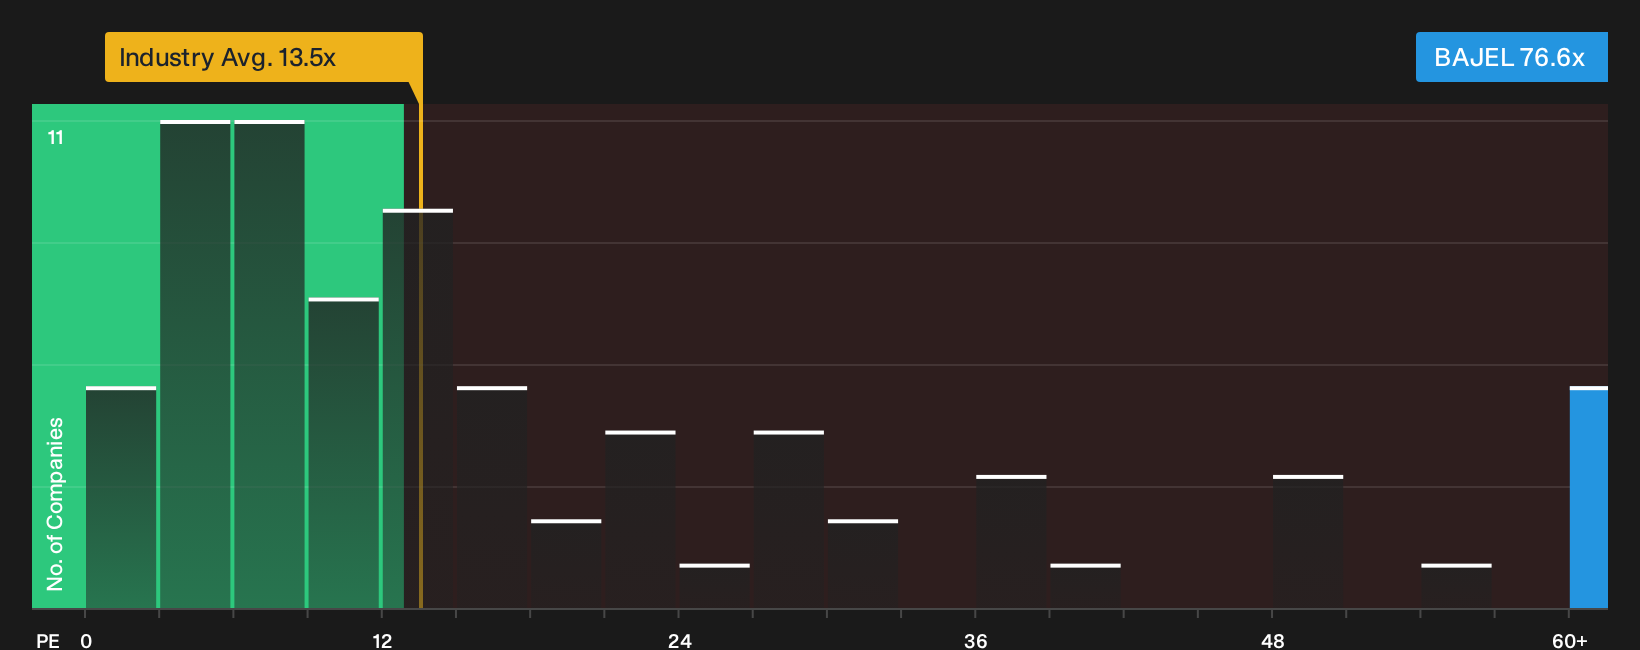
Bajel Projects is tied closely to India’s power buildout through long-tenure EPC projects, with earnings forecast to rise 60.71% per year and revenue expected to grow 30.1% per year, supported by large 765 kV and 400 kV orders. The premium 76.6x P/E depends on how the pressure around funding growth through borrowings develops.
That funding question is exactly why the Bajel Projects financial health report could be worth a few minutes, because Bajel Projects’ growth story looks very different once you map the leverage path.
Syrma SGS Technology (NSEI:SYRMA)
Syrma SGS Technology is an electronics design and manufacturing specialist focused on high growth EMS work like PCB assemblies, wire harnesses and medtech ODM solutions, generating about ₹63.1b from EMS activities and carrying a market value of roughly ₹289.9b.
Syrma SGS Technology taps directly into the screener’s fast growth theme through its EMS and medtech ODM work, where complex hardware, sticky customer relationships and higher value add services can support ambitious plans if execution holds up.
"The decision to treat inventory as a strategic asset in response to supply chain disruption, with net working capital days rising from 63 to 71 in Q1 FY27 and short term borrowings increasing by about ₹340 crore, raises the risk that any prolonged component tightness or demand slowdown could leave Syrma SGS Technology with elevated funding needs and weaker free cash flow than current expectations assume."
For investors tracking Syrma SGS Technology, a single pressure point behind those growth plans could end up deciding how resilient future returns look.
That hinge point makes it worth reading the full narrative for Syrma SGS Technology to see whether Syrma SGS Technology is quietly building strength or masking deeper balance sheet strain.

Seeking Fresh Alternatives Before They Fly
New ideas move first and price action follows. Catch potential breakout momentum while it matters, while ideas are still under the radar for now, and get in early.
- Spot cash rich operators that still look overlooked and scan the 226 high quality undervalued stocks before stronger interest arrives and entry points start dropping out of reach. Act now.
- Zero in on resilient balance sheets built to handle shocks and review the list of solid balance sheet and fundamentals (193 results) while these businesses remain quietly priced for hesitation. Move quickly.
- Ride real earnings power in AI and track the 41 profitable AI stocks that aren't just burning cash while sentiment is still catching up to their cash generation story. Get positioned early.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com