


EN
Will Stronger Power Demand Change Southern Stock's Narrative
- Southern Company reported third quarter 2026 revenue of US$8.8b and net income of US$2.0b, with earnings per share from continuing operations higher than the same period a year earlier.
- Management tied this performance to unusually strong weather adjusted sales and rising data center and industrial demand, alongside long term large load contracts and a pledge to hold base rates flat in key states.
- The focus now turns to how this stronger demand backdrop and data center driven load growth may reshape Southern Company’s investment narrative.
Southern Investment Narrative Recap
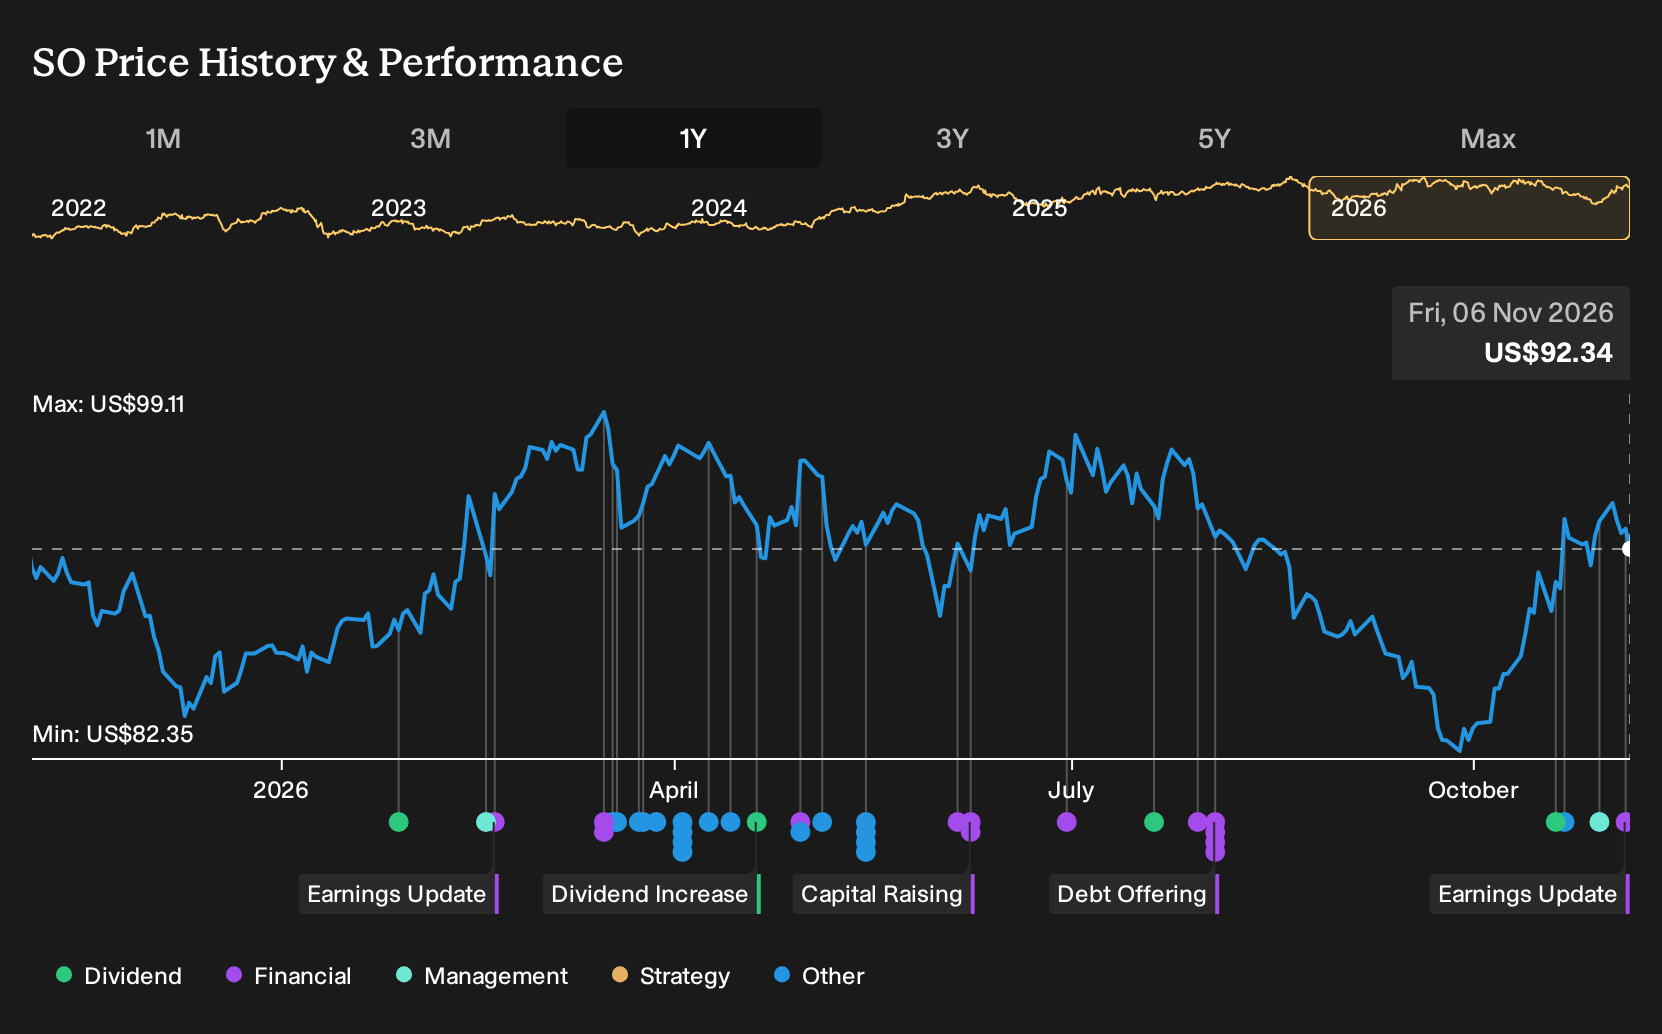
To own Southern, you need to believe that data center and industrial power demand in its territories turns into long duration contracts, regulated asset growth and stable customer bills. The latest quarter supports that story. Revenue was US$8.8b, net income was US$2.0b and EPS from continuing operations came in higher than a year earlier.
The short term catalyst is continued execution on those large load agreements while keeping base rates flat in Alabama and Georgia through at least 2029. The key risk is that the higher capital plan and funding mix, including equity linked financing and DOE backed debt, could strain earnings coverage of interest and dilute EPS over time.
The recent leadership reshuffle announced for January 2027 is closely tied to these catalysts. Kim Greene moving to president of Southern Company Operations centralizes responsibility for generation, transmission, planning, nuclear and enterprise strategy under one seat. That structure matters when the grid is being retooled to serve large data center loads and industrial projects.
Stan Connally taking over Georgia Power, along with expanded roles for technology and HR leaders, ties directly into execution risk. Georgia is at the center of many long duration contracts, including large AI data center agreements, so operational discipline, workforce skills and technology governance will influence how reliably Southern converts its capital program into regulated returns without putting undue pressure on customer bills.
Southern's narrative projects US$36.2b revenue and US$6.5b earnings by 2029. This rests on analysts assuming 6.3% yearly revenue growth and an earnings increase of roughly US$1.8b from US$4.7b today.
Discover how Southern's fair value signals a 5% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
The Simply Wall St Community offers three fair value views for Southern Company, stretching from about US$6.3 to roughly US$97 per share. That spread shows how far private investors can disagree. In light of fresh earnings headlines and a heavier capital plan, you should weigh dilution risk, the P/E premium debate and data center contract momentum, then compare multiple viewpoints directly.
Explore 2 other Southern fair value estimates, including one that suggests as much as 93% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Southern research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Southern. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southern's overall financial health at a glance.
Looking for more investment ideas beyond Southern?
If the Southern story has you thinking about where regulated infrastructure, cash flow resilience and different risk profiles might meet your own goals, the Simply Wall St Screener is a useful next stop. You can filter for fundamentals that matter to you, then let the data surface candidates that fit your preferred mix of quality, income and balance sheet strength.
- For investors who care most about valuation and underlying business quality, check out a curated 38 high quality undervalued stocks that may warrant a closer look.
- If capital preservation sits high on your list, scan a focused 31 resilient stocks with low risk scores that aim to pair steadier fundamentals with tighter risk scores.
- When you want sturdier finances as the foundation of any thesis, start with a list of solid balance sheet and fundamentals (25 results) that already filters for healthier leverage and liquidity profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com