


EN
Why Labcorp Holdings (LH) Is Back In The Spotlight
Labcorp earnings and guidance shift draw investor focus
Labcorp Holdings (LH) put fresh numbers on the table with third quarter 2026 results and a higher full year revenue growth outlook, giving investors new data to weigh the stock’s recent move.
Recent trading has backed up that guidance shift, with a 30 day share price return of 17.43% and a year to date gain of 45.66%, while total shareholder return of 46.52% over one year and 84.73% across three years indicates momentum that investors are still willing to pay attention to.
Scan how the market is rewarding earnings upgrades like Labcorp Holdings with a curated set of potential breakout candidates in the 38 high quality undervalued stocks list.
Bulls point to Labcorp Holdings raising guidance and steady earnings, while bears flag an 84.73% three year return and higher expectations. Which side does the current valuation actually support?
Most Popular Narrative: 3% Overvalued
Labcorp Holdings last closed at $366.57, slightly above the most followed fair value estimate of $354.50. This frames the current debate around how much of its specialty testing and biopharma pipeline is already priced in.
Labcorp Holdings continues to expand higher value specialty testing in oncology, neurology, autoimmune disease and women’s health, with this franchise now around US$2b in diagnostics revenue and a rising share of esoteric and specialty work, which supports higher revenue per patient encounter and contribution to earnings.
See why 7 investors see Labcorp Holdings as 3% overvalued.
Result: Fair Value of $354.50 (OVERVALUED)
Still, the narrative around Labcorp Holdings can crack if PAMA cuts hit that US$100m earnings line, or if recent revenue and margin trends stall again.
Find out about the key risks to this Labcorp Holdings narrative.
Another view on Labcorp Holdings valuation
The first take pegs Labcorp Holdings as about 3% overvalued at $366.57 against a $354.50 fair value. A different lens tells a very different story. The SWS DCF model estimates future cash flows at $979.07 per share, which screens as heavily undervalued versus the current price. Which signal should carry more weight for you?
The SWS DCF model leans entirely on long term cash generation rather than near term earnings multiples, so it can point to opportunity where shorter term sentiment sees limited upside. That kind of gap invites a harder look at the inputs behind each approach, and which set of assumptions you trust most for Labcorp Holdings over the next few years. Look into how the SWS DCF model arrives at its fair value.
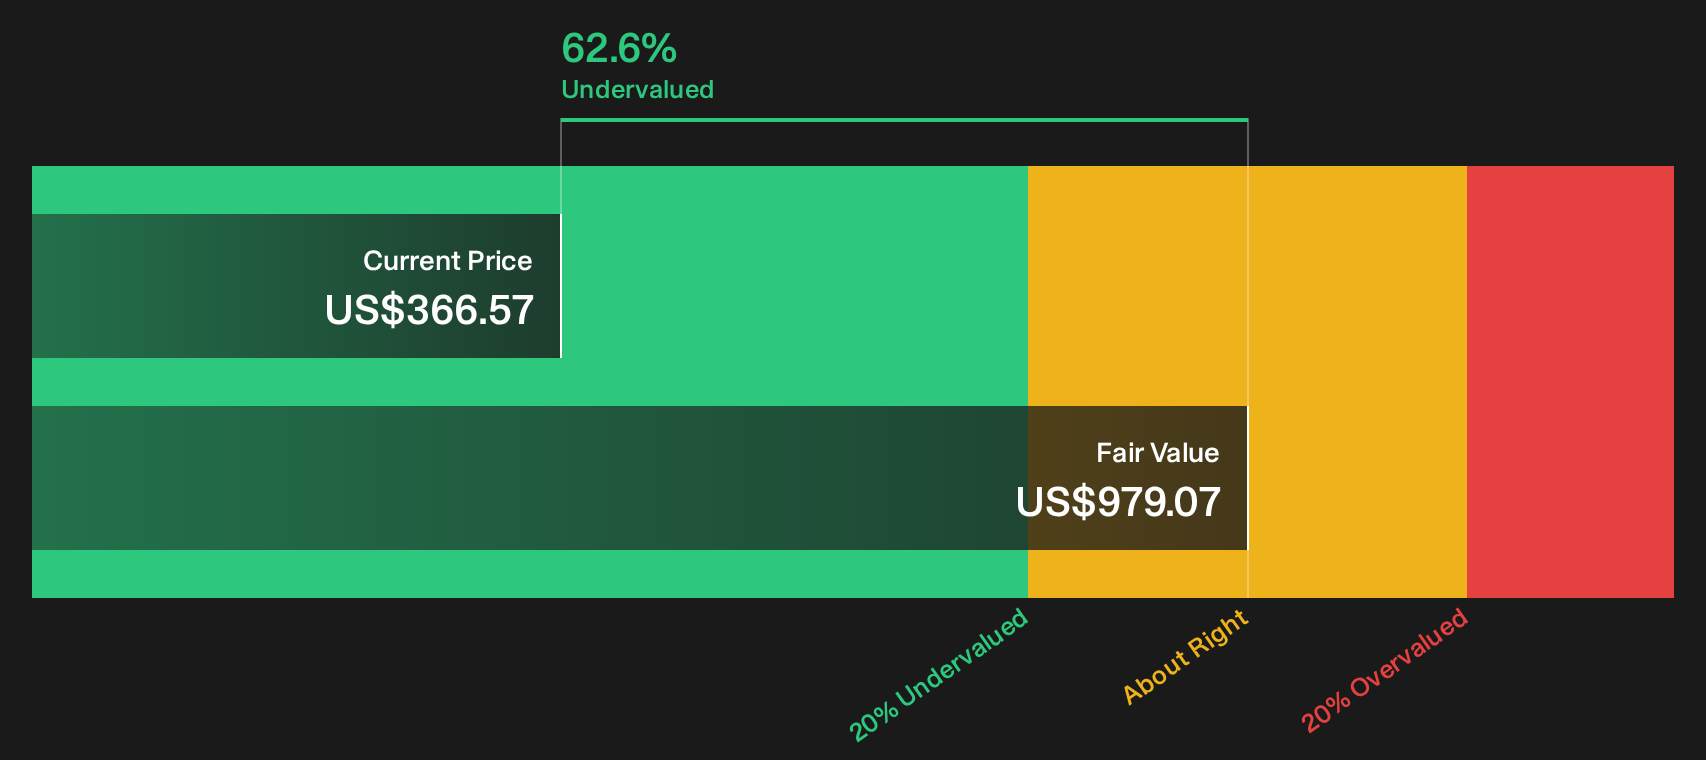
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Labcorp Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Labcorp Holdings valuation can feel messy, so move quickly on the data and pressure test the upside and downside for yourself with 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Labcorp Holdings?
If Labcorp Holdings has you thinking harder about valuation and momentum, do not stop here. Fresh ideas often come from looking just one layer wider.
- Spot potential high quality turnarounds early by scanning the 19 high quality undiscovered gems that the market may not be watching yet.
- Prioritise resilience in tougher conditions by checking companies in the 31 resilient stocks with low risk scores that score well on stability and risk controls.
- Anchor your portfolio with stronger finances by reviewing the list of solid balance sheet and fundamentals (25 results) before capital chases the next headline mover.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com