


EN
3 British Growth Stocks With Earnings Growth Up To 71%
Rising UK interest rate expectations after a strong US jobs report have pushed investors to rethink where growth might come from next. When money is no longer cheap, fast growing British businesses where executives own a lot of the shares can look especially interesting. This article highlights three stocks from that high growth, high insider ownership group so you can see which kinds of stories fit this backdrop.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where leaders have significant skin in the game. However, if you want the standouts, these 6 high growth high conviction stocks are the most outstanding.
International Workplace Group (LSE:IWG)
Overview: International Workplace Group runs global flexible workspaces and coworking brands, offering recurring memberships, virtual offices, and managed-office services aligned with hybrid work.
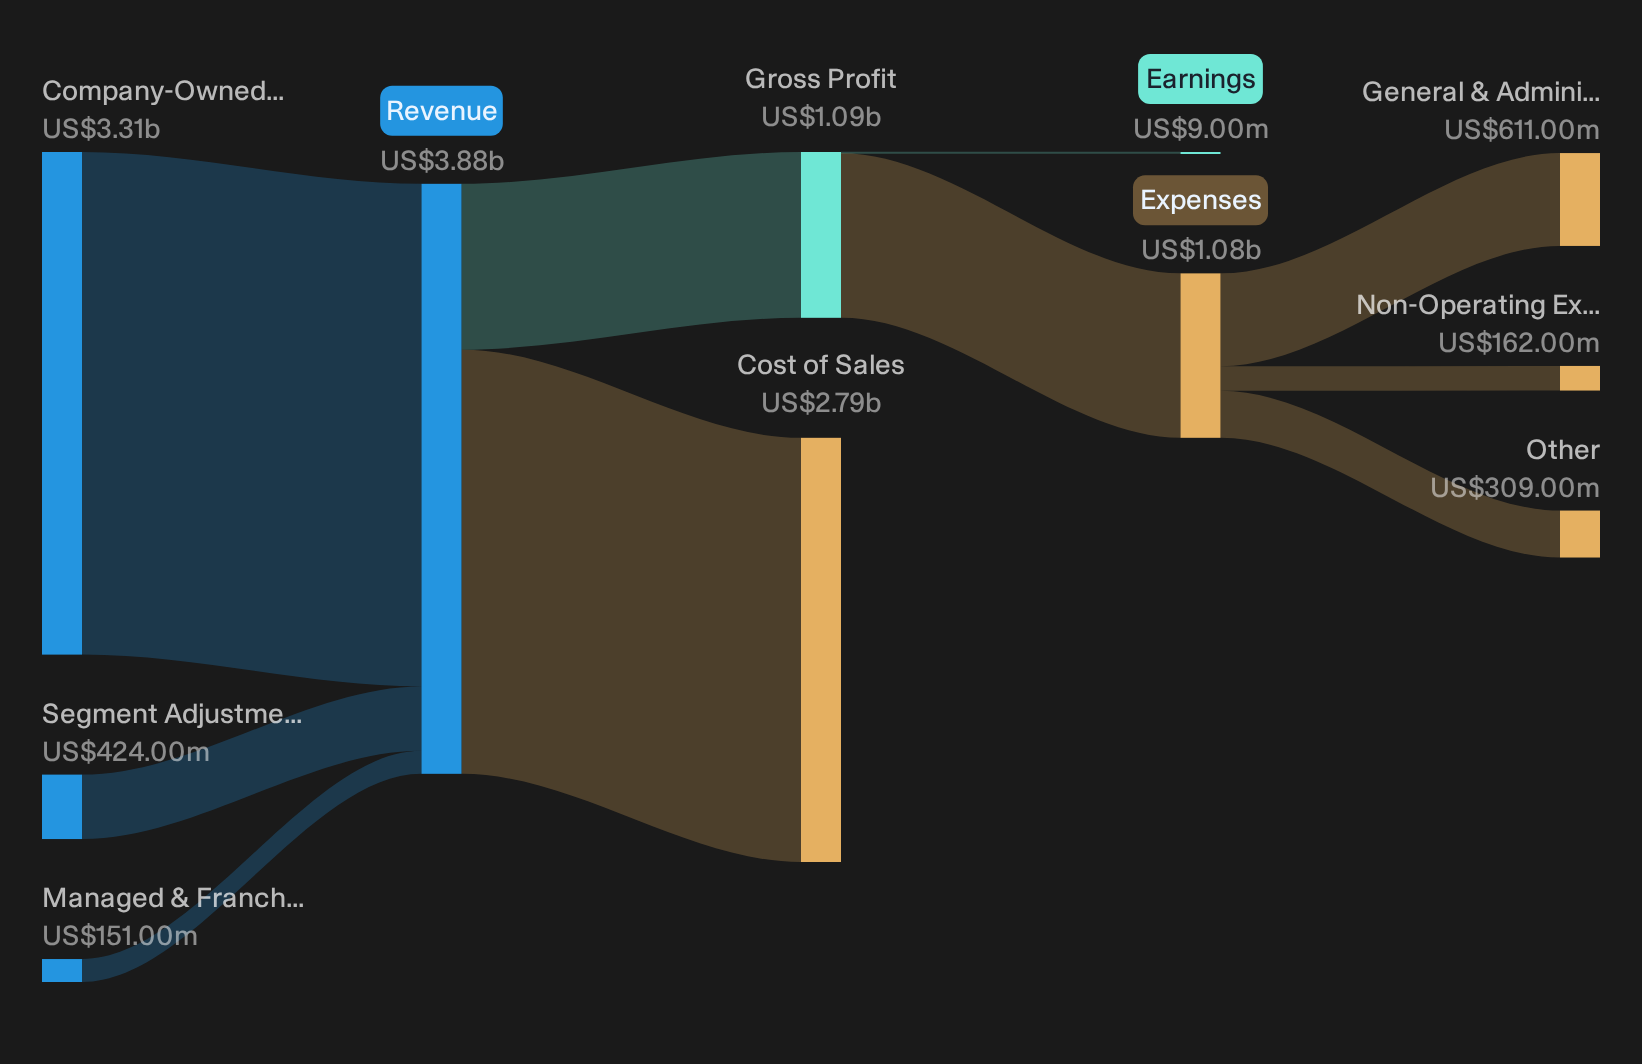
Operations: International Workplace Group generates most income from company-owned centers with about US$3.3b revenue, plus US$151 million from managed and franchised arrangements.
Market Cap: £2.0b
International Workplace Group fits this screener because its flexible workspace network is tightly linked to recurring demand for hybrid work solutions, yet the way earnings respond to that demand depends heavily on how its different revenue models behave through the cycle.
"Although International Workplace Group reports broad corporate interest in shifting real estate from fixed to flexible models, management concedes that quarter on quarter movements in company-owned revenue still flow almost 1:1 into EBITDA before costs."
What happens if a single assumption about how quickly higher fee-based arrangements ramp up proves too optimistic for future margins?
If that margin sensitivity worries you, read the full narrative for International Workplace Group to see how insider ownership, capital intensity and fees could be decoupling beneath the surface.
Playtech (LSE:PTEC)
Overview: Playtech runs a global gambling software and content platform, with casino, live casino and sports betting products driving scalable recurring licensing revenue.
Operations: Playtech generates about €735.5 million from B2B activities and €64.8 million from Sun Bingo and other B2C operations, with smaller HAPPYBET and intercompany adjustments.
Market Cap: £1.0b
Playtech fits this fast growing, high insider ownership theme because its online gaming platforms turn product investment into repeat fees when operators scale.
"The move to a predominantly regulated footprint, with more than 85% of Playtech income already from regulated markets and management aiming to focus new investment on regulated and regulating jurisdictions. This positions future B2B revenue and earnings to be driven more by markets with clearer rule books and potentially more stable net margins."
The real tension is what happens to Playtech’s earnings trajectory if a single assumption about how quickly regulated B2B margins settle proves too optimistic.
That risk cut both ways, so read the full narrative for Playtech to see how Playtech’s regulated focus could turn volatility into accelerating B2B momentum.

Softcat (LSE:SCT)
Overview: Softcat provides value added IT reselling and high growth digital infrastructure services, helping UK enterprises and public bodies adopt cloud, security and AI.
Operations: Softcat generates about £2.0b from value added IT resale and infrastructure solutions, almost entirely from customers in the United Kingdom.
Market Cap: £3.4b
Softcat matters for this high growth, high insider ownership screen because its advisory led cloud, security and AI projects sit on top of a broad resale base. This gives management room to tilt the mix toward higher value services.
"Expansion into the US through the planned GDT acquisition, with GDT forecast to contribute about US$240m gross profit and US$80m adjusted EBITDA in calendar 2026, could broaden Softcat’s revenue base and support earnings growth as the combined group gains more exposure to multinational customers."
What could really reshape the Softcat story is how one shift in gross margin mix interacts with that bigger, more complex customer book.
That margin mix question is exactly why you should read the full narrative for Softcat to see how Softcat’s US push could accelerate or mask the next phase of earnings power.

Seeking Alternatives Before The Crowd Moves
Fresh opportunities do not stay quiet for long. Breakout stories gain momentum, laggards get caught, and prices start flying once attention arrives. Review these under the radar ideas now and consider them before they become widely followed.
- Look for strong balance sheets before the rush and review the curated list of solid balance sheet and fundamentals (9 results) that filters out weaker fundamentals while it still matters.
- Focus on resilient income as rates shift and scan the hand picked 4 dividend fortresses that aims to highlight consistent payouts even when prices are dropping.
- Monitor the infrastructure theme early and track the focused 41 power grid technology and infrastructure stocks that highlights businesses connected to grid upgrades while they remain less widely noticed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com