


EN
What Edwards Lifesciences Stock Beat And Raised Outlook Means For Shareholders
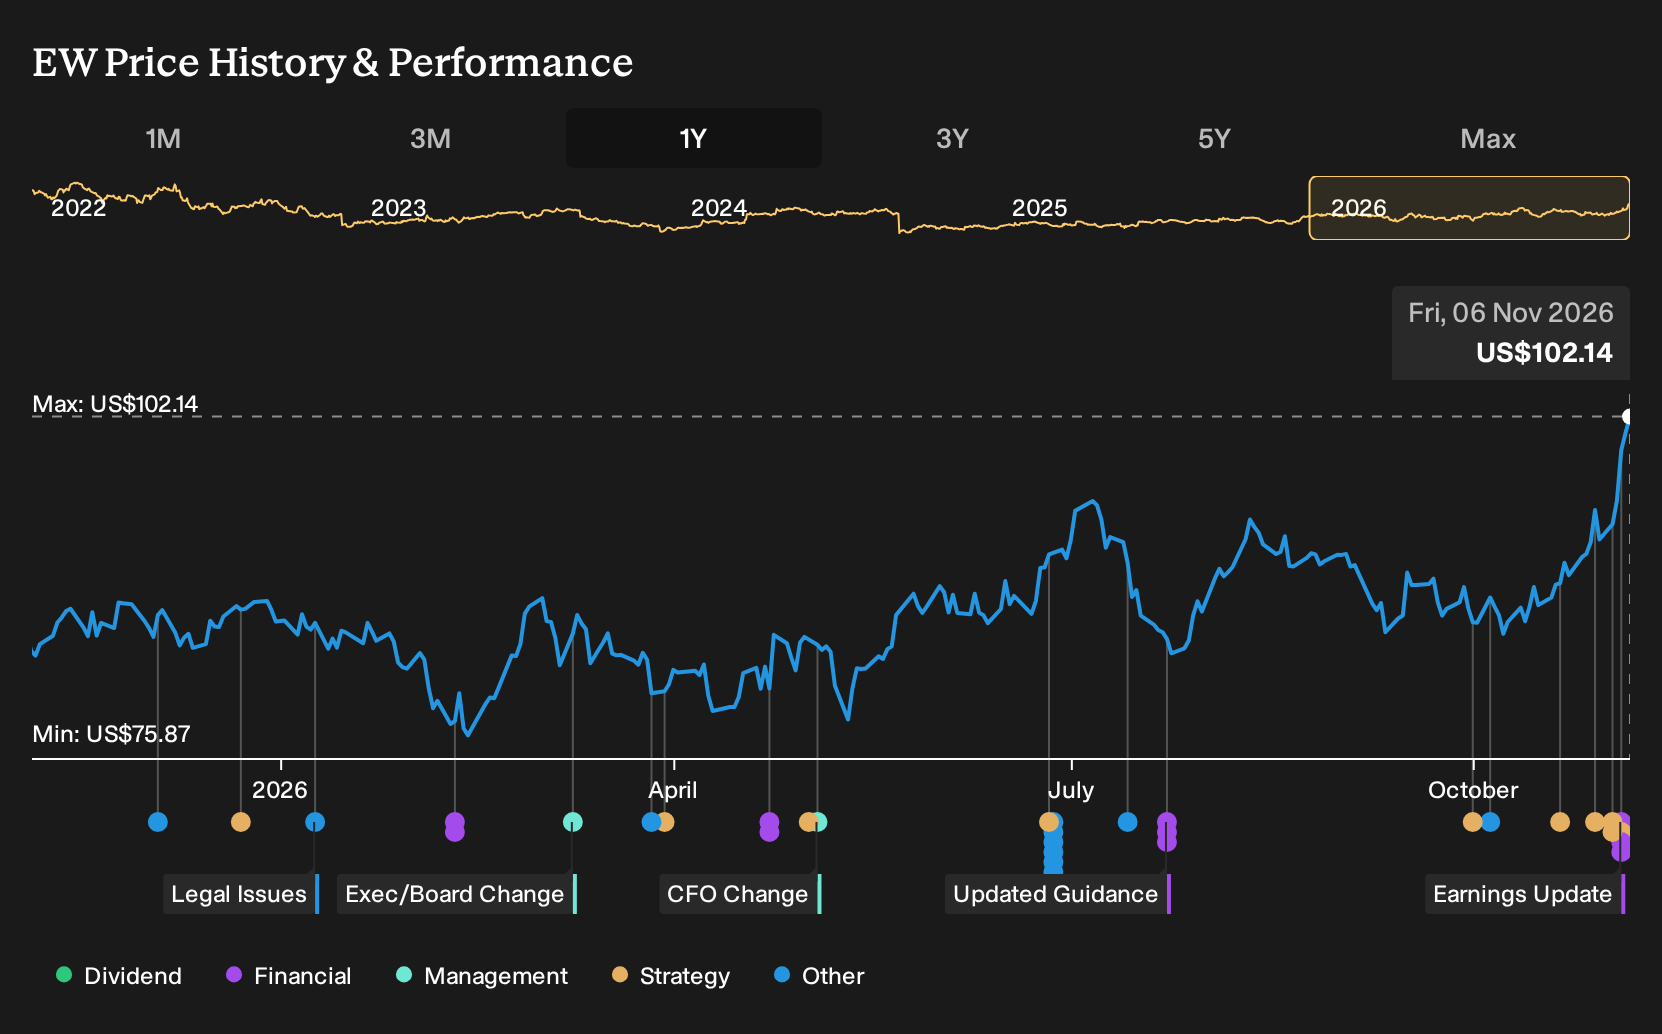
- Edwards Lifesciences reported third quarter 2026 sales of US$1,715.5 million and net income of US$307.5 million, and raised full year guidance for total sales growth and key transcatheter product groups.
- Fresh PROGRESS and CLASP II TR trial data, together with recent TAVR coverage and approval milestones, highlight how Edwards Lifesciences is tying clinical outcomes directly to procedure volume potential across its structural heart portfolio.
- We will now see how Edwards Lifesciences' investment narrative could be influenced by raised 2026 guidance supported by stronger procedure trends.
Scan how Edwards Lifesciences' latest procedure-driven guidance compares with other potential heart health beneficiaries by reviewing the hand-picked 35 healthcare AI stocks in this space.
Edwards Lifesciences Investment Narrative Recap
To own Edwards Lifesciences, you need to be comfortable with a procedure-driven story where TAVR and transcatheter mitral and tricuspid therapies anchor growth and operating leverage. The raised 2026 sales and product group guidance supports that view, although the nine-month earnings profile and recent impairment charges keep the quality of reported profit a live question.
In the near term, the key catalyst is sustaining higher valve procedure volumes as more centers ramp under expanded Medicare coverage. The biggest risk is pressure on margins from tariffs, legal and compliance costs around blocked M&A, and large one-off items that have already weighed on profitability and could recur.
The PROGRESS trial update looks most relevant to the latest guidance. Edwards Lifesciences reported that TAVR was superior to clinical surveillance in moderate aortic stenosis patients with at-risk features on a composite of death or heart failure events at two years, and patients had a meaningful quality-of-life improvement at 30 days.
That kind of randomized data, alongside expanded Medicare coverage and the raised TAVR growth outlook to 9% to 9.5%, highlights procedure volume as the main operational swing factor. The opportunity is that more moderate aortic stenosis patients ultimately receive TAVR, while the risk is that uptake, reimbursement decisions, or competing therapies limit how fully those trial results translate into real-world volumes.
Edwards Lifesciences' current analyst narrative assumes revenue reaches US$8.7b and earnings of US$2.3b by 2029, based on forecast annual top line growth of 9.2% and an earnings increase of about US$1.3b from US$994.3m today.
Discover why Edwards Lifesciences' fair value is essentially aligned with its current price.
Exploring Other Perspectives
The Simply Wall St Community offers only two fair value views on Edwards Lifesciences so far, clustered in a tight US$104.27 to US$108.31 band. That small sample sits against meaningful questions around impairment charges, tariff exposure, and the blocked JenaValve deal, which could all shift how you judge future earnings resilience.
Explore another Edwards Lifesciences fair value estimate, including one that suggests it could be worth just $104.27.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Edwards Lifesciences research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Edwards Lifesciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edwards Lifesciences' overall financial health at a glance.
Looking for more investment ideas beyond Edwards Lifesciences?
Once you have formed a view on Edwards Lifesciences, it can help to widen the lens and compare it with other opportunities that share similar qualities or offer different risk and reward profiles.
- If you care most about quality at a sensible price, scan a curated 38 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into their share prices.
- If capital protection ranks higher for you than aggressive upside, review a 31 resilient stocks with low risk scores that screen for resilient balance sheets and steadier risk scores.
- If you are hunting for under-followed ideas, browse a 19 high quality undiscovered gems that highlight financially solid businesses that may not yet be widely on the market's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com