


EN
Recursion Pharmaceuticals (RXRX) After Phase 2 Data What The REC 4881 Narrative Means For Valuation
Recursion Pharmaceuticals (RXRX) just put fresh Phase 2 data for its REC-4881 program in front of investors, highlighting sizable polyp burden reductions in familial adenomatous polyposis patients and a clean safety profile that supports a planned registrational trial.
The fresh REC-4881 data lands after a volatile stretch for Recursion Pharmaceuticals, with the share price down 19.3% over the past month and 16.2% year to date, yet still up 7% on a 90 day view as traders weigh earlier earnings and the recent board change alongside this new clinical readout.
Scan how Recursion Pharmaceuticals stacks up against other biotech stories with fresh catalysts by reviewing a curated list of 35 healthcare AI stocks.
Recursion Pharmaceuticals is trading well below its recent range after the REC-4881 update and board shake up. Is most of the value of this pipeline already reflected in the US$3.52 quote, or is meaningful upside still ahead?
Most Popular Narrative: 52% Undervalued
At a last close of $3.52 versus a narrative fair value of $7.32, Recursion Pharmaceuticals is framed as materially discounted, with the thesis hinging on how well the platform, pipeline and partnerships convert into future cash flows under a 7.49% discount rate.
The key thing that has to go right is that Recursion Pharmaceuticals turns its AI-driven platform and growing pipeline, including partnered programs with Roche, Genentech, and Sanofi, into commercially meaningful assets while keeping operating expenses in line with guidance.
The current valuation implies the market is still discounting the potential of Recursion Pharmaceuticals’ AI-enabled pipeline and partnership economics despite clinical progress, sizeable milestone structures, and a cash runway that management projects into early 2028.
See why 143 investors see Recursion Pharmaceuticals as 52% undervalued.
Result: Fair Value of $7.32 (UNDERVALUED)
Still, the Recursion Pharmaceuticals story can change quickly if the timing of milestone revenue remains choppy or if further equity raises dilute existing holders again.
Find out about the key risks to this Recursion Pharmaceuticals narrative.
Another View on Recursion Pharmaceuticals Valuation
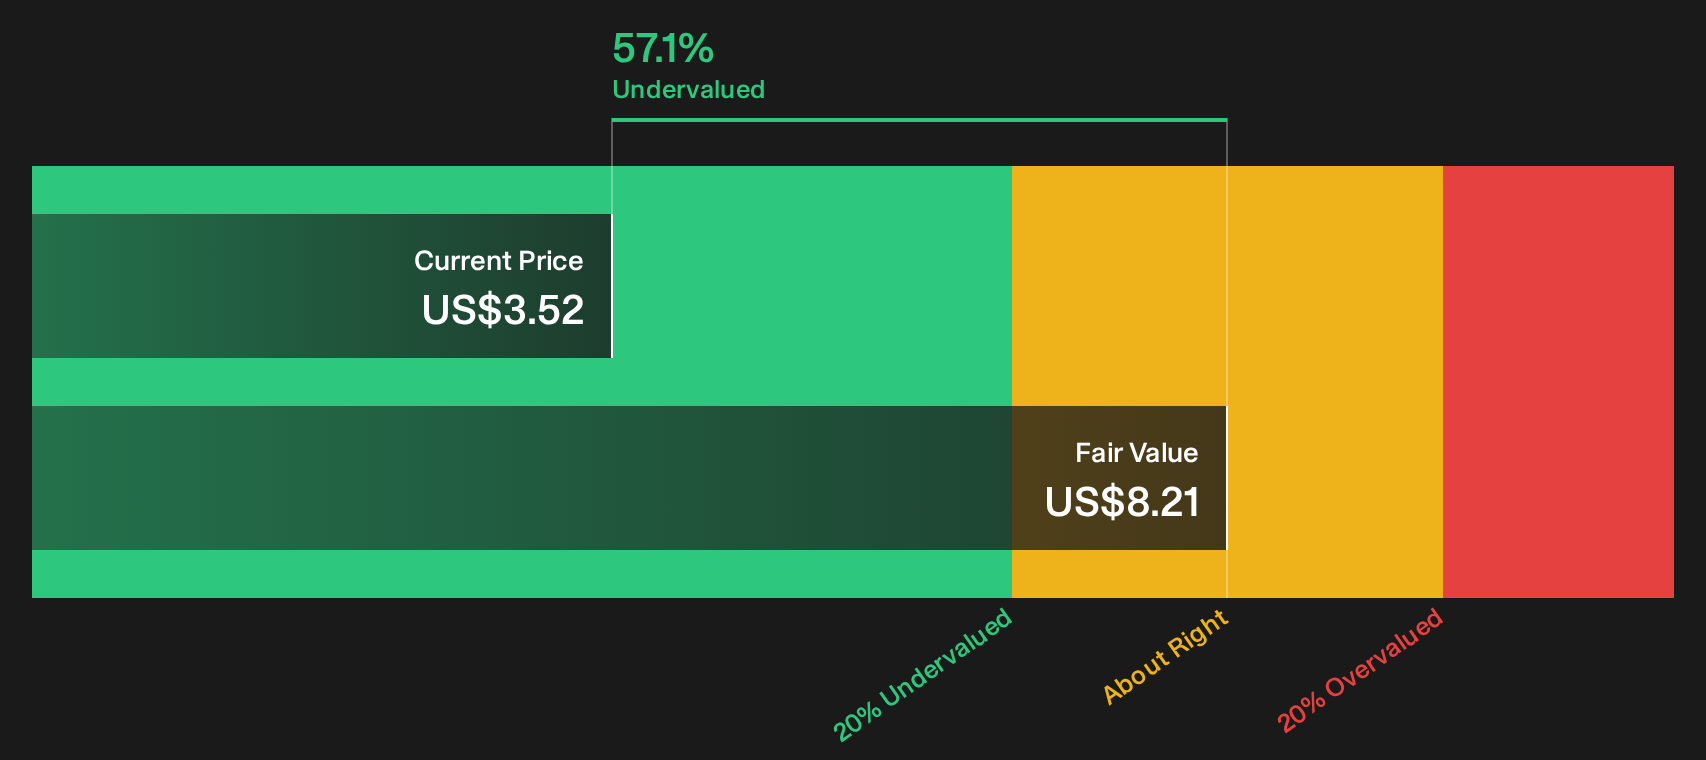
The SWS DCF model points in the opposite direction to the rich P/S multiples. RXRX is trading at $3.52, which is 57.1% below the modelled future cash flow value of $8.21, so the framework identifies the stock as undervalued. Which signal should investors prioritize when the cash flows are still years away?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Plenty of optimism and concern sit side by side in the Recursion Pharmaceuticals story right now. Consider moving quickly, review the numbers for yourself, and weigh both the upside and the risks by checking the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Recursion Pharmaceuticals?
Do not stop your research with Recursion Pharmaceuticals. Broaden your watchlist with fresh ideas sourced from structured screeners that focus on quality, resilience, and income potential.
- Target potential upside by scanning a curated set of high quality opportunities through the 19 high quality undiscovered gems.
- Strengthen portfolio resilience by focusing on companies with dependable finances using the list of solid balance sheet and fundamentals (25 results).
- Build a reliable income stream by reviewing businesses offering robust payout profiles via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com