


EN
3 Great Dividend Stocks To Own In November 2026
Social Security faces projected benefit cuts from 2032, so reliable income streams are suddenly front of mind for many future retirees. Well covered dividends above 3% can help plug that potential gap, especially when those payouts look stable and have a history of rising. This article highlights three high yielding companies from a curated dividend list that could help anchor a long term, income focused portfolio.
The three stocks highlighted here offer a compelling starting point if you want exposure to well covered, growing dividend payers with yields above 3%. However, if you want the names that matter most, these 7 dividend aristocrats stocks are the strongest companies we've found.
Chevron (CVX)
Chevron anchors this Dividend Powerhouses list because its integrated oil and gas operations generate the kind of cash flow that can underpin a sizeable, recurring payout, giving income focused investors a direct link between real world energy assets and steady portfolio income.
Chevron runs a global integrated energy and chemicals business with large Upstream oil and gas activities in the United States and internationally generating about US$55.7b and US$60.6b of revenue, alongside sizeable Downstream refining and marketing operations producing roughly US$91.2b in the US and US$85.4b abroad, supporting its dividend profile at a scale consistent with a US$414.9b company.
"Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow."
What happens if one key cost pressure quietly shifts against that free cash flow story will be crucial for long term dividend comfort.
That cost pressure is exactly what the full narrative for Chevron unpacks, revealing how Chevron's capital choices, payout priorities, and energy mix could keep income potential accelerating or quietly stall it.

DICK'S Sporting Goods (DKS)
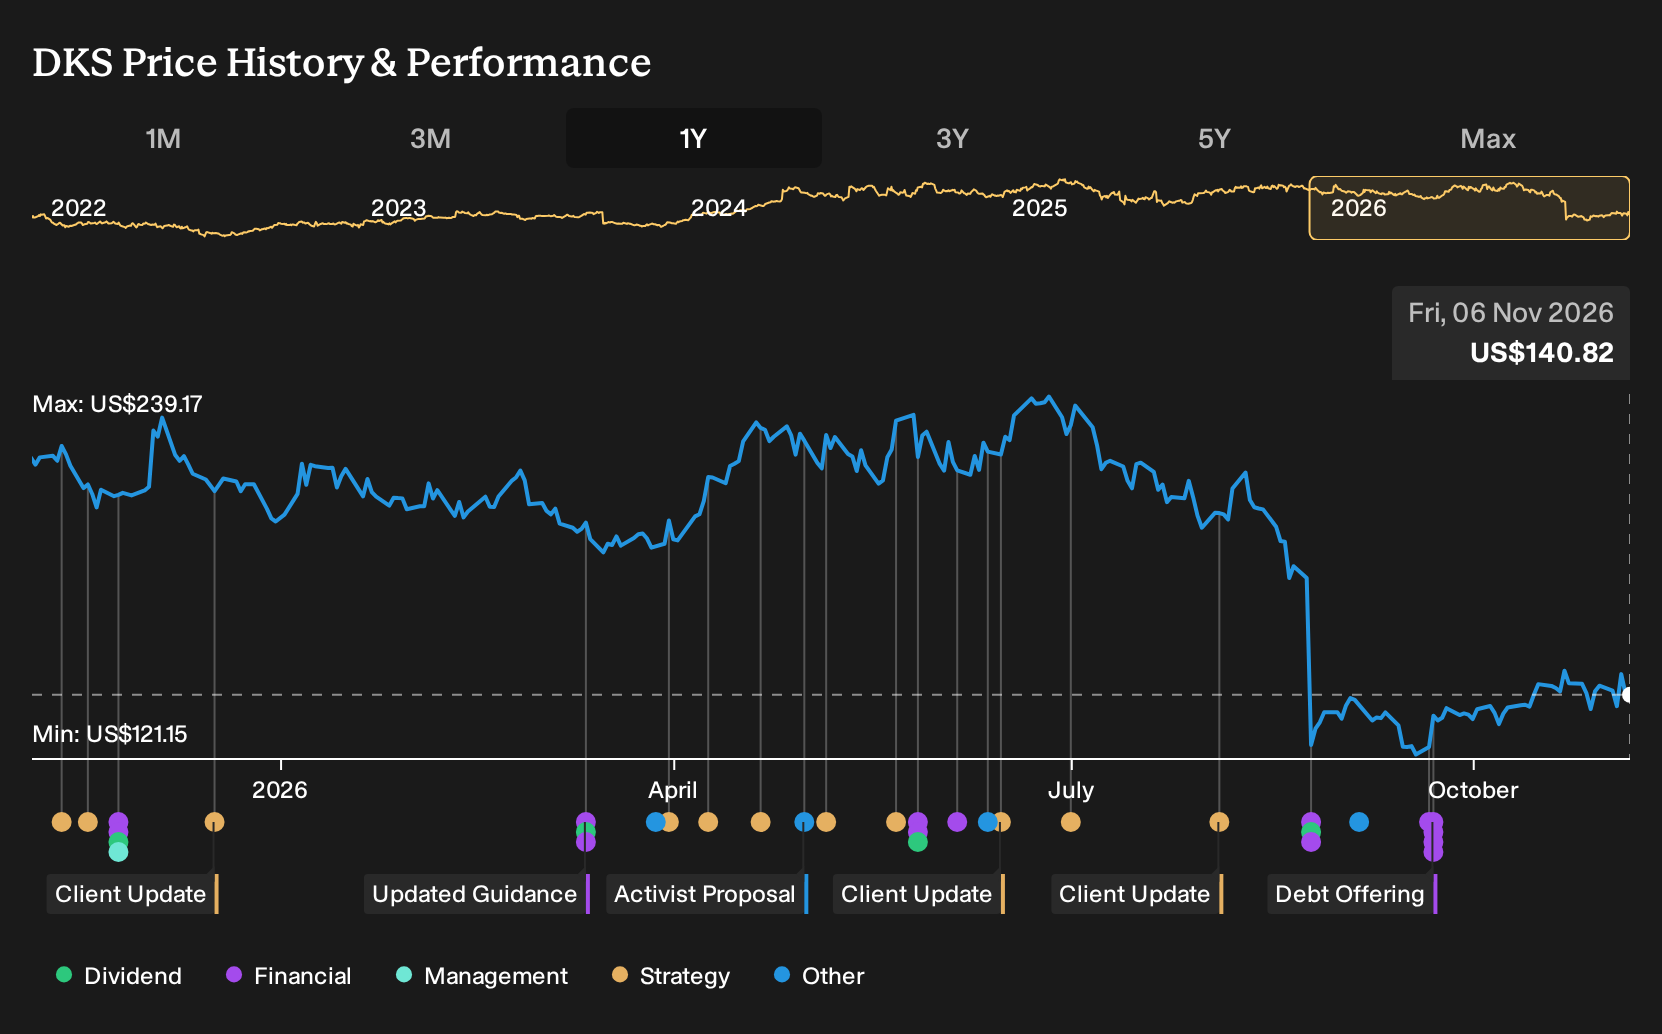
DICK'S Sporting Goods leans on its cash generating sporting goods, footwear, and apparel stores to fund a 3%+ dividend, with omni channel retail at the core while digital services and apps play a supporting role in that income story.
DICK'S Sporting Goods runs large U.S. sporting goods chains and related banners that generated about US$14.5b from DICK’S branded operations, against segment adjustments of roughly US$6.6b, and the overall business carries a market value near US$12.5b.
"The Foot Locker "inflection point" has been deferred. May's call used that phrase with some precision, describing the first back-to-school season where the team had "full control over the buys" as the structural turning point."
For dividend focused investors, what happens if a single unseen pressure on this retail model quietly drags on cash generation will matter a lot.
That hidden drag on cash is exactly what the full narrative for DICK'S Sporting Goods unpacks, showing where DICK'S Sporting Goods could be quietly accelerating beyond the Foot Locker comparison.
Bank OZK (OZK)
Bank OZK is a full service Arkansas bank that leans on interest income from loans and fee based treasury and wealth services to fund steady dividends, with a market value around US$5.5b that reflects its role as a traditional income focused lender.
For income investors, Bank OZK brings an old fashioned banking model into a screen built around dependable cash payouts, using everyday loans, deposits, and fees to support a higher yield rather than more fragile trading activity.
"The accelerated buildout of the Corporate and Institutional Banking platform, which now spans more than seven lending verticals and over 42 industry niches and is expected to reach a portfolio size similar to RESG by 2027, is set to increase floating rate lending spreads and fee income from roles as administrative agent or joint lead on single lender and small club deals."
The quiet swing factor is how one pressure on future loan profitability plays out, which could reshape both dividend headroom and valuation upside.
That profitability question is exactly where the full narrative for Bank OZK picks up, mapping how Bank OZK's lending engine could turn that pressure into accelerating income potential for long term holders.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not stay under the radar for long. Some ideas are already building quiet breakout momentum. Scan these curated lists before the crowd catches up and act now.
- Spot potential turnaround stories early by reviewing 19 high quality undiscovered gems that pair solid fundamentals with underfollowed stories still flying under most investors' screens.
- Target resilient cash generators by checking the list of solid balance sheet and fundamentals (25 results) curated to highlight businesses where financial strength supports staying power when markets turn choppy.
- Ride long term infrastructure themes by tracking 41 power grid technology and infrastructure stocks built around companies investing in critical grid upgrades while many investors remain focused elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com