


EN
How Investors May Respond To EOG Resources (EOG) Record Production And Dividend Raise
- EOG Resources reported third quarter 2026 revenue of US$8.549b and net income of US$2.781b, alongside record oil, NGL, and gas output and an 8% increase in its regular dividend to US$1.10 per share.
- The combination of record production, higher earnings per share, a larger regular dividend, and the planned Janus gas plant expansion indicates that EOG Resources is focusing on both current cash generation and LNG linked gas marketing opportunities.
- We will look at how EOG Resources' investment narrative is affected by record production and the 8% dividend increase announced for 2027.
Scan how EOG Resources' record output and higher regular dividend stack up against other cash generative producers by reviewing our curated 7 dividend fortresses in one place.
EOG Resources Investment Narrative Recap
To own EOG Resources, you need to believe the business can keep turning its multi basin portfolio and technology gains into profitable barrels and gas volumes while managing commodity swings and energy transition pressure. The latest quarter shows that record production and higher earnings per share are aligned with that story rather than changing it.
The key near term swing factor is execution on high return projects and LNG linked gas marketing, including keeping production around current guidance ranges without cost creep. The biggest risk is that gas focused and international projects underperform, which could expose EOG Resources more to weaker prices and renewables driven demand pressure.
The regular dividend increase to US$1.10 a share, or US$4.40 a year, is the announcement that ties most directly into this earnings release. It channels current cash generation into recurring payouts rather than only buybacks, which matters if you care about more predictable cash returns.
This higher base dividend also raises the bar for future cycles. EOG Resources now needs its Janus gas plant expansion, LNG linked offtake and lower drilling costs in areas like the Utica to keep supporting free cash flow. Any slip in execution or prolonged commodity weakness would make that higher payout ratio harder to sustain.
EOG Resources Analyst Assumptions and Valuation Setup
Analysts looking at EOG Resources effectively assume a steady top line over the next few years, with most of the change coming from margin work rather than rapid expansion in sales. Profitability today is framed around a 25.7% margin, while consensus points to 27.0% in three years, so the story hinges on squeezing more earnings out of roughly similar revenue rather than chasing sheer volume.
On the earnings side, the group forecast is for profit of US$7.2b by 2029, compared with US$6.9b in earnings today. That is a US$0.3b uplift, which is not huge in absolute terms but matters when you remember analysts are not baking in big revenue swings. The spread between the most optimistic and most cautious estimates, from US$8.6b down to US$5.4b, shows how much disagreement there is about how efficiently the portfolio can be run by the end of the decade.
Those profit expectations sit inside a specific valuation frame. To line up with the consensus targets, investors would need to be comfortable with EOG Resources trading on a P/E of 13.4x those 2029 earnings, compared with 12.0x today and 12.5x for the broader US oil and gas peer group. That implies a modest uplift in the earnings multiple alongside the projected margin improvement, rather than the entire case resting on volume growth.
The forecast also assumes a shrinking share count, with analysts expecting outstanding shares to decline by about 3.33% a year over the next three years. If that happens, even flat or gently rising earnings could translate into a more noticeable move in earnings per share, since profits would be spread over fewer shares. For income and buyback focused investors, the interaction between that falling share base and the higher regular dividend is a key part of the EOG Resources equity story.
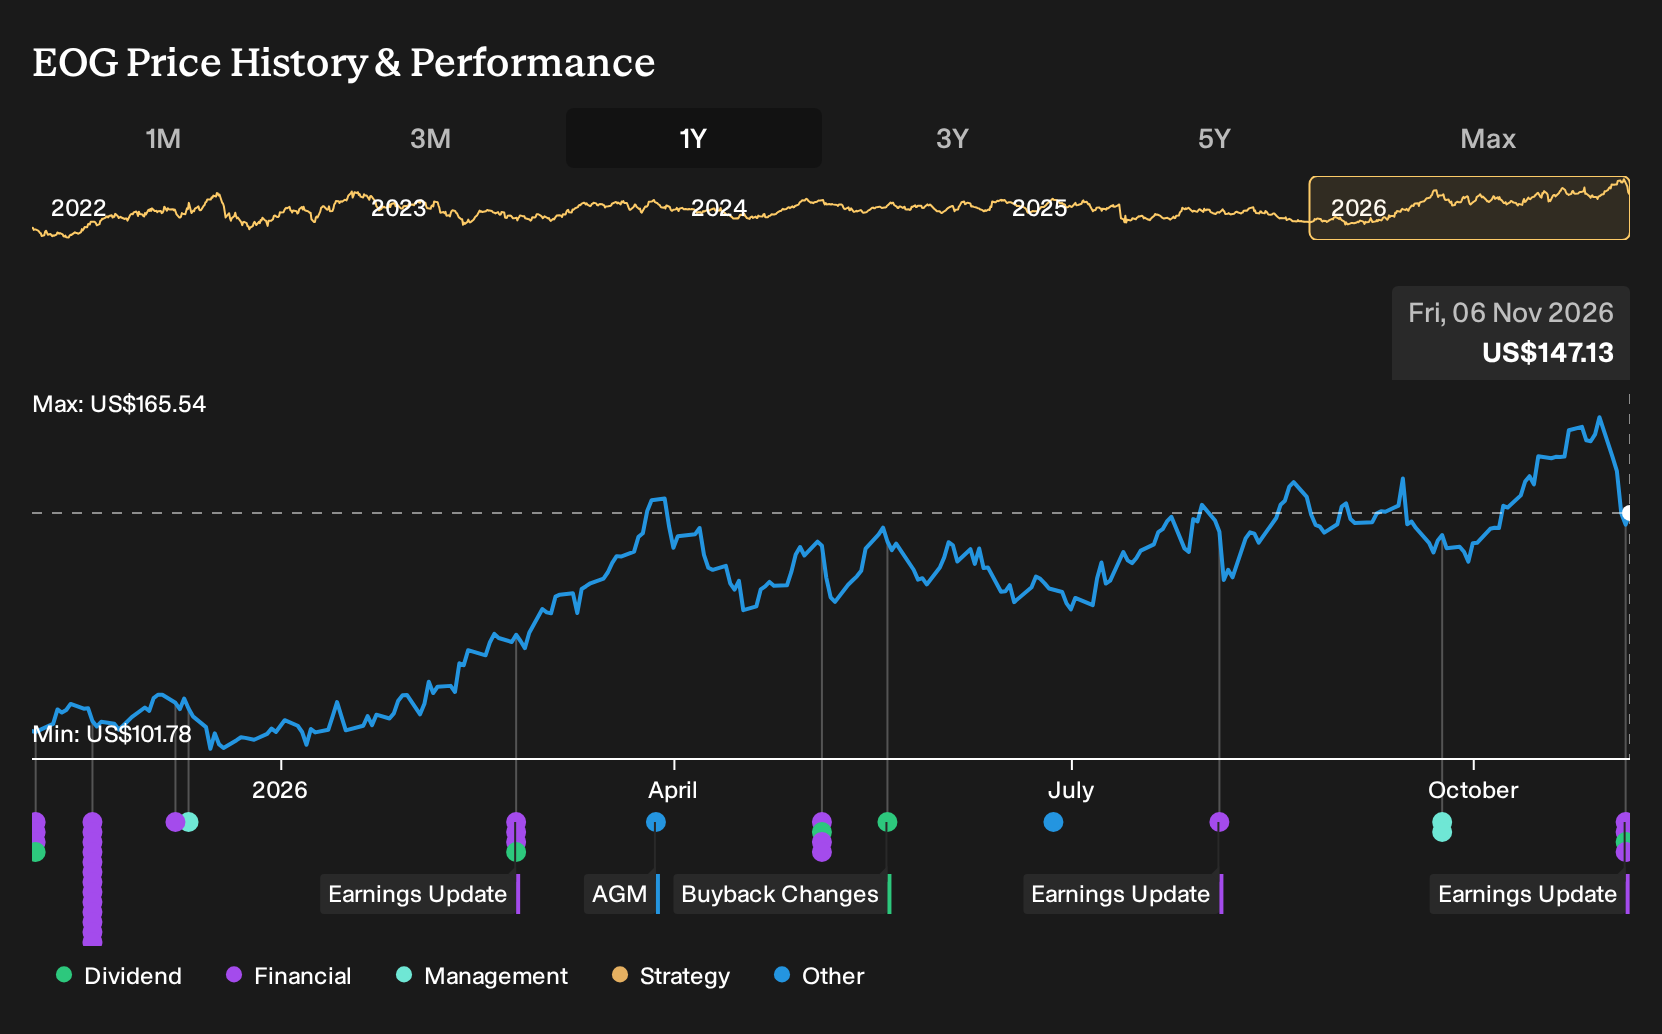
Analyst price targets cluster around US$166.41, with the stock recently at US$157.91 and individual targets stretching from US$141.00 to US$213.00. That relatively tight gap between the current price and the consensus target suggests many analysts see EOG Resources as roughly in line with their expectations rather than extremely mispriced. For readers, the useful step is to compare these margin, earnings and P/E assumptions with personal views on gas exposure, LNG contracts and the sustainability of record production levels.
EOG Resources' current analyst framework points to forecast revenue of US$26.8b and forecast earnings of US$7.2b by 2029. This setup uses flat yearly revenue growth assumptions and an earnings increase of US$0.3b from current earnings of US$6.9b.
Uncover why EOG Resources' fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The bullish narrative around EOG Resources leans heavily on the Janus and Dorado gas infrastructure as a catalyst, which contrasts with the baseline focus on execution risk. Some of the most optimistic analysts were penciling in revenue of about US$29.9b and earnings of roughly US$8.5b by 2029. Those forecasts were set before this earnings beat and dividend lift, so you may want to revisit both bullish and cautious cases to see how your own view lines up.
Explore 3 other EOG Resources fair value estimates, including one that suggests potential upside of up to 112% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis rather than relying solely on consensus views.
- A great starting point for your EOG Resources research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for EOG Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EOG Resources' overall financial health at a glance.
Looking for more EOG Resources sized ideas?
If this EOG Resources update has sharpened your view on cash generation, dividends and project execution, it can be useful to widen the lens and compare it with other opportunities on the Simply Wall St Screener platform.
- If reliable income is high on your list, scan companies that combine higher yields with balance sheet resilience by starting with our 7 dividend fortresses.
- If capital preservation matters more than chasing every rally, focus on steadier performers that screen well on risk by reviewing our 31 resilient stocks with low risk scores.
- If you want to spot potential future leaders before they are widely followed, look through our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com