


EN
Cohu Stock Returns To Profit As Revenue Outlook Rises
- Cohu reported third quarter 2026 sales of US$172.96 million, returned to quarterly profitability, and issued fourth quarter revenue guidance near US$178 million along with updated growth targets for 2026 and 2027.
- The company linked its higher 2026 and 2027 revenue outlook to an expanding high performance computing opportunity funnel, tying recent financial progress directly to demand for more complex semiconductor test solutions.
- We will now see how Cohu's investment narrative could shift in light of this raised multi year revenue guidance and profitability.
Cohu Investment Narrative Recap
Cohu appeals to investors who buy into a simple idea. Semiconductor complexity keeps rising, which supports demand for test handlers, inspection gear, and data software that can handle high performance computing and diversified end markets like automotive and industrial. The latest quarter put hard numbers behind that story, with profit returning alongside US$172.96 million in sales.
The near term hinge is whether that improving operating backdrop carries into the fourth quarter and 2027 without major stumbles in customer ramps or factory transfers to Asia. Raised revenue guidance and a profitable third quarter help that case, but customer concentration and industry cyclicality remain the clearest pressure points.
The most important piece of news around this update is the new revenue outlook. Cohu is now guiding to approximately US$178 million in fourth quarter sales, plus or minus US$7 million, and is tying its 2027 expectations to conversion of a high performance computing opportunity funnel rather than a single deal or one product cycle.
For you as a shareholder, that guidance makes the operational checklist much more concrete. Execution on high performance computing test handlers, smooth manufacturing transfers, and consistent qualification wins move from long term talking points to nearer term catalysts. Any hiccups in big customer programs or extended semiconductor downturns remain the main threats to that plan.
Cohu's current analyst playbook points to revenues of US$1.2b and earnings of US$215.2 million by 2029, based on a projected 27.6% yearly revenue growth rate and an earnings change of about US$237.8 million from a loss of US$22.6 million today.
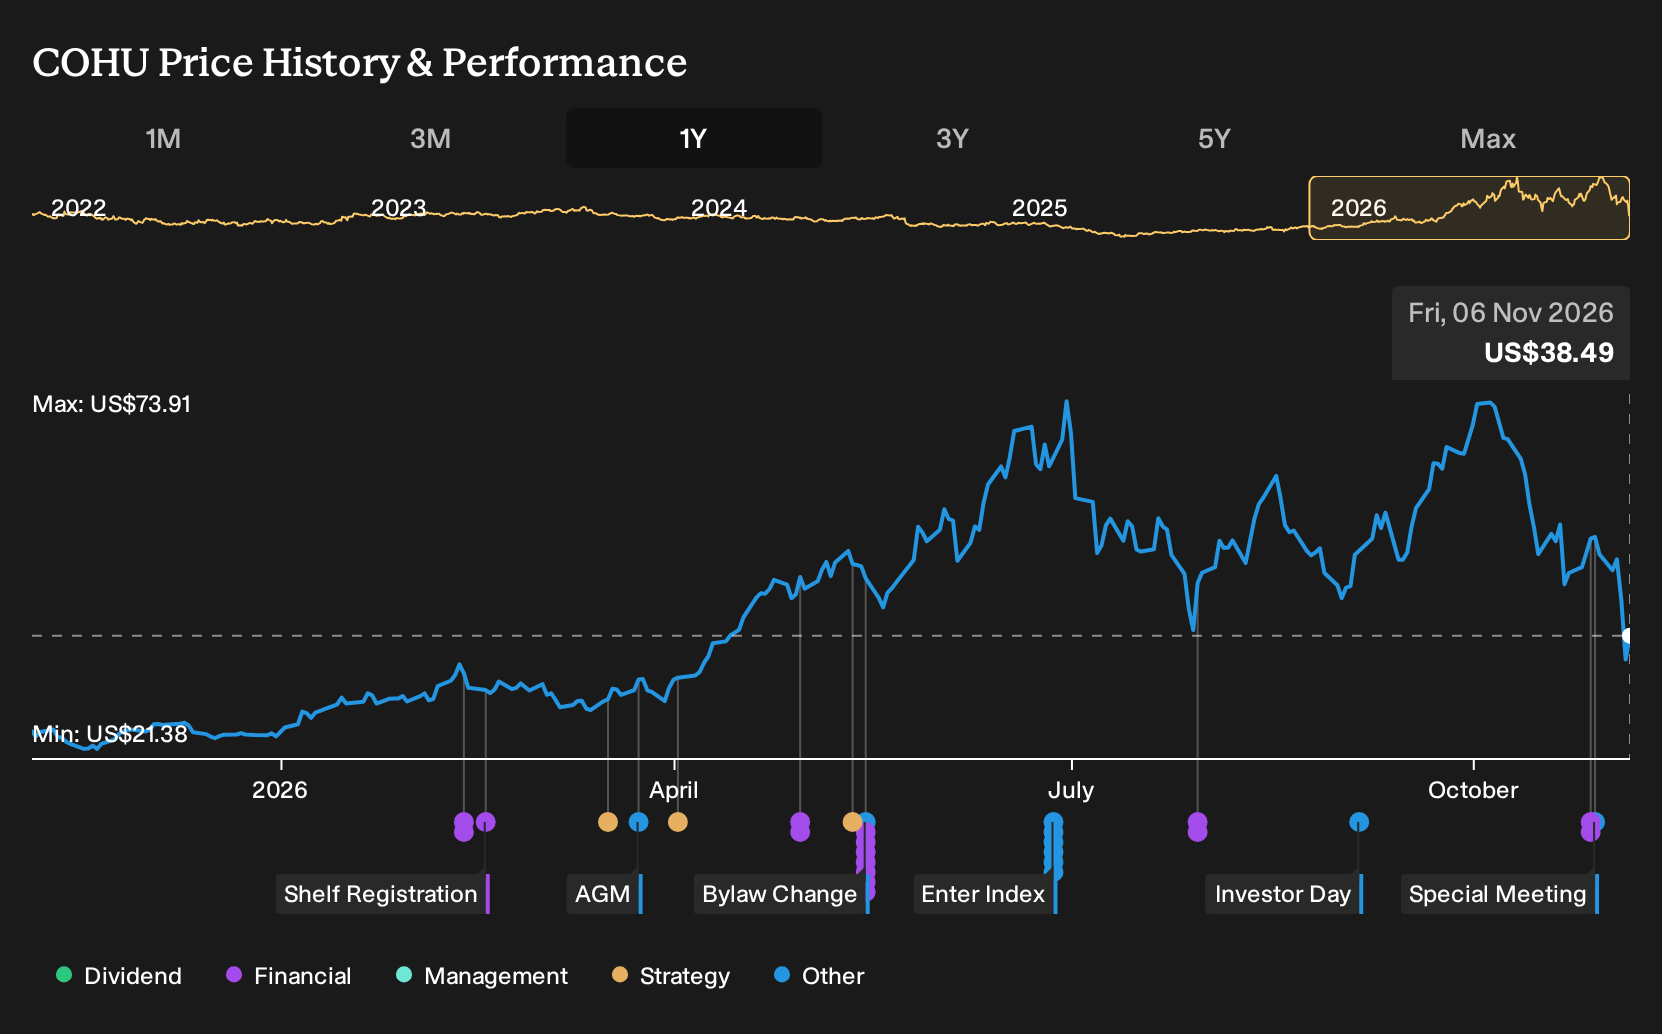
Uncover how Cohu's fair value indicates a 94% potential upside to its current price, which could narrow quickly if sentiment on Cohu shifts.
Exploring Other Perspectives
One alternate angle on Cohu leans hard into the recurring revenue story. Some analysts had previously modeled roughly 28.4% yearly revenue growth and about US$205.5 million in earnings by 2029 ahead of this guidance. Those projections were more optimistic than the broader consensus and indicate how sharply expectations might shift after this latest update.
Explore 3 other Cohu fair value estimates, including one that suggests up to 133% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cohu research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cohu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cohu's overall financial health at a glance.
Looking for more investment ideas beyond Cohu?
If Cohu has sharpened your interest in high performance computing and semiconductor enablers, it can help to widen your watchlist across different styles of opportunity and levels of risk.
- For investors who want potential mispricing with quality fundamentals, scan a curated 38 high quality undervalued stocks that may offer a different balance of risk and reward to Cohu.
- If resilience and capital preservation matter most to you, filter for businesses with steadier profiles using a 31 resilient stocks with low risk scores that focuses on sturdier metrics and lower volatility.
- To cast a wider net for lesser known opportunities, use a 19 high quality undiscovered gems that highlights companies with strong financial underpinnings but lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com