


EN
Freedom Holding (FRHC), Why Is Its Latest Update Drawing Attention?
AI infrastructure move reshapes the Freedom Holding story
Freedom Holding (FRHC) is pushing into large scale computing with plans for a US$2b Sovereign AI Hub in Kazakhstan, a public GPU cloud and a new Freedom Cloud data centre.
The programme includes a 100 MW site designed for AI model training, data heavy workloads and shared infrastructure that could appeal to businesses, developers and public institutions that want access to high end chips without building their own server rooms.
Recent trading suggests that momentum in Freedom Holding has been choppy rather than one way, with the share price up 19.23% over 90 days and 5.42% over 30 days. The 1 year total shareholder return of 26.06% sits alongside a 3 year total shareholder return of 122.64% and a 5 year total shareholder return of 155.68%, as investors weigh this AI build out against existing financial services operations.
Scan how Freedom Holding fits into the wider AI build out story by comparing it with 53 AI infrastructure stocks, which is gaining traction off similar infrastructure themes.
For Freedom Holding, the Kazakhstan AI build looks like either a logical extension of a multisegment financial group or a sentiment driven side bet on hot infrastructure themes. How far does the current valuation lean toward each story?
Preferred P/E of 77.3x: Is it justified for Freedom Holding?
Freedom Holding closed at $178.85, yet the key valuation signal many investors will focus on is its P/E multiple of 77.3x.
The P/E ratio compares the share price to earnings per share and effectively shows how many dollars investors are willing to pay for each dollar of profit. For a diversified financial group like Freedom Holding, that multiple reflects expectations around the durability of current earnings, the potential for new profit streams and the perceived risk profile of those cash flows.
FRHC has several ingredients that can help explain why the market is paying up. Earnings grew 86.3% over the past year, current net profit margins of 8.4% are higher than last year’s 5.1%, and earnings growth over the past year exceeded the Capital Markets industry figure of 28.5%. At the same time, management is leaning into higher risk funding, with 100% of liabilities coming from sources other than customer deposits. Return on Equity sits at 9.6%, which is described as low, and earnings have declined by 17% per year over the past 5 years despite the recent acceleration.
The comparison with peers is stark. FRHC is described as expensive based on its P/E ratio of 77.3x compared with the peer average of 15x, and it is also tagged as expensive versus the wider US Capital Markets industry where the average is 36.3x. On top of that, the SWS DCF model suggests the stock at $178.85 is trading above an estimated future cash flow value of $61.08, which reinforces the idea that the market price builds in generous expectations relative to both earnings and modeled cash flows.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 77.3x (OVERVALUED)
Still, the Freedom Holding story faces pressure if earnings momentum cools or the Kazakhstan AI build absorbs more cash than the current business comfortably throws off.
Find out about the key risks to this Freedom Holding narrative.
Another view on Freedom Holding’s value
The earnings multiple paints Freedom Holding as rich, yet the SWS DCF model goes further and tags the stock as overvalued at $178.85 compared with an estimated future cash flow value of $61.08. That kind of gap raises a simple question for investors: Which story feels more realistic if the AI build takes longer or costs more than planned?
Look into how the SWS DCF model arrives at its fair value.
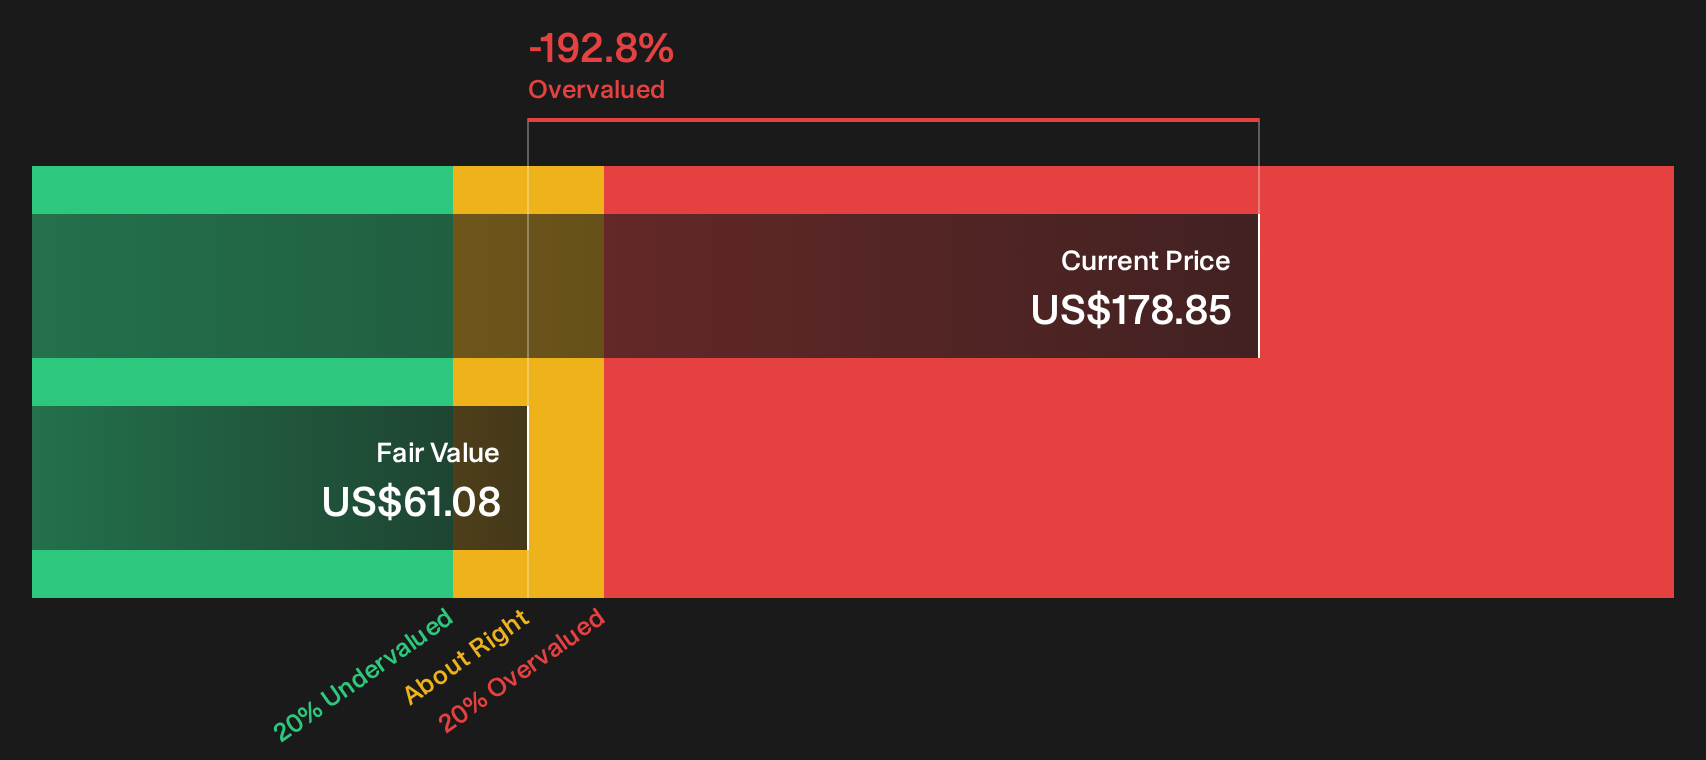
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Freedom Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Freedom Holding’s AI push and valuation can feel confusing. Move fast, review the underlying data and test your own thesis using 1 key reward and 2 important warning signs
Looking for more Freedom Holding sized ideas?
Do not stop your research with Freedom Holding. The best opportunities often sit one or two clicks beyond the obvious tickers investors already know well.
- Target steady compounding potential by scanning a 31 resilient stocks with low risk scores that keeps volatility and financial fragility from dominating your portfolio.
- Hunt for mispriced quality by zeroing in on a 38 high quality undervalued stocks that filters for strong fundamentals at prices that may look out of sync with the underlying business.
- Strengthen your core holdings by focusing on a list of solid balance sheet and fundamentals (25 results) that surfaces companies built to handle shocks without constant refinancing worries.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com