


EN
What Investors Overlooked Before Neogen's 84% Run
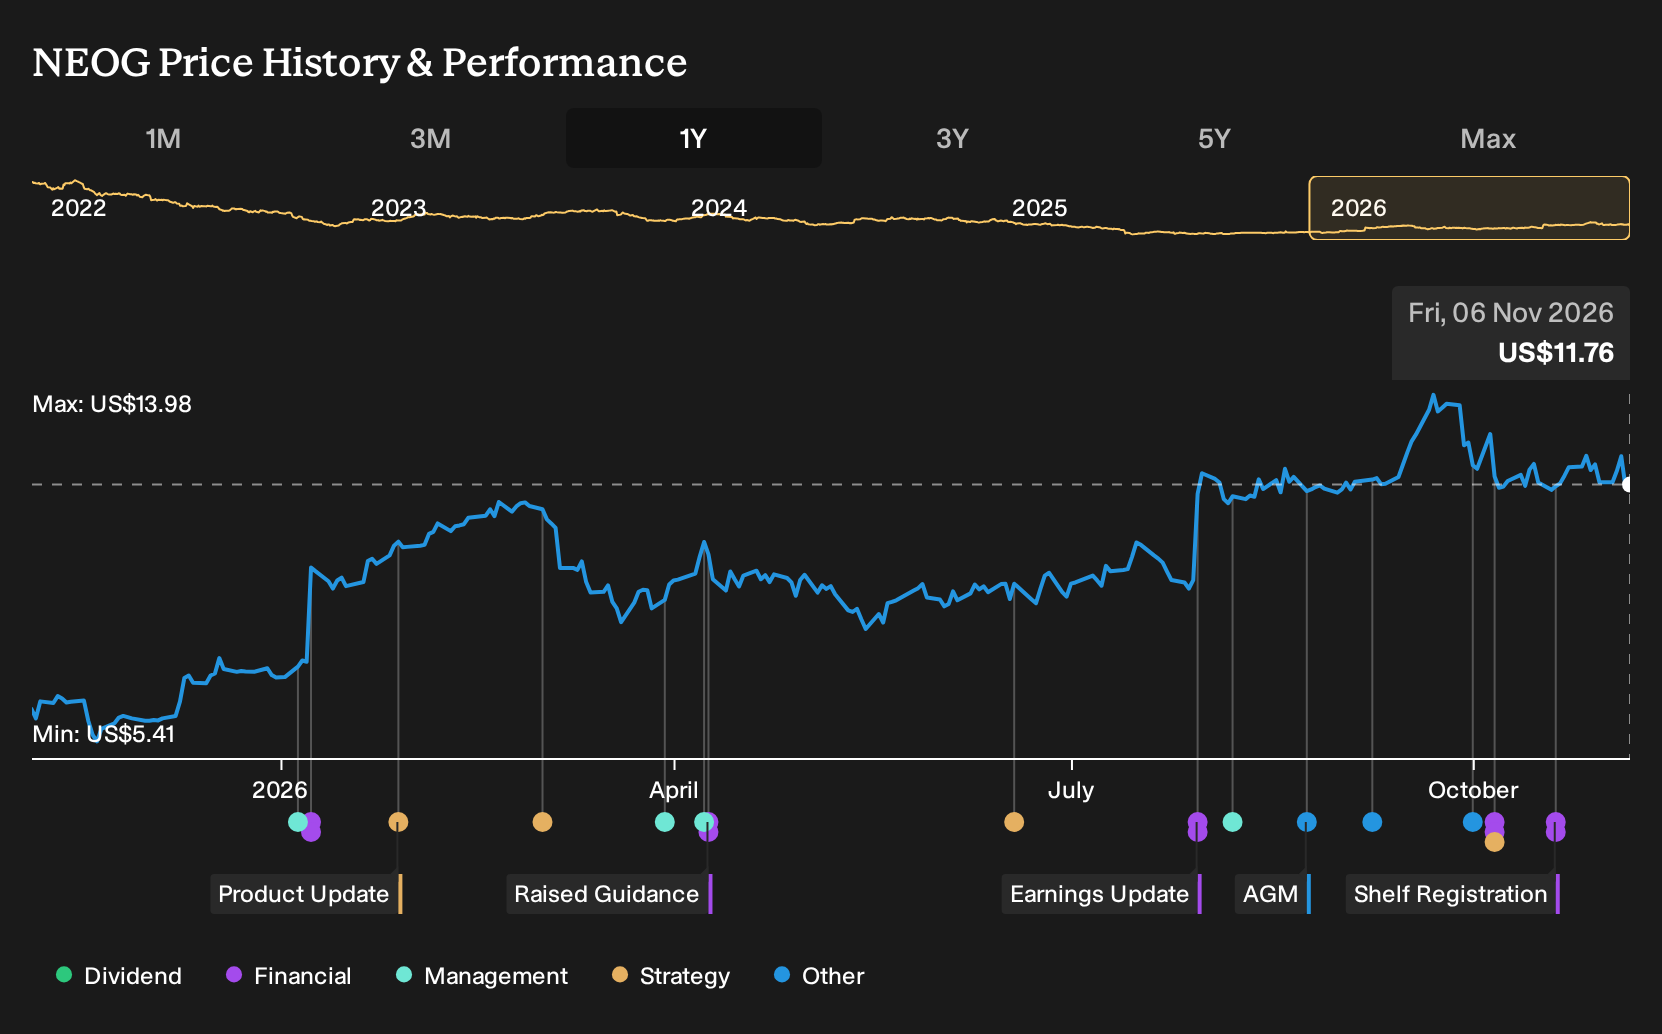
If Neogen sat on your watchlist instead of in your portfolio, the move over the past year may sting. Holding Neogen over the past year would have returned 83.8%, including dividends. That sort of gain invites a blunt question. What signals, already on record in late 2025, might have justified owning a loss-making diagnostics group on the assumption that rising profit margins from portfolio streamlining and new partnerships could eventually matter more than near term integration headaches?
The move put Neogen in the middle of this trade. Scan 35 healthcare AI stocks for other companies exposed to it.
The Argument You Would Have Been Weighing Up On Neogen
The shares cost US$5.98 at the start of the period, and anyone looking at Neogen then had to decide which of two very different stories sounded more reasonable.
The bullish narrative saw upside to a Fair Value of US$6.5, a price implied by assumptions that tighter food safety rules and portfolio streamlining would allow higher future margins, even though analysts still expected revenue to fall 1.3% a year and did not project profits within three years.
The bearish view pointed to a Fair Value of US$5, based on expectations that weak demand, a 1.5% annual revenue decline and ongoing 3M Food Safety integration problems could keep Neogen under earnings pressure despite the same long term margin target.
What The Neogen Evidence Actually Tested
Neogen’s Q1 FY 2027 update showed revenue at US$222.8 million versus US$209.2 million a year earlier, which leaned toward the bullish case that tighter food safety rules and partnerships could support the top line. The same period reported a net loss of US$11.9 million compared with prior net income of US$36.3 million and a net margin that moved from 17.4% to a loss of 5.3%. That mix cut both ways for the original thesis on rising margins.
The useful takeaway is simple: when a story hangs on better profitability, track net margin and absolute earnings alongside any upbeat revenue or guidance language. Then decide if the claimed margin journey is actually showing up in reported numbers at your next watchlist company.
What Neogen’s Price Now Asks You To Believe
Neogen shares trade at US$11.76, and the selected Narrative’s Fair Value sits above that level based on its own assumptions rather than any proven outcome. The argument leans on scale, consumables and efficiency gains as potential offsets to recall, regulatory and quality setbacks.
On that view, today’s price does not fully credit the possibility that Neogen converts its installed base and analytics platform into higher recurring consumable use and stronger long term margins.
"If Neogen continues to convert its large installed base of more than 50,000 instruments and 70,000 customers into higher recurring consumable usage, including through Neogen Analytics where sites use more than 1.5x consumables, revenue and earnings could track closer to a compounding software and consumables model than the bearish case assumes."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
One Step Beyond Neogen
Neogen keeps you focused on lab results, contamination risks and regulatory pressure. One step away sits a different kind of healthcare engine.
Where Neogen leans on diagnostics, this other business leans on care programs and digital plumbing. It tries to manage treatment plans, pharmacy spending and data handling in one loop.
The goal is simple. Keep people healthier for longer, while squeezing waste from how care is delivered and paid for.
To get there, it leans heavily on software, workflow tools and AI that targets back office drudgery. Claims, call centres and clinical paperwork all sit in scope.
If that push really sticks, your watchlist might need to handle a very different healthcare story alongside Neogen.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 22% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com