


EN
What Investors Got Wrong About Tata Chemicals Before The Drop
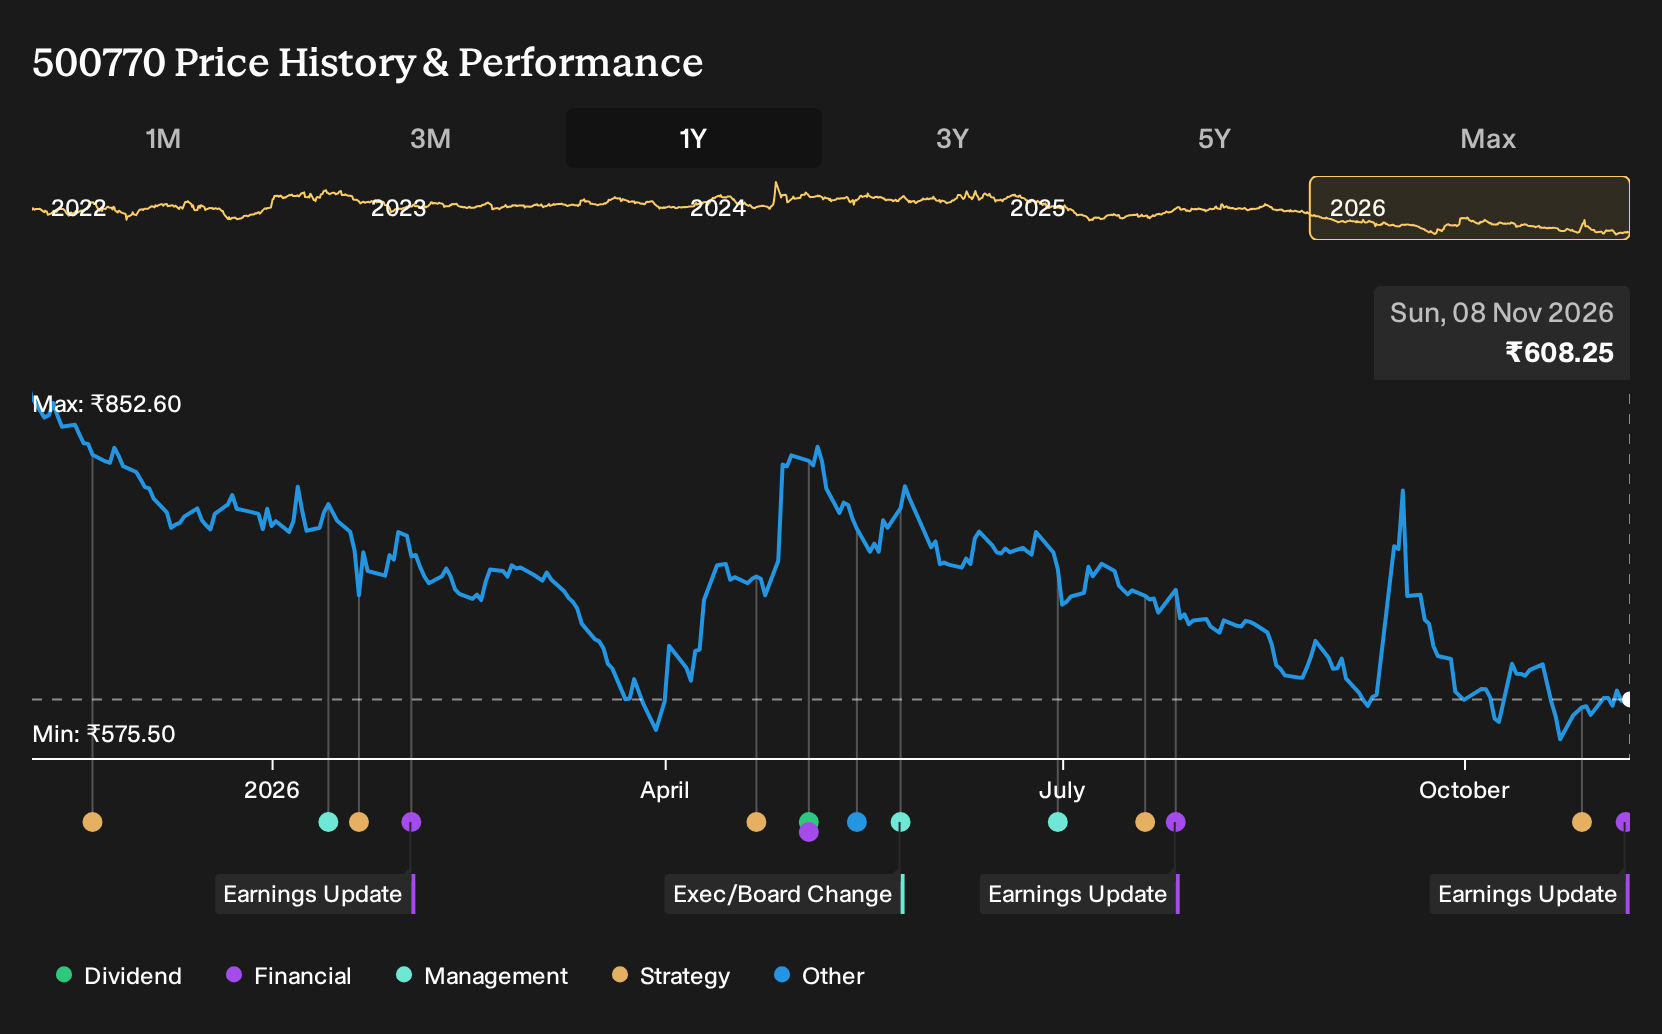
If you had looked at Tata Chemicals in late 2025 and decided to sit it out because the bullish and bearish analyst camps were so far apart on fair value, that hesitation might feel easier to live with today. Investors who held Tata Chemicals over the past year are down 28.0%, including dividends. With revenue at ₹42,720m and a reported net loss in Q2 2027, which early assumptions about soda ash capacity, specialty roll-out, or rising costs most deserved a harder look?
If the move has made Tata Chemicals harder to judge, start where the gap is still open and scan 225 high quality undervalued stocks.
The Two Tata Chemicals Stories Investors Were Weighing
The shares cost ₹858 at the start of the period, and Tata Chemicals investors were pulled between two very different stories about what might come next.
On the bullish side, the optimistic narrative pointed to a fair value of ₹1,127, effectively a price implied by faith in specialty chemicals, with the thesis built around EV adoption, food security themes, and higher margin projects such as bicarb and pharma salt.
The cautious narrative put fair value at ₹780, an implied level based on concerns that excess soda ash capacity in places like China and Mongolia, plus heavy capital outlay, could keep margins under pressure for years.
What The Results Changed For Tata Chemicals
Revenue at Tata Chemicals moved from ₹38,770m in Q2 2026 to ₹42,720m in Q2 2027, which lent some weight to the optimistic story about demand and project ramp up. The shift from a profit of ₹770m to a net loss of ₹1,220m, and a net margin sliding from 2.0% to 2.9% in the red, clearly supported the cautious case on earnings pressure.
The key assumption here was straightforward: higher capacity and specialty projects were expected to support profit as well as sales. When you look at another chemicals stock, test that idea by tracking net margin and absolute net income alongside revenue, rather than treating revenue alone as proof of a stronger thesis.
What Tata Chemicals' Lower Price Now Asks You To Believe
Tata Chemicals trades today at ₹608, which leaves the selected Narrative's Fair Value above the current price. The view leans on a shift toward non cyclical, value added lines rather than a soda ash recovery story.
For that higher figure to be realised, a buyer today would need Living and Farm Essentials projects to offset prolonged soda ash weakness.
"Resegmentation into Living Essentials, Industrial Essentials and Farm Essentials, together with capital allocation that favours less cyclical products like salt, bicarbonate and prebiotics, points to a growing share of non cyclical revenue that could make Tata Chemicals’ consolidated earnings and net margins less sensitive to soda ash pricing cycles."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Tata Chemicals
Tata Chemicals keeps drawing attention to specialty products tied to food and daily life. One step away, another business is focused on feeding the soil itself.
This other producer is not chasing soda ash or pharma ingredients. It is trying to supply a key crop nutrient more cheaply, using oil drilling style methods instead of huge traditional mines.
The approach aims to cut surface disruption and water use, while still producing fertilizer material farmers rely on.
If that method proves itself at scale, your watchlist for agriculture exposure may not stop with Tata Chemicals.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 45% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com