


EN
Alvotech Stock After Guidance Reaffirmed Has The Bull Case Changed?
- Alvotech reaffirmed its 2026 outlook for total revenue of US$650 million to US$700 million and adjusted EBITDA of US$180 million to US$220 million, even after reporting first half 2026 revenue of US$212 million that was 31% lower year on year due to manufacturing slowdowns and supply constraints.
- The reaffirmed targets keep attention on whether Alvotech’s upgraded multi site manufacturing network and biosimilar launch execution can support a much stronger second half and more reliable cash generation.
- We will now look at how Alvotech’s investment narrative is affected by reaffirmed 2026 guidance despite earlier operational disruptions and funding needs.
Compare Alvotech's setup with other potential rebound stories by scanning our hand picked 38 high quality undervalued stocks, which also trade at compressed P/S multiples and face execution questions.
Alvotech Investment Narrative Recap
Owning Alvotech means believing the upgraded manufacturing network and broad biosimilar portfolio can turn reaffirmed 2026 guidance into more predictable cash generation. The biggest near term swing factor is execution on those facilities after a first half hit by slowdowns and supply constraints. If operating stability improves, the business case tightens.
The flip side is clear. The required step up to reach US$650 million to US$700 million of 2026 revenue and US$180 million to US$220 million of adjusted EBITDA leaves little margin for further disruption. Any fresh quality issue, delay in biosimilar rollouts or supply shortfall would likely test that roadmap quickly.
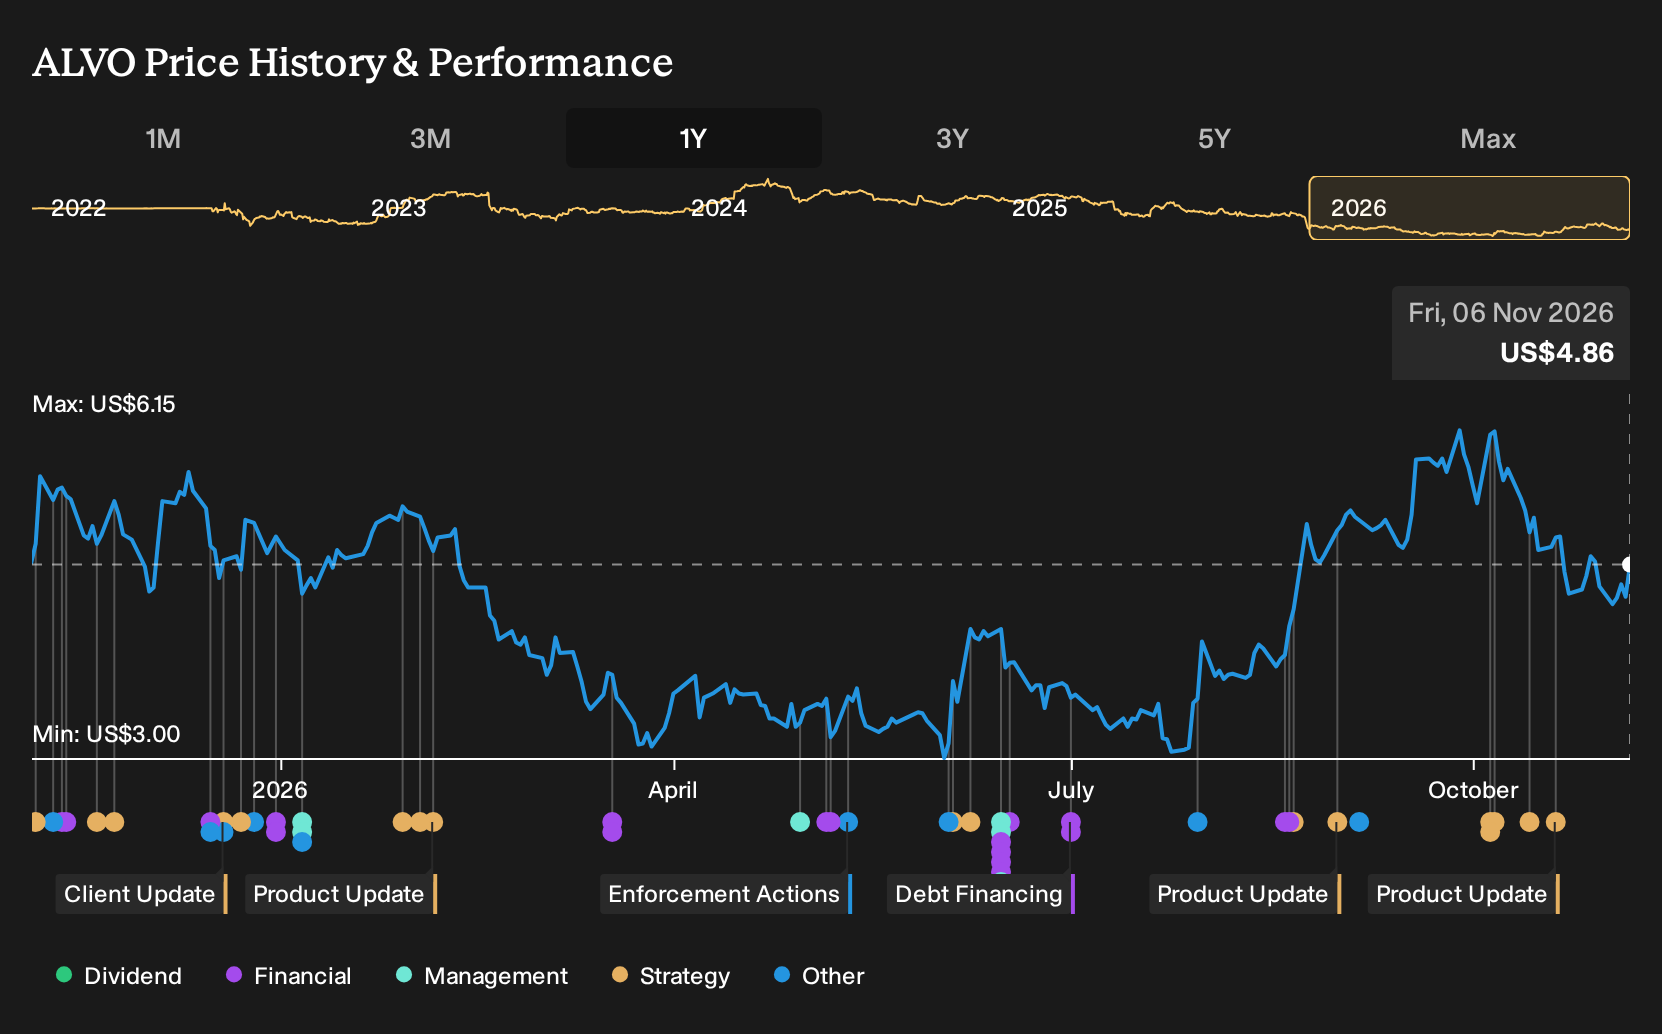
The most relevant recent development is the decision to reaffirm 2026 guidance despite a 31% year on year decline in first half 2026 revenue to US$212 million. That choice keeps the focus squarely on whether facility upgrades, including added capacity with partners, can support the needed ramp without repeating past bottlenecks.
For you as a shareholder or potential investor, that guidance now functions as both catalyst and stress test. Meeting it would point to smoother execution on Simponi, Entyvio, Eylea and other launches. Falling short would raise fresh questions about funding needs, interest costs on the new term loan and the sustainability of Alvotech’s current cost base.
Alvotech's current analyst narrative points to forecast revenue of US$984.0 million and earnings of US$202.4 million by 2029, anchored on revenue growth expectations of 25.8% per year and an earnings swing of about US$382.0 million from a loss of US$179.6 million today into positive territory.
Uncover why Alvotech's fair value indicates a 48% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on earnings power rather than 2026 guidance. The most pessimistic analysts were looking for around US$790.5 million of revenue and US$141.1 million of earnings by 2029, well below the consensus path. This view sees a version of Alvotech where execution risks stay front and center. Those forecasts were set before this reaffirmed outlook, so you may want to compare both narratives and decide which assumptions feel closer to your own.
Explore 4 other Alvotech fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alvotech research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alvotech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alvotech's overall financial health at a glance.
Looking For More Ideas Beyond Alvotech?
Once you have a view on Alvotech, it can help to set that thesis alongside other opportunities so you can judge risk, quality and upside on the same footing. The Simply Wall St Screener gives you ready made shortlists that focus on different angles, from resilience to income to overlooked quality.
- If capital protection comes first for you, start with a basket of companies flagged as relatively resilient using our 31 resilient stocks with low risk scores.
- If income is a priority, scan for businesses offering stronger yields and more robust payout profiles through the 7 dividend fortresses.
- If you prefer under the radar stories where fundamentals already look solid, sort through the 19 high quality undiscovered gems and see which ones deserve a place on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com