


EN
Is Debt Raise And Earnings Growth Altering The Investment Case For NiSource (NI)?
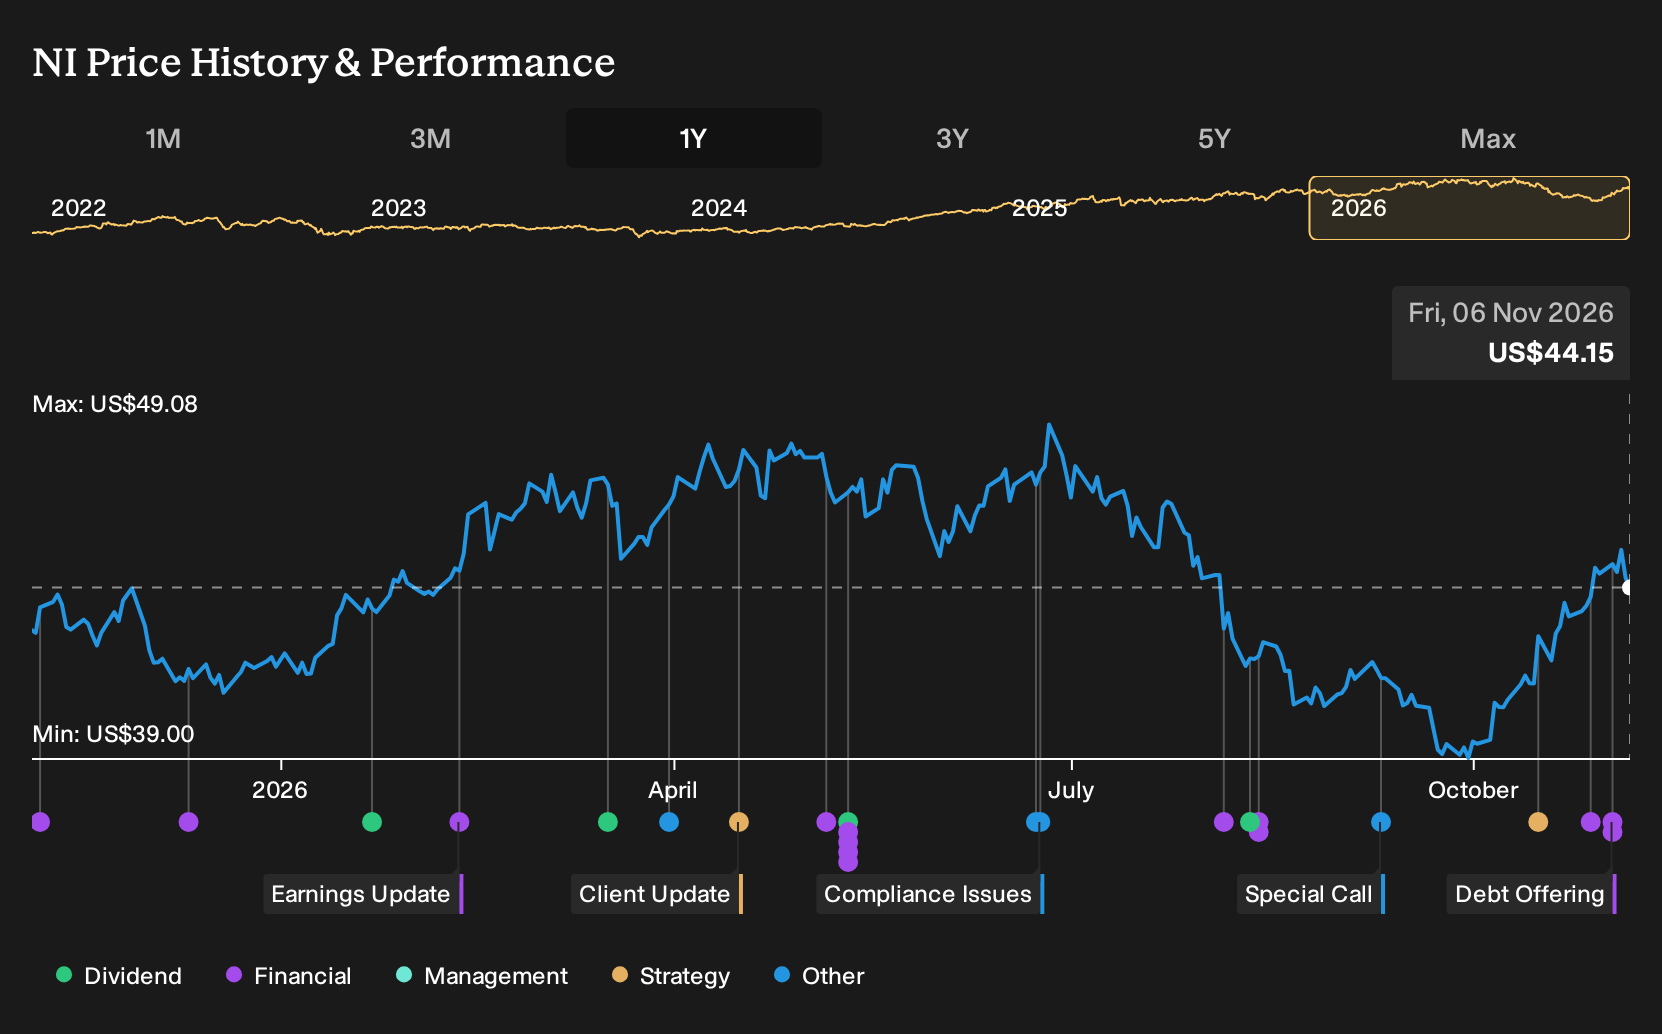
- NiSource has issued fixed rate senior unsecured notes due 2032 with a 5.400% coupon, raising about US$598.5 million after pricing at 99.752% of a US$600 million principal amount, shortly after reporting higher third quarter 2026 sales, revenue and net income versus the prior year.
- The combined debt raise and earnings update provide investors with more detail on how NiSource is funding its regulated capital program, and how that spending is being translated into higher sales, revenue and earnings per share from continuing operations.
- Investor attention now turns to how NiSource's fixed income raise at a 5.400% coupon fits within its long term regulated investment narrative.
Scan how NiSource funds growth through its balance sheet, then compare it with list of solid balance sheet and fundamentals (25 results), which is built to support ongoing capital programs and earnings stability.
NiSource Investment Narrative Recap
To own NiSource, you need to believe its long regulated capital plan can keep translating into steady earnings from gas and electric service, while customer bills and regulators stay onside. The recent 5.400% notes and the latest quarter, where revenue and net income were higher than a year earlier, both speak directly to that execution.
The short term swing factor is how regulators treat NiSource spending on modernization and data center load, given prior margin pressure and tighter scrutiny in Indiana. The main risk is that heavy capex and added debt, now including these 2032 notes, keep leverage and interest costs high relative to earnings coverage.
The 5.400% fixed rate notes due 2032 look most relevant for you as a shareholder because they plug directly into that US$28.6b long term capital plan. NiSource is choosing to lean on unsecured, senior debt that sits alongside ongoing equity issuance, which keeps the balance sheet central to the equity story.
This bond issue matters operationally because it dictates how much financial room management has as data center projects and grid upgrades move forward. Higher interest expense can tighten coverage if earnings growth slows. The key catalyst is steady progress on bringing new electric load and rate based projects into earnings to support that larger debt stack.
NiSource's current analyst narrative points to revenues of US$8.6b and earnings of US$1.4b by 2029, based on an assumed 7.3% annual revenue growth rate and an earnings increase of about US$466m from US$933.7m today.
Uncover how NiSource's fair value indicates an 8% potential upside to its current price that could narrow quickly as new data is released.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$35.97 and US$47.72, which shows how far private investors can stretch on NiSource assumptions. These opinions were set before the 5.400% bond issue and the latest earnings, so you may want to test how fresh financing and electrification risks reshape those views.
Explore 2 other NiSource fair value estimates, including one that suggests as much as 19% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your NiSource research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NiSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NiSource's overall financial health at a glance.
Looking for more investment ideas beyond NiSource?
Once you have formed a view on NiSource, it can help to set it beside other opportunities using the Simply Wall St Screener so you can see how it stacks up on balance sheet strength, valuation and risk.
- If you want to focus on financial resilience first, compare NiSource with a broader 31 resilient stocks with low risk scores that rate well on stability and downside protection.
- For investors leaning toward value, line up NiSource next to a wider 38 high quality undervalued stocks that combine quality fundamentals with potentially attractive pricing.
- If income is a priority, weigh NiSource against a hand picked 7 dividend fortresses that aim to pair higher yields with business durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com