


EN
Century Aluminum Stock Gets An Earnings Beat And Oklahoma Smelter Progress
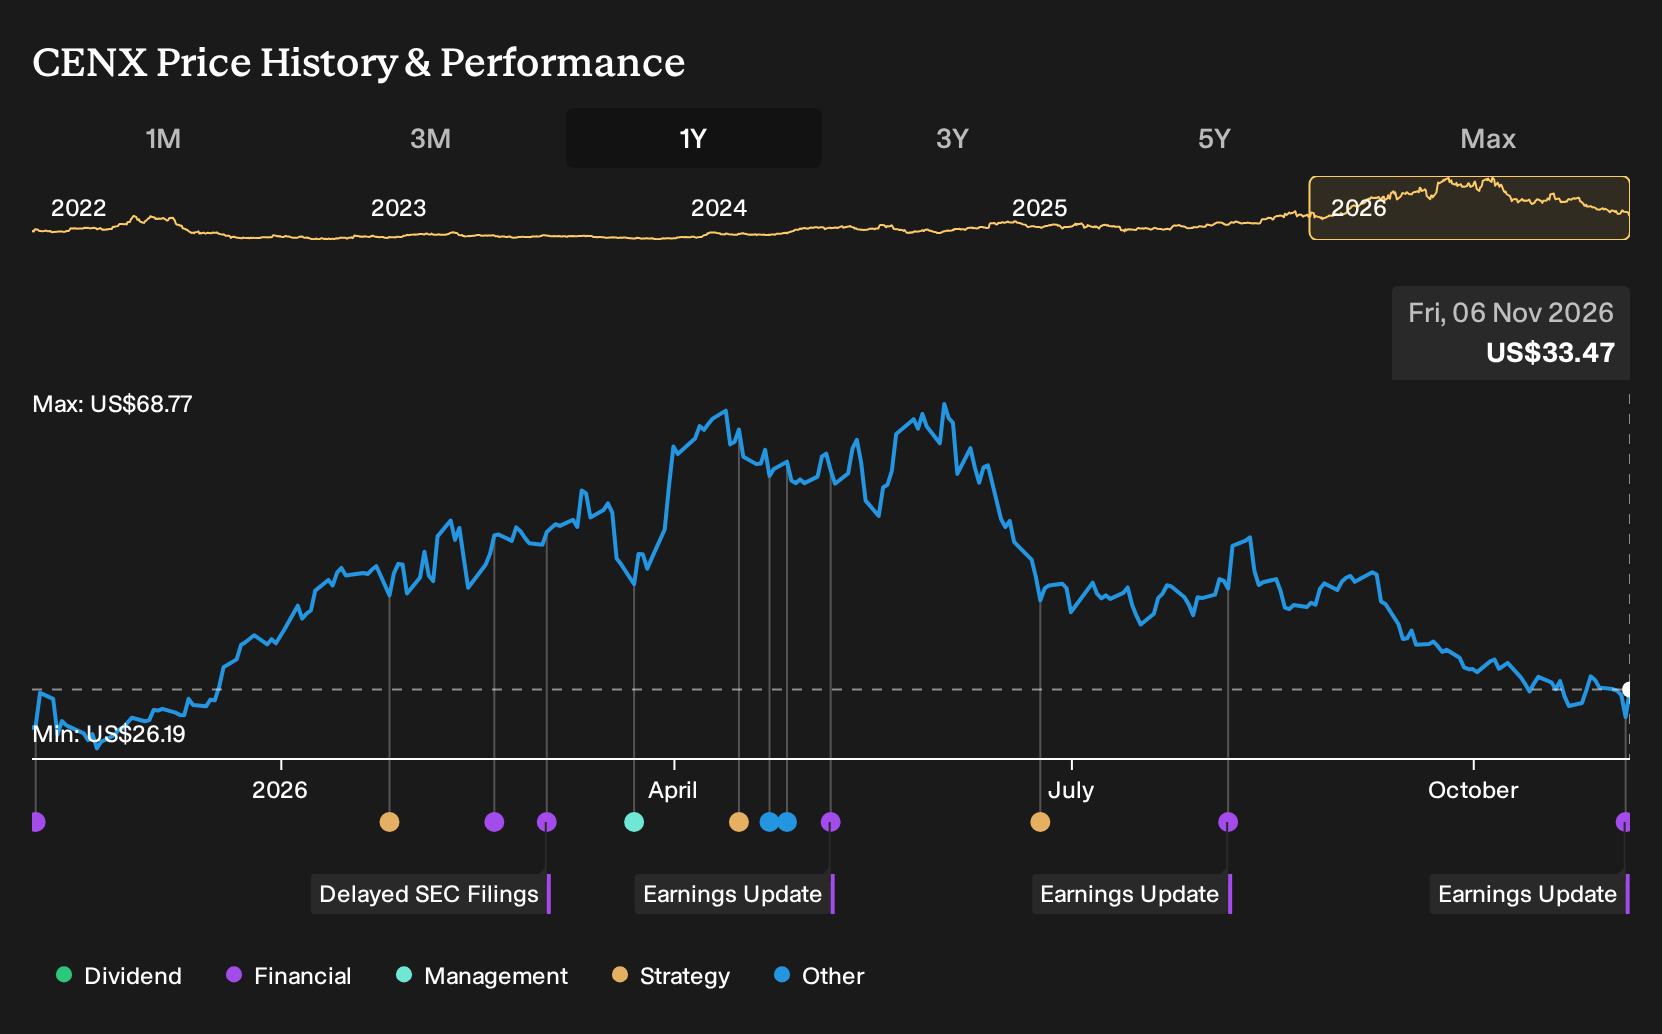
- Century Aluminum reported Q3 2026 revenue of US$961.2 million and net income of US$302.6 million, with earnings per share from continuing operations of US$2.89 on a diluted basis, alongside higher year to date sales and profit versus the prior period.
- The Oklahoma smelter project advanced with updated environmental plans, financing progress and power contract work, linking Century Aluminum’s recent earnings results to a larger build out of U.S. primary aluminum capacity.
- This article will look at how Century Aluminum’s investment narrative is shaped by its Q3 earnings and the momentum on the Oklahoma smelter project.
Century Aluminum Investment Narrative Recap
For a shareholder in Century Aluminum, the core belief is that tight aluminum supply, full smelter utilization and projects like Oklahoma can keep cash generation robust enough to support both growth and a stronger balance sheet. Q3’s nearly US$1b in revenue and US$302.6 million in net income, helped by restarts and solid demand, reinforce that operating backdrop rather than changing it.
The key near term catalyst is continued high cash conversion from the now fully running system, especially as Jamalco costs and raw material pricing stay in focus. The biggest current risk is weaker LME or regional premiums, which would quickly flow through to shipment values and adjusted EBITDA, even if volumes hold steady.
The most relevant development here is management’s progress on the proposed US$4b Oklahoma smelter, which is moving toward a Final Investment Decision with updated environmental permits, advancing financing terms and power contract work. That project links directly to the volume and cost story that underpins the Century Aluminum thesis.
For you, the link between Oklahoma and Q3’s strong profit is simple. Higher current cash balances, now well above total debt, make it easier to fund Century Aluminum’s share of the build while still leaving room to think about future shareholder returns. Execution risk sits in construction timing, energy pricing and community or regulatory friction around the new facility.
Century Aluminum's narrative projects US$4.7b in revenue and US$1.2b in earnings by 2029. This is based on analysts' forecast of yearly revenue growth of 20.9% and an earnings increase of about US$597m from current earnings of US$603.0m.
Uncover why Century Aluminum's fair value indicates an 80% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most cautious analysts focus less on Oklahoma as upside and more on the risk that Jamalco keeps alumina costs heavy. Before these Q3 Century Aluminum numbers, the lowest forecasts only had revenue reaching about US$4.0b and earnings of roughly US$765.3 million by 2029. That is a much harsher story than consensus. You now have fresh information that those older estimates did not include, so it can be worth comparing several viewpoints before deciding how you see the next chapter.
Explore 4 other Century Aluminum fair value estimates, including one that suggests it could be worth just $40.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Century Aluminum research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Century Aluminum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Century Aluminum's overall financial health at a glance.
Looking For More Ideas Beyond Century Aluminum?
Once you have a view on Century Aluminum, it can help to widen the lens and line it up against other opportunities using the Simply Wall St Screener. That way you can compare different balance sheets, cash profiles and income streams side by side instead of assessing this one stock in isolation.
- If you want to focus on companies that combine robust financial footing with earnings support, run a filter using the list of solid balance sheet and fundamentals (25 results) and see which ones match your preferred risk profile.
- For investors who care most about quality businesses that might be priced below what their fundamentals imply, sort through the 38 high quality undervalued stocks and check which candidates deserve a closer look.
- If stability matters more than excitement in your portfolio, narrow the field with the 31 resilient stocks with low risk scores and compare those results with what you see in Century Aluminum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com