


EN
Veolia Environnement (ENXTPA:VIE) Wins New Water Deals As Guidance Backs Its Valuation Story
Veolia Environnement (ENXTPA:VIE) has just lined up new desalination work worth nearly €200 million in Oman and the UAE, regained Woonsocket’s wastewater plant, and reaffirmed 2026 earnings guidance, which is sharpening investor focus.
These contracts and the guidance confirmation sit against a share price that has climbed 12.08% year to date and delivered a 22.25% total shareholder return over the past year. The 90 day share price return has dipped 2.29%, hinting at cooling short term momentum after a strong run.
Scan how Veolia Environnement fits into the wider utilities story by lining it up against a curated list of solid balance sheet and fundamentals (192 results) that shares a similar defensive, infrastructure-heavy profile.
Veolia Environnement now trades at a double discount, both to intrinsic value estimates and to analyst targets, even after a strong 1 year run. Is the market being prudently cautious, or is it too slow to reprice the recent contract wins and the confirmation of guidance?
Most Popular Narrative: 13% Undervalued
Veolia Environnement's most followed narrative pegs fair value at €38.67 per share, above the latest close of €33.78. This frames current pricing as cautious relative to that earnings path.
Synergies from prior transactions and ongoing efficiency programs are now joined by targeted cost synergies from Clean Earth of €120m by year 4 and a continued €350m per year efficiency objective across the group. Together, these are aimed at supporting EBITDA margins and earnings growth over the next several years.
See why 55 investors see Veolia Environnement as 13% undervalued.
Result: Fair Value of €38.67 (UNDERVALUED)
Still, if delays in Water Technologies or weaker areas such as French municipal waste persist, the upbeat narrative around Veolia Environnement could quickly look too optimistic.
Find out about the key risks to this Veolia Environnement narrative.
Another View: Veolia Environnement Through The P/E Lens
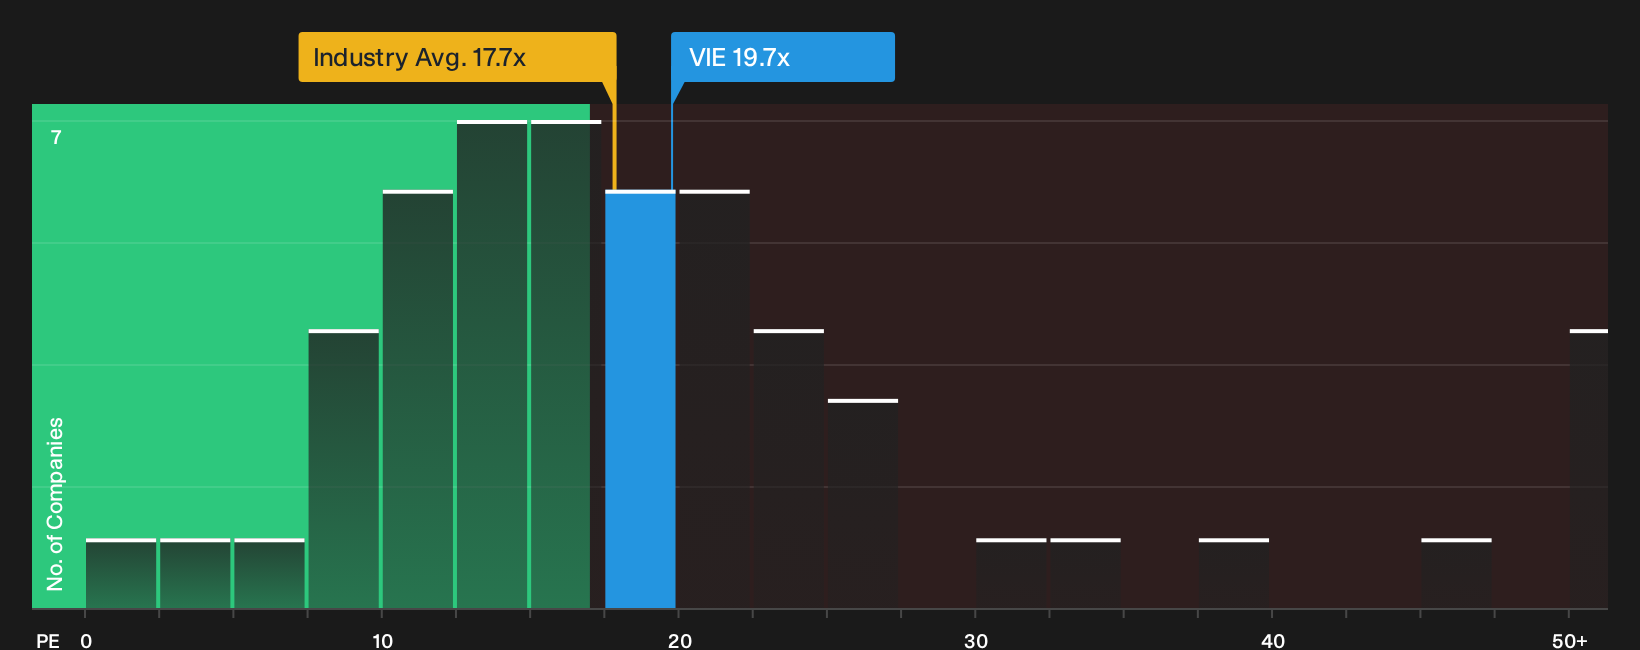
The SWS DCF model paints Veolia Environnement as materially undervalued, with a fair value of €73.70 per share versus the current €33.78. The P/E story is different. At 19.7x earnings, the stock trades above the 17.7x global integrated utilities average and a 19.2x fair ratio. Is the cash flow model generous, or are multiples too tight?
For a closer look at how this earnings multiple compares with peers and the fair ratio the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Veolia Environnement's valuation and risk reward profile can be hard to process at a glance. Move quickly, test the data against your own expectations, then pressure test that view against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Veolia Environnement?
If Veolia Environnement has sharpened your thinking on valuation and risk, do not stop here. Broaden your watchlist now or you may miss opportunities building quietly elsewhere.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (192 results), which screens for strength rather than hype.
- Hunt for mispriced quality by reviewing the 225 high quality undervalued stocks, which highlights stocks where fundamentals and current pricing do not fully align.
- Stack potential income on top of capital returns using the 228 dividend fortresses, which focuses on higher yield opportunities with staying power in their payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com