


EN
Earnings Call Might Change The Case For Investing In Sally Beauty Stock (SBH)
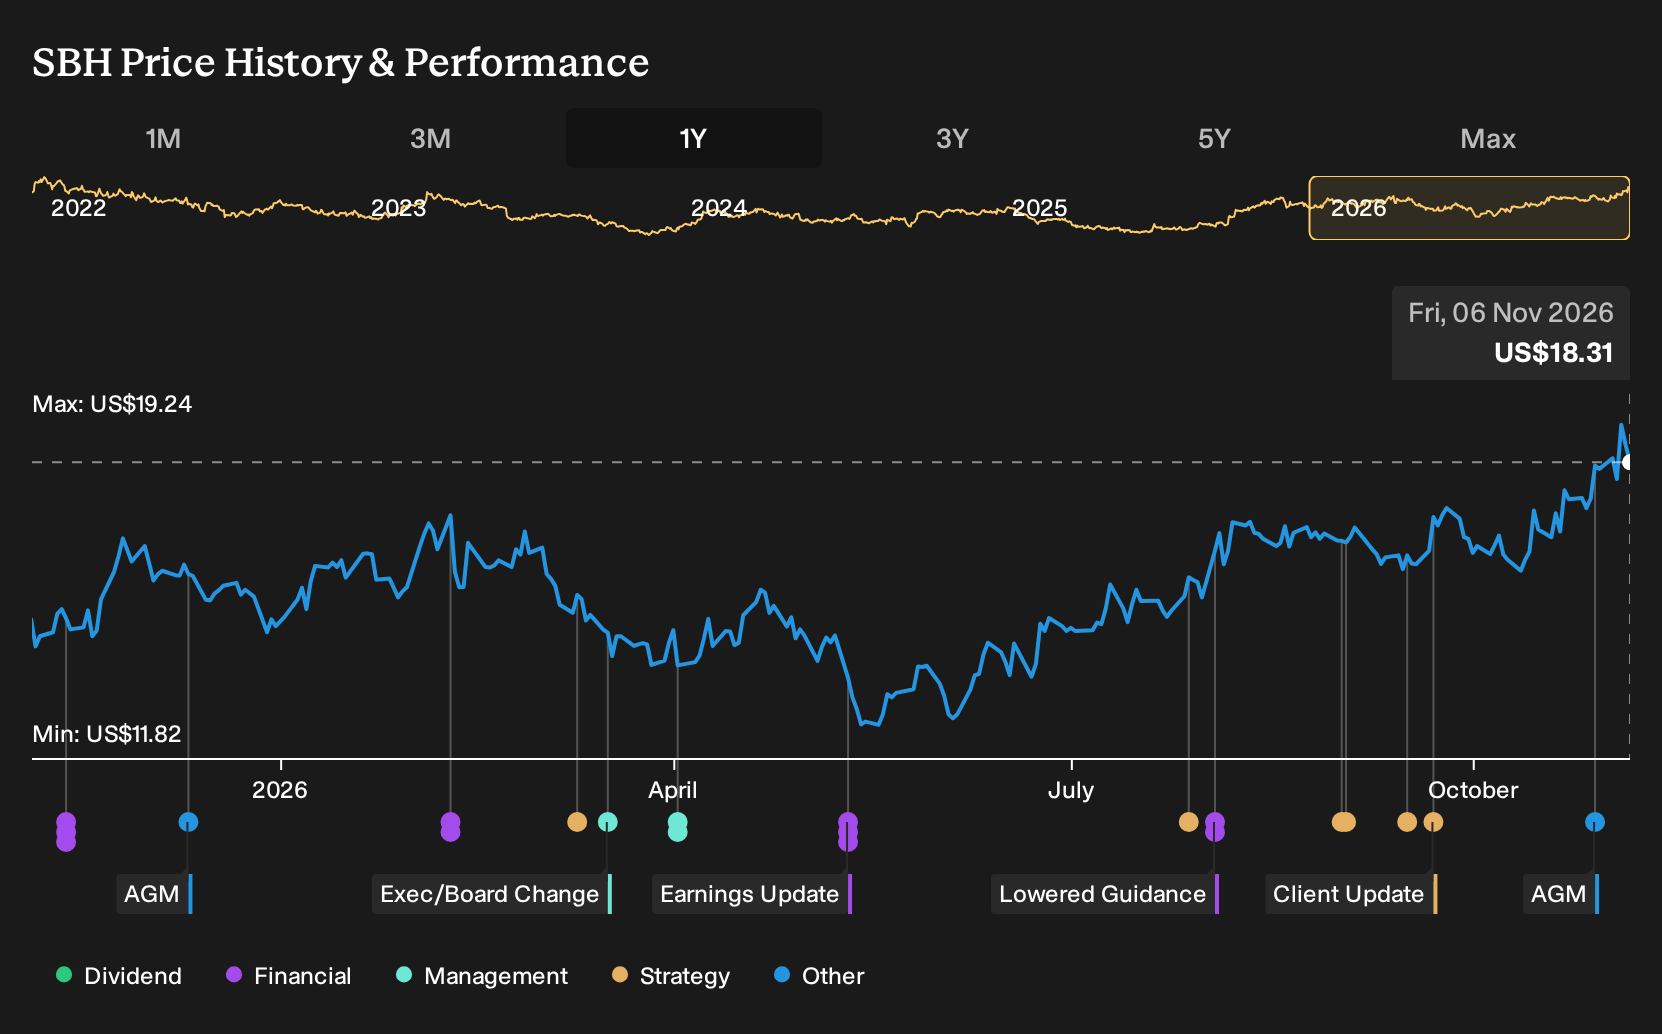
- Sally Beauty Holdings is drawing attention ahead of its late 2026 earnings call and annual meeting, as investors consider how its recent multi year share price strength aligns with current earnings power.
- The stock trades on a P/E ratio below specialty retail peers, which has sharpened the focus on whether its valuation reflects underlying profitability and cash generation.
- We will now look at how Sally Beauty Holdings' investment narrative could be influenced by increasing attention on its lower P/E valuation.
Compare Sally Beauty Holdings' lower P/E story with a curated set of other value opportunities by scanning our 38 high quality undervalued stocks, which also features companies with strong balance sheets and cash flows.
Sally Beauty Holdings Investment Narrative Recap
Sally Beauty Holdings appeals to shareholders who think the core beauty supply model can stay resilient, while cost programs and digital initiatives support earnings. The near term focus is on whether LCOD consultations, e commerce growth and store remodels can offset softer demand in care and ancillary categories that have been under pressure through 2026.
The biggest near term catalyst is clear operational evidence that value focused stylist spending is stabilising or improving in Beauty Systems Group. The key risk is that this more cautious buying pattern persists, which would keep care sales under strain, limit mix improvement and make it harder for management to translate Fuel for Growth savings into stronger net margins.
With no fresh company announcements since the share price move, the most relevant reference point is still the Fuel for Growth cost program. Management has targeted about US$45 million of benefits in fiscal 2026 and a run rate of US$120 million over three years, alongside a 40 basis point uplift in adjusted gross margin in Q3 2026.
For an investor weighing Sally Beauty Holdings today, the question is whether those savings and store refresh efforts such as Sally Ignited and Happy Beauty can meaningfully counter softer care demand, stylist down trading and competitive digital offerings. Progress against those goals is likely to frame discussion at the late 2026 earnings call and annual meeting, given the lower P/E multiple.
Sally Beauty Holdings' current analyst narrative points to revenues of US$3.9b and earnings of US$266.7 million by 2029, based on an assumed 1.4% yearly revenue growth rate and an increase in earnings of about US$74.4 million from current earnings of US$192.3 million.
Uncover why Sally Beauty Holdings' fair value indicates a 7% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternative view on Sally Beauty Holdings leans heavily on the risk that Beauty Systems Group stays under pressure. The most bearish analysts already expected only 1.4% yearly revenue growth to about US$3.9b and earnings of roughly US$272.2 million by 2029. That is a stricter lens. The latest news could push these forecasts to shift again.
Explore 2 other Sally Beauty Holdings fair value estimates, including one that suggests as much as 7% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sally Beauty Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sally Beauty Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sally Beauty Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sally Beauty Holdings?
If you want to put Sally Beauty Holdings in context, it can help to scan a wider field of companies that share similar value, quality or income traits. The Simply Wall St Screener lets you filter for exactly the mix of valuation, balance sheet strength and dividend profile that fits your own approach.
- Prefer inflation beating income and payout consistency? Take a look at 7 dividend fortresses that may suit a yield focused portfolio.
- Care most about financial strength and resilience? Start with a list of solid balance sheet and fundamentals (25 results) so you can compare Sally Beauty Holdings with peers that have robust finances.
- Want something off the radar? Scan a 19 high quality undiscovered gems that pair underfollowed stories with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com