


EN
TeraWulf (WULF) Leans On HPC Leases, Is The Stock Fully Priced?
TeraWulf (WULF) just put high performance computing leases at the center of its story, as fresh third quarter earnings and Google backed data center deals reframed how investors view the stock.
The fresh Q3 story lands after a choppy year for TeraWulf, with the share price rallying 12.8% in the last session but still down 17.4% over 30 days and 10.8% year to date, while the 3 year total shareholder return of more than 10x signals powerful longer term momentum. Recent setbacks tied to regulatory questions in Texas, impairment charges and financing worries around large data center projects have now collided with Google backed lease support and a swing to quarterly profitability. This combination helps explain why short term weakness has started to give way to sharp moves higher as investors reassess both growth potential and execution risk.
Scan how other AI infrastructure plays compare to TeraWulf by reviewing 53 AI infrastructure stocks in the same corner of the market.
TeraWulf just ripped higher on the Google backed lease story, yet still carries a deep recent drawdown and a huge gap to analyst targets. Is that a window to step in now, or a setup to wait for a cleaner entry as the valuation section makes clear next?
Most Popular Narrative: 3% Undervalued
TeraWulf last closed at $11.37, while the most followed narrative on Simply Wall St, according to DanielOliveira, places fair value at $11.70. That tiny gap keeps attention fixed on whether huge high performance computing build outs actually start paying rent on the timetable the thesis assumes.
The line I care about more is CB-4. In August the company said the first CB-4 data hall had entered commissioning, with phased delivery and rent commencement expected in the second half of 2026, and CB-5 targeted to begin delivery in early 2027. Together that is 336 MW under construction, more than three times what is earning rent today. A clean Q3 with a later CB-4 date would be worse news than a small revenue miss with CB-4 on time.
See why 1 investors see TeraWulf as 3% undervalued.
Result: Fair Value of $11.70 (ABOUT RIGHT)
Still, the TeraWulf narrative leans heavily on CB-4 hitting its commissioning timeline and on the Anthropic and Google lease structure surviving without material changes.
Find out about the key risks to this TeraWulf narrative.
Another View: TeraWulf Looks Expensive On Sales
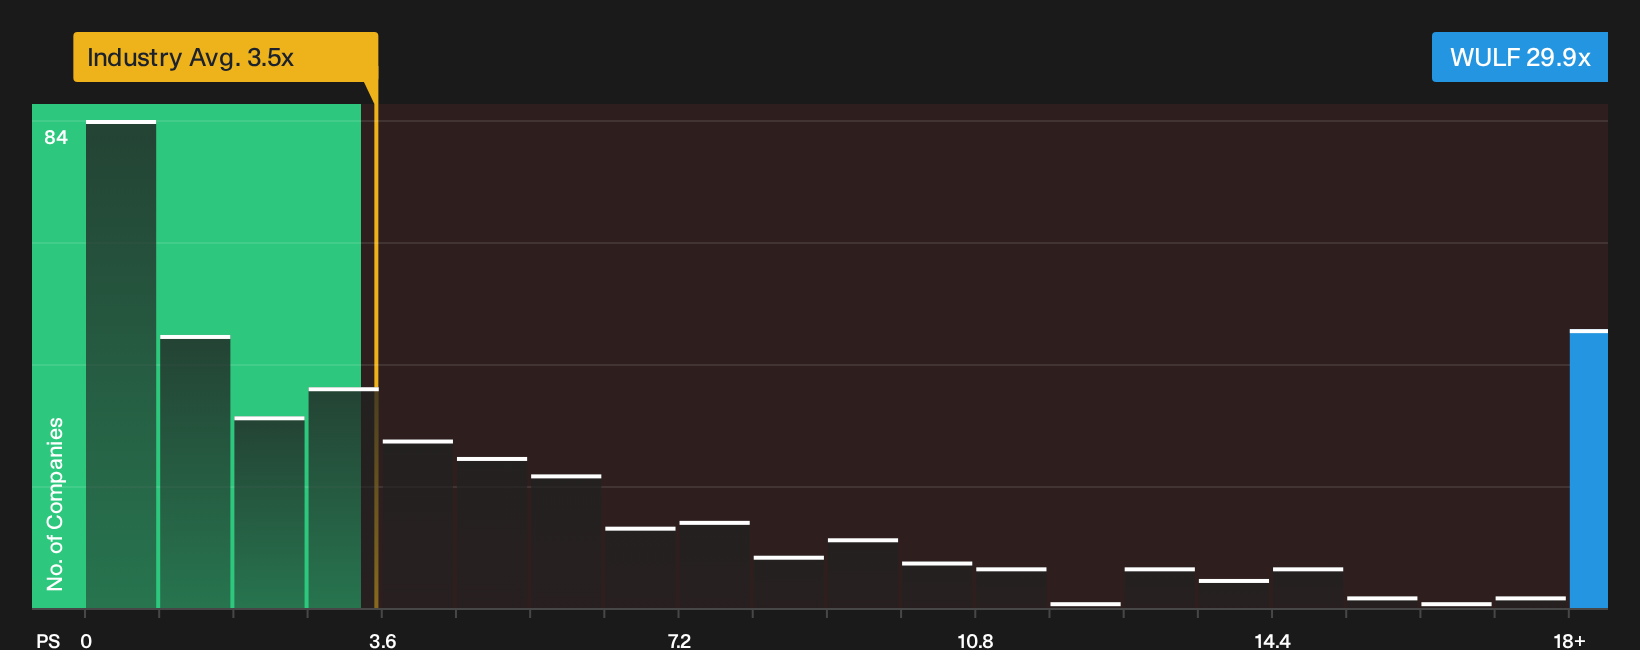
The $11.70 fair value from the Simply Wall St narrative presents TeraWulf as roughly in line with worth, yet the pricing on revenue tells a sharper story. The stock trades on a P/S of 29.9x, while the US Software group sits at 3.5x and the fair ratio is 15.5x.
This indicates that investors are paying almost eight times the industry average for each dollar of TeraWulf revenue, and close to double what the fair ratio suggests the market could move toward over time. For anyone weighing the Google and Anthropic leases against that kind of uplift, a key consideration is whether the growth case supports maintaining such a premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around valuation and execution risk can either freeze you on the sidelines or push you to act on incomplete information. Move quickly, review the underlying numbers, and ground your view in the full picture of TeraWulf's trade off between upside and threat signals by checking the 1 key reward and 4 important warning signs
Looking for more investment ideas beyond TeraWulf?
If TeraWulf has sharpened your focus on where capital could work hardest next, do not stop here. Broaden your watchlist with a few targeted screens that surface very different kinds of opportunities before the crowd catches on.
- Target potential mispricing by scanning a curated pool of companies that screen as quality yet out of favor through 38 high quality undervalued stocks.
- Explore more predictable cash flow potential by studying companies with robust payouts using the 7 dividend fortresses.
- Prioritize resilience when markets turn rough by filtering for sturdier balance sheets and fundamentals via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com