


EN
Tenable Holdings (TENB) Shares Dropped, So What Is Behind The Latest Attention?
Tenable Holdings (TENB) just delivered a swing to net income, raised its full year 2026 outlook, and announced an Atos partnership that spotlights demand for its AI-driven cyber exposure platform.
Tenable Holdings’ 1-day share price return fell 4.6% and the 7-day share price return is down 17%, yet the 90-day share price return of 14.8% and year to date share price return of 85.35% indicate momentum that has built over 2026. Over a longer horizon, the 1-year total shareholder return of 52.26% and 3-year total shareholder return of 12.62%, set against a 5-year total shareholder return decline of 22.61%, show how recent earnings results and the Atos deal have coincided with a shift in sentiment after a tougher early stretch as a public company.
Scan how Tenable Holdings fits alongside other security and AI infrastructure plays by reviewing the hand picked 53 AI infrastructure stocks shaping this part of the market.
Tenable Holdings just flipped to profit, raised its outlook, and still saw the share price pull back. Is that latest move pricing in the business, or is it simply sentiment catching its breath before valuation does the talking next?
Most Popular Narrative: 16% Overvalued
The most followed narrative pegs Tenable Holdings at a fair value of $36.45, which sits below the last close at $42.13, so the gap between price and implied worth is doing a lot of work in this story.
The analysts have a consensus price target of $36.45 for Tenable Holdings based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $1.3 billion, earnings will come to $68.4 million, and it would be trading on a PE ratio of 60.8x, assuming you use a discount rate of 8.8%.
See why 38 investors see Tenable Holdings as 16% overvalued.
Result: Fair Value of $36.45 (OVERVALUED)
Still, if Tenable Holdings stumbles on U.S. public sector contracts or faces sharper pricing pressure from bundled security platforms, this overvaluation story could unwind quickly.
Find out about the key risks to this Tenable Holdings narrative.
Another View: Tenable Holdings Through A Cash Flow Lens
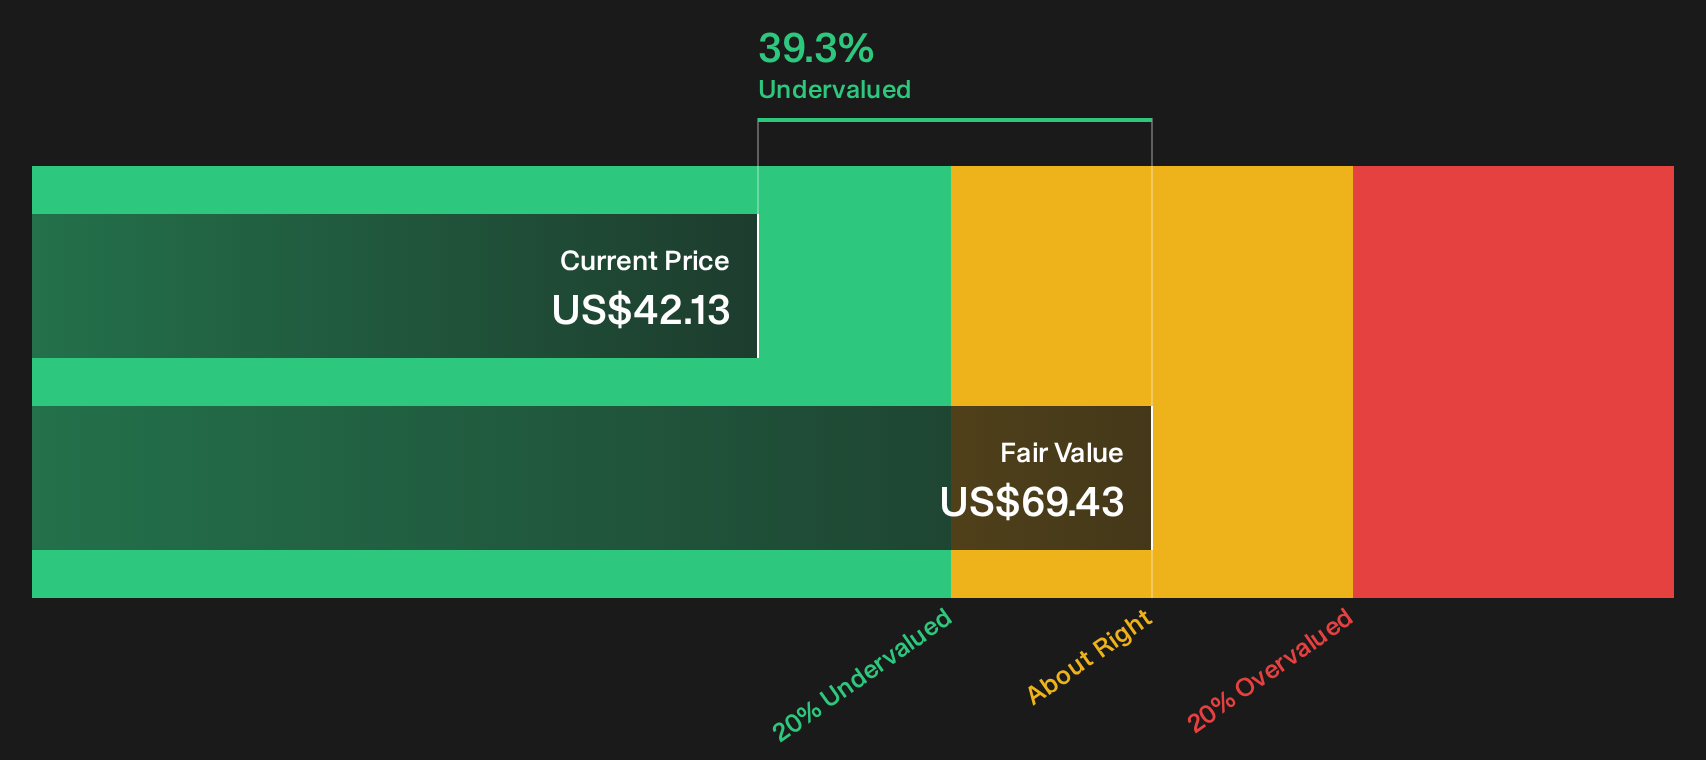
The analyst narrative frames Tenable Holdings as 16% overvalued at a fair value of $36.45, yet Simply Wall St's DCF model points the other way. On that measure, TENB at $42.13 trades about 39% below an estimated future cash flow value of $69.43. Which story do you trust more, the earnings multiple or the cash flow math?
Before leaning on either view, it is worth understanding how the SWS DCF model gets to that gap between price and estimated value, and what would need to change in Tenable Holdings' cash generation for that discount to shrink or widen from here. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Tenable Holdings can be energising or exhausting, so move fast, stress test the assumptions that matter, and ground your own thesis in our breakdown of 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Tenable Holdings?
If Tenable Holdings has sharpened your thinking, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities lining up today.
- Target potential mispricings by scanning a curated 38 high quality undervalued stocks that combines quality fundamentals with marked gaps between current prices and underlying business strength.
- Anchor your portfolio around income by reviewing a hand picked set of 7 dividend fortresses that pair higher yields with balance sheet support.
- Dial down portfolio stress by focusing on resilience first, starting with a 31 resilient stocks with low risk scores that screens for sturdier financial profiles and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com