


EN
Earnings Recovery Might Change The Case For Investing In MGM Resorts International (MGM)
- MGM Resorts International reported third quarter 2026 revenue of US$4.21b and a net loss of US$17.11 million, while nine-month results showed US$13.12b in revenue and net income of US$400.46 million.
- The swing from a nine-month net loss in the prior year to positive earnings, together with progress at the Osaka resort, highlights shifting profitability and execution on long-term projects.
- This article examines how MGM Resorts International's improving nine-month profitability may reshape the investment narrative built around global resort expansion.
Scan how MGM Resorts International’s earnings turnaround and Osaka expansion compare with other potential opportunities by zeroing in on our curated list of 38 high quality undervalued stocks to watch next.
MGM Resorts International Investment Narrative Recap
To own MGM Resorts International, you need to believe the resort, Macau and digital betting mix can translate steady top line performance into more consistent profits, while funding big projects like Osaka without stretching the balance sheet too far. The latest quarter still showed a small net loss, so the near term test is margin resilience rather than headline revenue shifts.
The key near term swing factor is whether self insurance costs, interest expense and any one off items stay contained enough for the recent nine month profitability to hold. The biggest risk remains high debt and interest coverage, which this quarter’s modest loss does not meaningfully change.
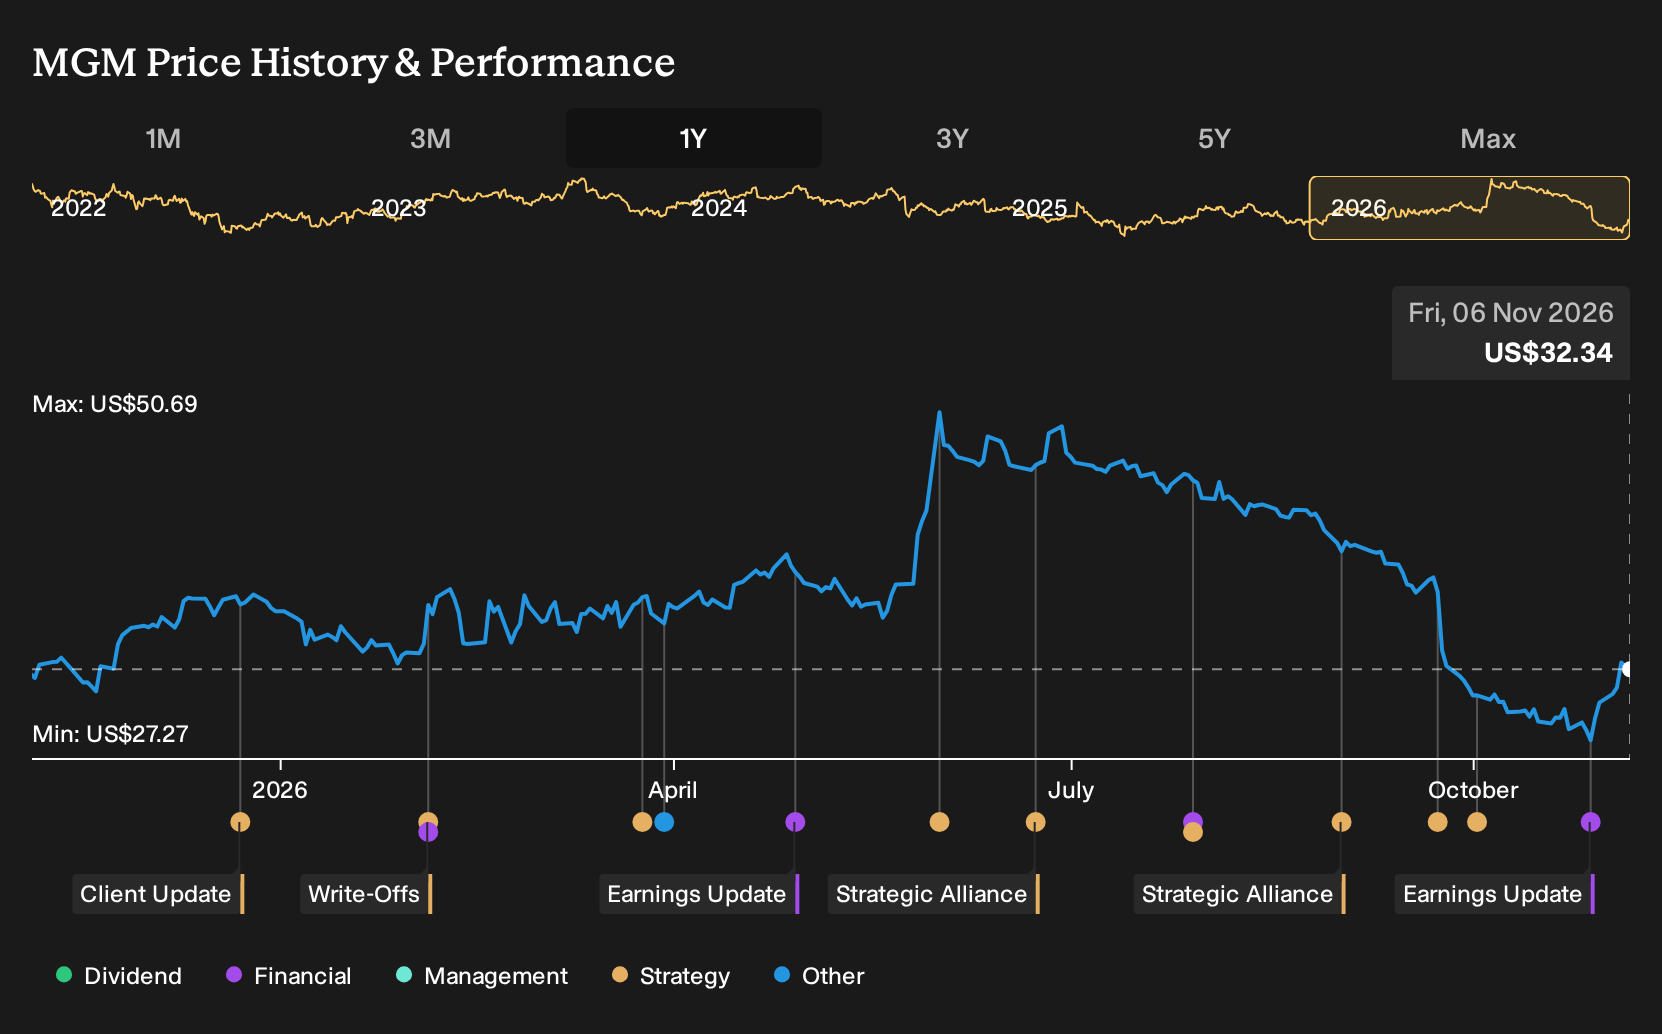
The most relevant piece of news is the third quarter and nine month 2026 earnings release. Revenue for the quarter was US$4.21b with a much smaller loss than last year, while the nine month period moved to net income of US$400.46 million. This indicates that MGM Resorts International is now showing profitability over a longer stretch, even if a single quarter is still in the red.
For catalysts such as Osaka and digital betting, this matters because major projects and product expansion require internally generated cash to support heavy funding needs and interest payments. If MGM Resorts International can keep nine month earnings positive while absorbing self insurance, legal and funding costs, it has more room to execute on Osaka and premium upgrades without amplifying financial risk.
MGM Resorts International's narrative projects US$19.3b revenue and US$340.0 million earnings by 2029. This assumes 2.8% yearly revenue growth and an earnings decline of about US$359.3 million from the current US$699.3 million level.
Uncover how MGM Resorts International's fair value indicates a 22% potential upside to its current price, which could narrow quickly if earnings execution keeps improving.
Exploring Other Perspectives
One alternative lens focuses on MGM Resorts International’s debt load rather than Osaka’s upside. The more optimistic analysts were already modeling revenue of about US$19.3b and earnings of roughly US$558.1 million by 2029. You can now weigh this quarter’s profit swing against those assumptions and decide whether that optimism still feels reasonable.
Explore 6 other MGM Resorts International fair value estimates, including one that suggests potential upside of as much as 102% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own analysis and going with your instincts.
- A great starting point for your MGM Resorts International research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for MGM Resorts International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MGM Resorts International's overall financial health at a glance.
Looking for more investment ideas beyond MGM Resorts International?
Once you have formed a view on MGM Resorts International, it can help to line it up against other potential opportunities using the Simply Wall St Screener. That way you see where its balance sheet, income profile and risk trade off sit compared with businesses in very different corners of the market.
- If you want to focus on financial strength, scan a list of solid balance sheet and fundamentals (25 results) and see which businesses pair resilience with cleaner leverage profiles.
- For investors who care most about valuation, compare MGM Resorts International with a curated 38 high quality undervalued stocks that combine quality metrics with pricing that may look appealing.
- If you prefer ideas that fly under the radar, broaden your watchlist with a 19 high quality undiscovered gems that already show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com