


EN
Will Bobsled Partnership Change Hexcel (HXL) Narrative
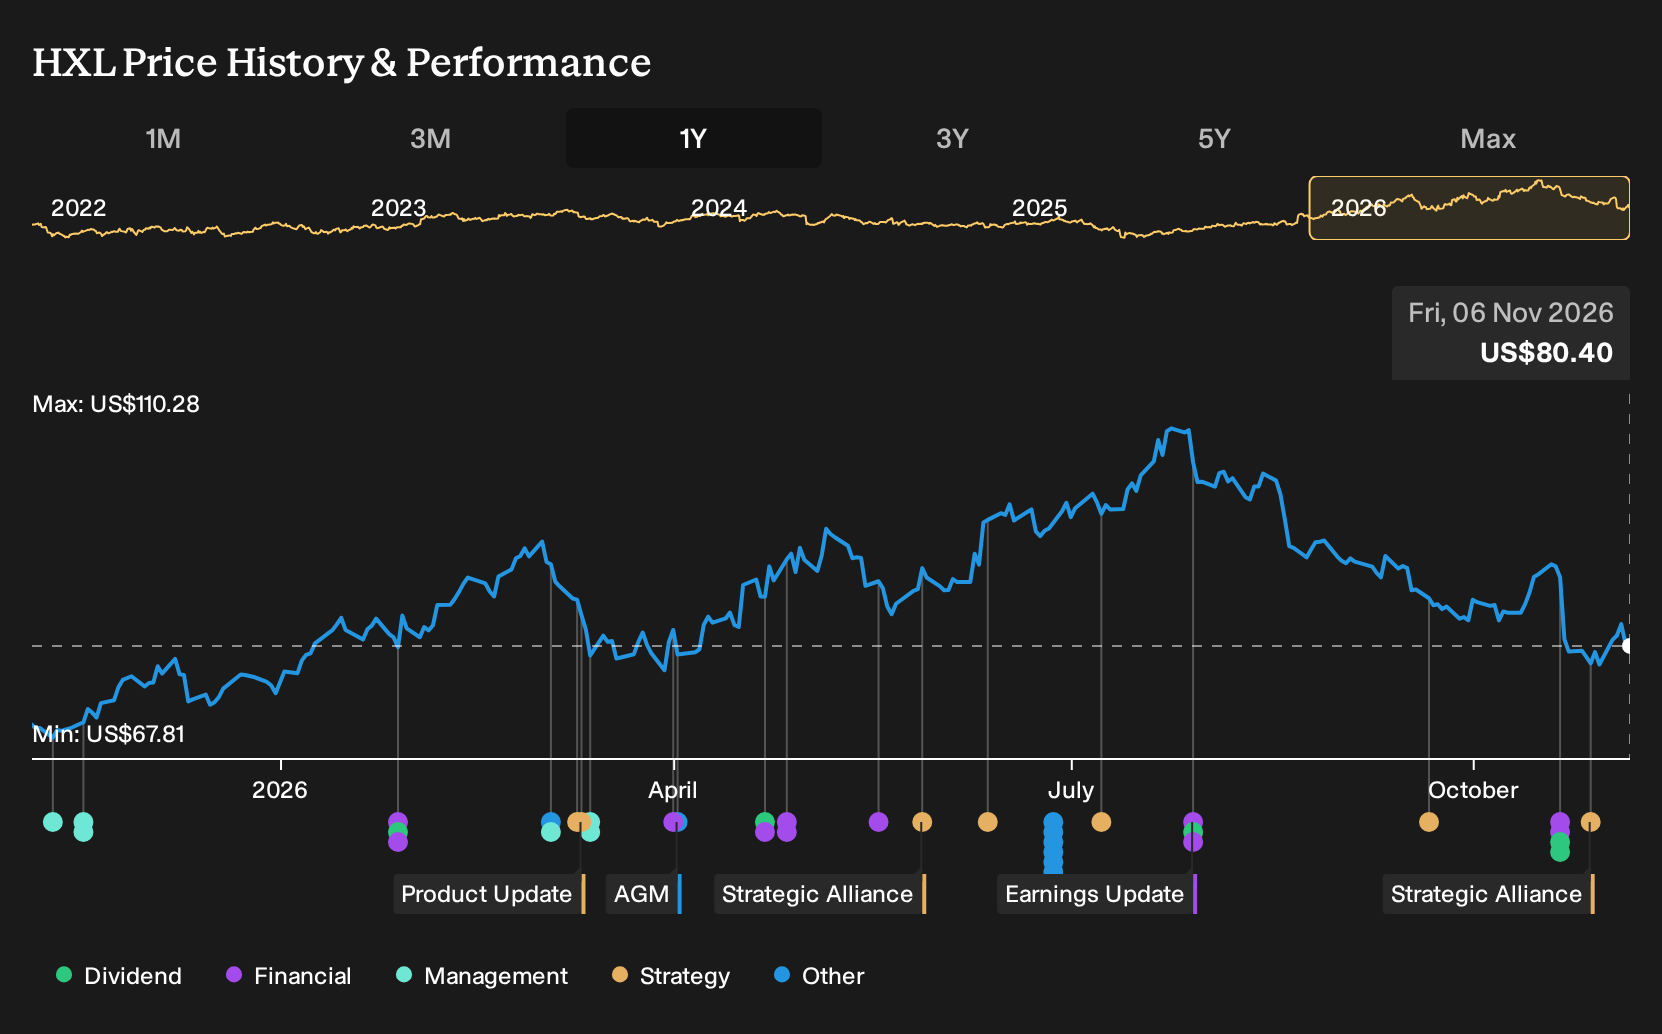
- On 28 October 2026, 47G announced a partnership with USA Bobsled/Skeleton, Albany Engineered Composites, Hexcel and Nammo Composite Solutions to apply advanced composite materials to next generation bobsled cowlings and sleds ahead of the 2034 Winter Olympics.
- The collaboration highlights Hexcel's composites know how being applied outside core aerospace and defense programs. This potentially broadens use cases while keeping the focus on demanding, performance critical applications.
- We will now examine how Hexcel's role supplying advanced composites for USA bobsled cowlings could influence its broader investment narrative.
Scan other composite heavyweights riding similar performance themes by checking out the 90 robotics and automation stocks that push advanced materials and precision engineering just as hard as Hexcel does here.
Hexcel Investment Narrative Recap
To own Hexcel, you need to be comfortable with a composites specialist that is tightly linked to long run aircraft build rates and defense programs, while working to lift margins from an 8.5% net level toward management’s longer term aspirations. The Utah bobsled partnership is high profile but operationally small, so it does not shift the near term earnings picture.
The key near term swing factor is how efficiently Hexcel converts roughly US$700 million of expected commercial and defense revenue uplift into higher operating margin, despite cost inflation and start up expenses from added headcount and a restarted carbon fiber line. The largest risk remains cost pressure on long dated Airbus contracts that already account for about 40% of sales.
The bobsled collaboration lines up most clearly with Hexcel’s push to show its composite materials work under extreme performance demands, similar to aircraft, missiles and unmanned systems. That message ties back to the stated goal of using largely existing capacity, while keeping annual capex under US$100 million, to reach about 18% operating margin and roughly 25% EBITDA margin by the end of the decade.
For you as an investor, the interesting angle is how this project reinforces Hexcel’s pitch on technical capability just as analysts expect earnings to grow 21.6% per year and return on equity to reach 23.2% in three years. Validation in a visible Olympic setting may help management when securing or repricing long term agreements, which links directly to the margin and cash flow story already embedded in current expectations.
Hexcel's current analyst narrative points to revenues of US$2.7b and earnings of US$360.1 million by 2029, based on an assumed 10.0% yearly revenue growth rate and an earnings increase of about US$188.6 million from US$171.5 million today.
Uncover how Hexcel's fair value indicates a 23% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternative angle focuses on Hexcel’s potential revenue trajectory rather than contract headwinds. The most optimistic analysts were already penciling in about US$3.0b of sales and US$435.7 million in earnings by 2029 before this bobsled alliance. You can now ask whether this Olympic stage pushes forecasts higher, lower, or just differently skewed.
Explore 2 other Hexcel fair value estimates, including one that suggests potential upside of as much as 58% from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hexcel research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hexcel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hexcel's overall financial health at a glance.
Looking For More Ideas Beyond Hexcel?
Hexcel might be central to your thesis today, but your portfolio is built on the mix of opportunities you line up next. The Simply Wall St Screener can help you filter that wider universe into a shortlist that actually fits your risk appetite and return goals.
- If you want potential bargains with quality fundamentals, scan for companies on the 38 high quality undervalued stocks that match your preferred mix of cash flows and balance sheet strength.
- For steadier income potential, focus on businesses in the 7 dividend fortresses that pair higher yields with more durable payout profiles.
- When capital preservation matters more than chasing every rally, narrow your search to companies in the 31 resilient stocks with low risk scores and see which ones align with your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com