


EN
3 Utility Stocks With Predictable Cash Flows as Bond Proxy Picks
While French unrest and heavy debt loads in Europe have pulled markets back to the basics of funding risk and social stability, U.S. Treasuries have quietly reclaimed their role as a relative safe haven, drawing fresh attention to equities that behave more like bond proxies than high-octane growth bets. Investors hunting steadier cash flows do not want to watch this from the sidelines. This article explains how that backdrop relates to our government and high quality bond proxy screener and walks through three stocks that appear well positioned on the positive side of this story.
The stocks covered below are just a sample of this idea. The full screen surfaced 15 more large caps with equally compelling, income-oriented narratives that are not included in this article. To identify and analyze those potential higher conviction bond proxy candidates directly, head into the U.S. Investment‑Grade Government and High‑Quality Bond Proxies screener.
ONE Gas (OGS)
ONE Gas fits the government and high quality bond proxy theme neatly, offering regulated natural gas distribution that aims to turn essential service demand into steadier cash flows at a time when many investors are searching for income that feels closer to utilitylike predictability.
ONE Gas operates a regulated natural gas distribution utility serving about 2.3 million customers across Oklahoma, Kansas, and Texas, generating around US$2.3b in regulated public utilities revenue and carrying a market value near US$5.1b. This positioning aligns it naturally with this income oriented, lower volatility screener theme.
"Favorable regulatory frameworks in Texas, Kansas, and Oklahoma, including mechanisms that defer depreciation, allow carrying costs on capital, and expand surcharge eligibility, are expected to support more predictable revenue recovery and help ONE Gas translate its multi year capital program into steadier earnings."
The real test for ONE Gas is how that supportive backdrop interacts with one persistent cost and funding pressure that could quietly reshape margins.
If that pressure matters to you, read the full narrative for ONE Gas to see how ONE Gas balances funding costs, capital plans and income resilience.

California Water Service Group (CWT)
California Water Service Group fits neatly into the bond proxy theme because it runs regulated water and wastewater utilities that aim to exchange essential service demand for steadier cash flows. This can appeal when you want equity income to feel closer to a high quality defensive holding.
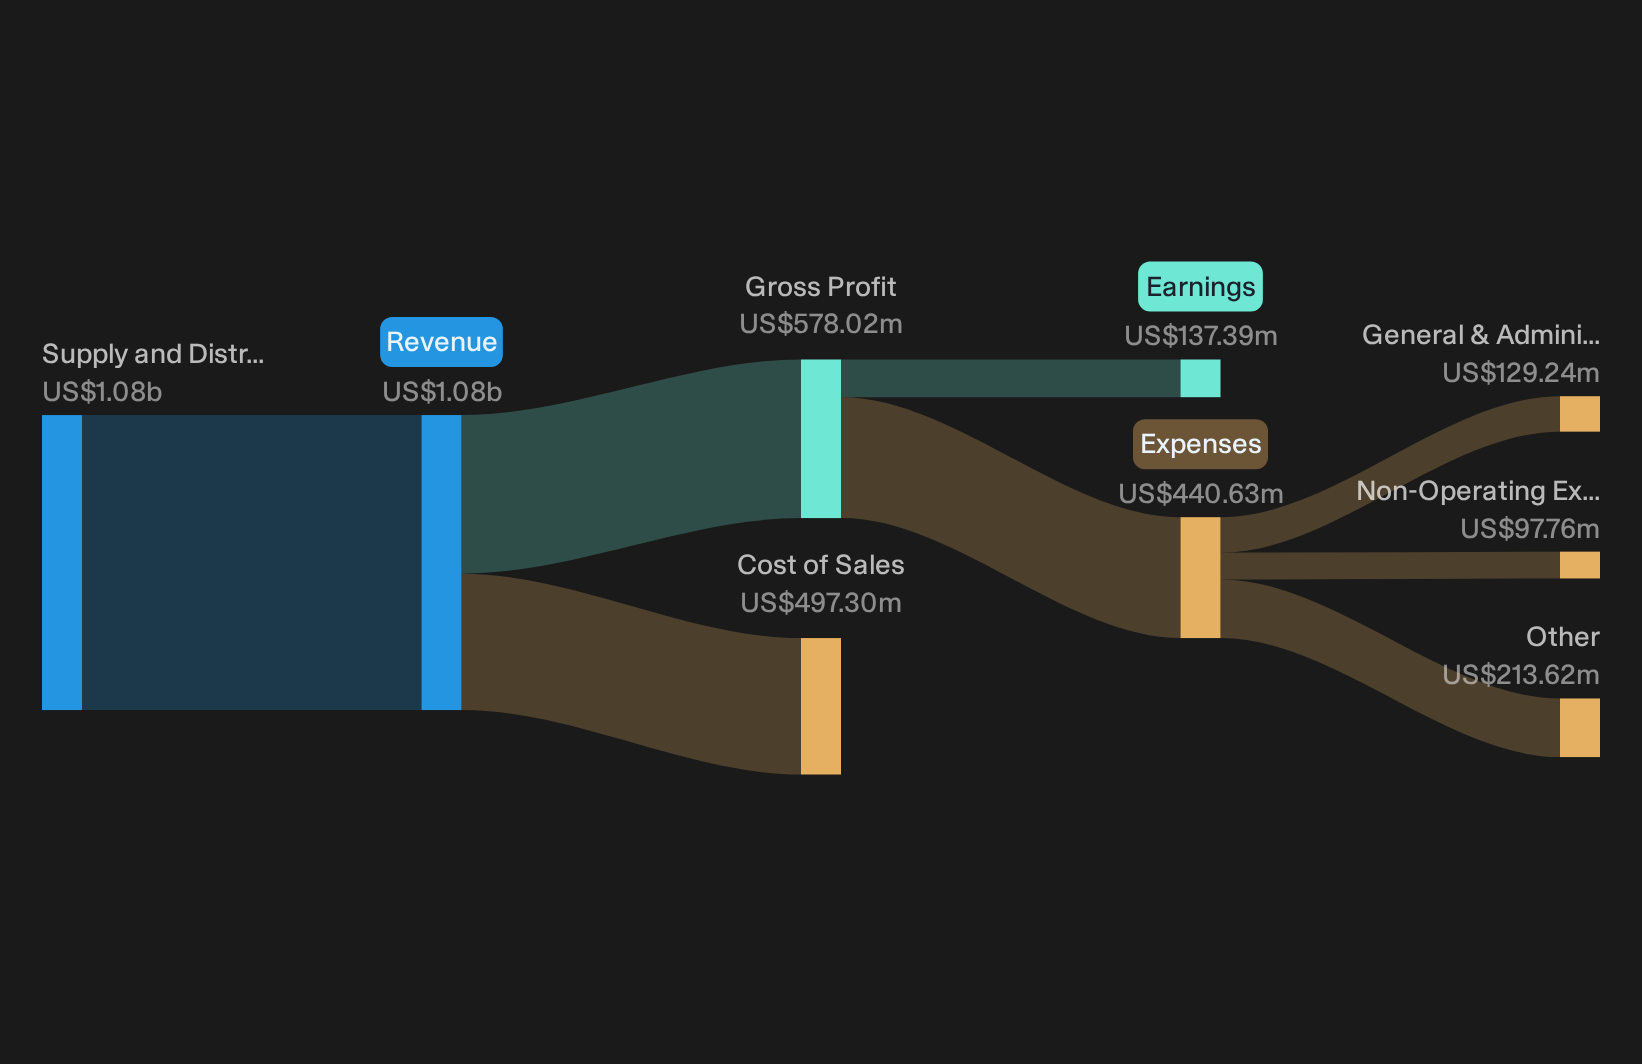
California Water Service Group provides regulated and non regulated water and wastewater services across several U.S. states, earning about US$1.1b from supplying and distributing water and related utility services, and carries a market value of roughly US$3.2b.
"Accelerating capital investment in water infrastructure and modernization is now backed by a roughly 11% 10 year growth capital CAGR, and by management expectations for nearly 12% rate base CAGR to around US$3.5b by 2028."
What happens to the dividend profile and cash flow comfort depends heavily on how one unresolved cost recovery pressure plays out.
That cost recovery question is where things get interesting, so read the full narrative for California Water Service Group to see how California Water Service Group balances investment, rates, and income resilience.
Sempra (SRE)
Sempra gives this bond proxy screen a large cap anchor, combining regulated utilities in California and Texas with energy infrastructure that aims to turn essential service demand into steadier cash flows when investors want something closer to a utility backed income stream.
Sempra runs electric and gas utilities plus energy infrastructure, generating about US$11.8b from Sempra California and US$1.9b from Sempra Infrastructure, with minor intersegment eliminations, and carries a market value near US$51.1b, which fits the large cap, defensive profile of this screener.
"Strong demand growth in Texas, including large load requests under the Batch Zero process that equate to about 140% of Oncor's current peak load and are backed by over US$2b of customer collateral, supports the view that Sempra's multi decade grid buildout plan can continue to expand regulated rate base and future revenues."
What really shapes Sempra’s bond like appeal is how one core regulatory and funding assumption ultimately feeds through to margins and long term earnings resilience.
If that assumption is what you care about, read the full narrative for Sempra to see how Sempra's regulatory bets could be masking both risk and upside potential.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not wait. Momentum can build quietly, then prices move fast and the best entry window is gone before the crowd notices. Scan these ideas and act now.
- Spot income workhorses with resilient cash profiles by running the 7 dividend fortresses before yields tighten and the strongest payers get repriced by income hungry investors.
- Track the next wave of AI infrastructure demand by scanning the 53 AI infrastructure stocks while these backbone providers are still building momentum under the radar for now.
- Capitalize on renewed interest in hard assets by checking the 34 elite gold producer stocks before renewed macro headlines pull more investors into the same narrow group of producers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com