


EN
Entegris (ENTG) On Kioxia Deal And Fresh Guidance Looks Undervalued
Entegris (ENTG) is back in focus after two key developments: an expanded collaboration with Kioxia on materials for future BiCS FLASH memory and fresh quarterly results with new guidance.
Recent trading in Entegris reflects that mix of excitement and nerves. The share price has climbed strongly this year, with a year to date share price return of 42.9%. However, it has pulled back sharply, with a 7 day share price return of down 17.1% and a 30 day share price return of down 22.8% as investors digest the Kioxia partnership, robust quarterly figures and new guidance. The 1 year total shareholder return of 48.1% signals that longer term holders have still seen meaningful gains even as near term momentum has cooled.
Scan how Entegris fits alongside peers by comparing it with a curated set of 53 AI infrastructure stocks that benefit from chipmaking, memory and AI-driven manufacturing demand.
After a 22.8% pullback over 30 days, Entegris now trades about 32% below the average analyst price target while sitting above one intrinsic estimate. Is this a bargain being misread, or caution that fits the numbers?
Most Popular Narrative: 32% Undervalued
On the most followed view, Entegris screens as undervalued, with a fair value of $189.07 against a last close of $127.98, and that gap is built on relatively strong growth and margin assumptions that investors need to weigh carefully.
Rising AI related demand for advanced logic, HBM, DRAM and higher layer NAND is increasing Entegris’ materials and filtration content per wafer. This trend is already visible in double digit growth in liquid filtration, CMP pads, advanced deposition materials and selective etch chemistries, which can support further revenue and gross margin expansion as these nodes scale.
See why 13 investors see Entegris as 32% undervalued.
Result: Fair Value of $189.07 (UNDERVALUED)
Still, the Entegris story can break if sector sentiment turns and high P/E expectations meet flatter revenue trends or renewed volatility around AI related spending.
Find out about the key risks to this Entegris narrative.
Another Angle On Entegris Valuation
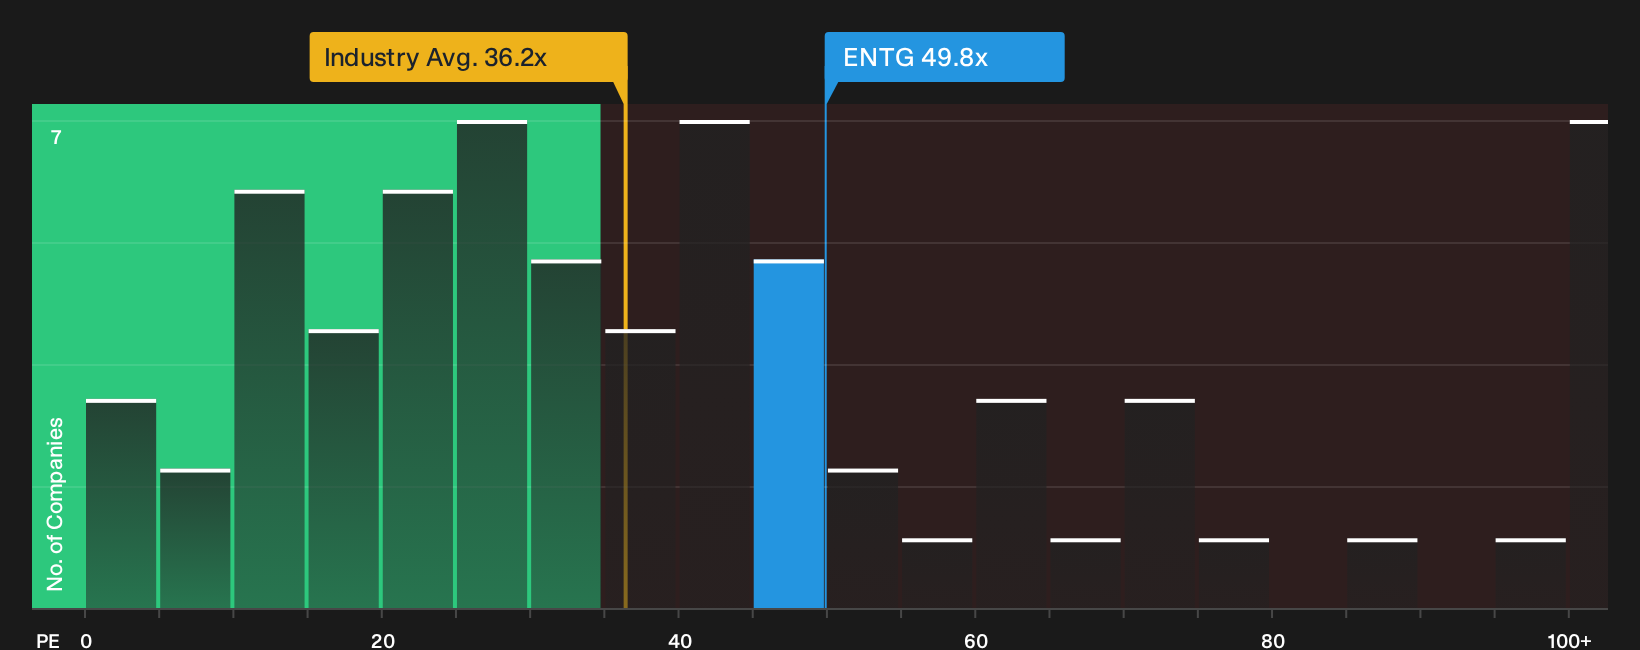
The P/E view already looks demanding for Entegris. The stock trades on roughly 49.8x earnings, compared with about 36.2x for the US semiconductor group and a fair ratio estimate of 32.5x. That is a big gap, so this premium may be a cushion for some investors or a source of valuation risk for others.
To see how firmly the current price lines up with earnings power over time, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Entegris can feel confusing, yet that tension is exactly why it pays to look under the hood yourself and act promptly. Weigh the potential benefits and risks by checking the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Entegris?
If you stop with Entegris, you only see part of the opportunity set. Cast the net wider and let structured screeners surface ideas you might otherwise miss.
- Target potential mispricing by scanning a curated 38 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them.
- Strengthen portfolio resilience by filtering for a list of solid balance sheet and fundamentals (25 results) that can better handle tough conditions and still stay financially flexible.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems that pair quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com