


EN
How Investors May Respond To Engie (ENXTPA:ENGI) Upper End Guidance
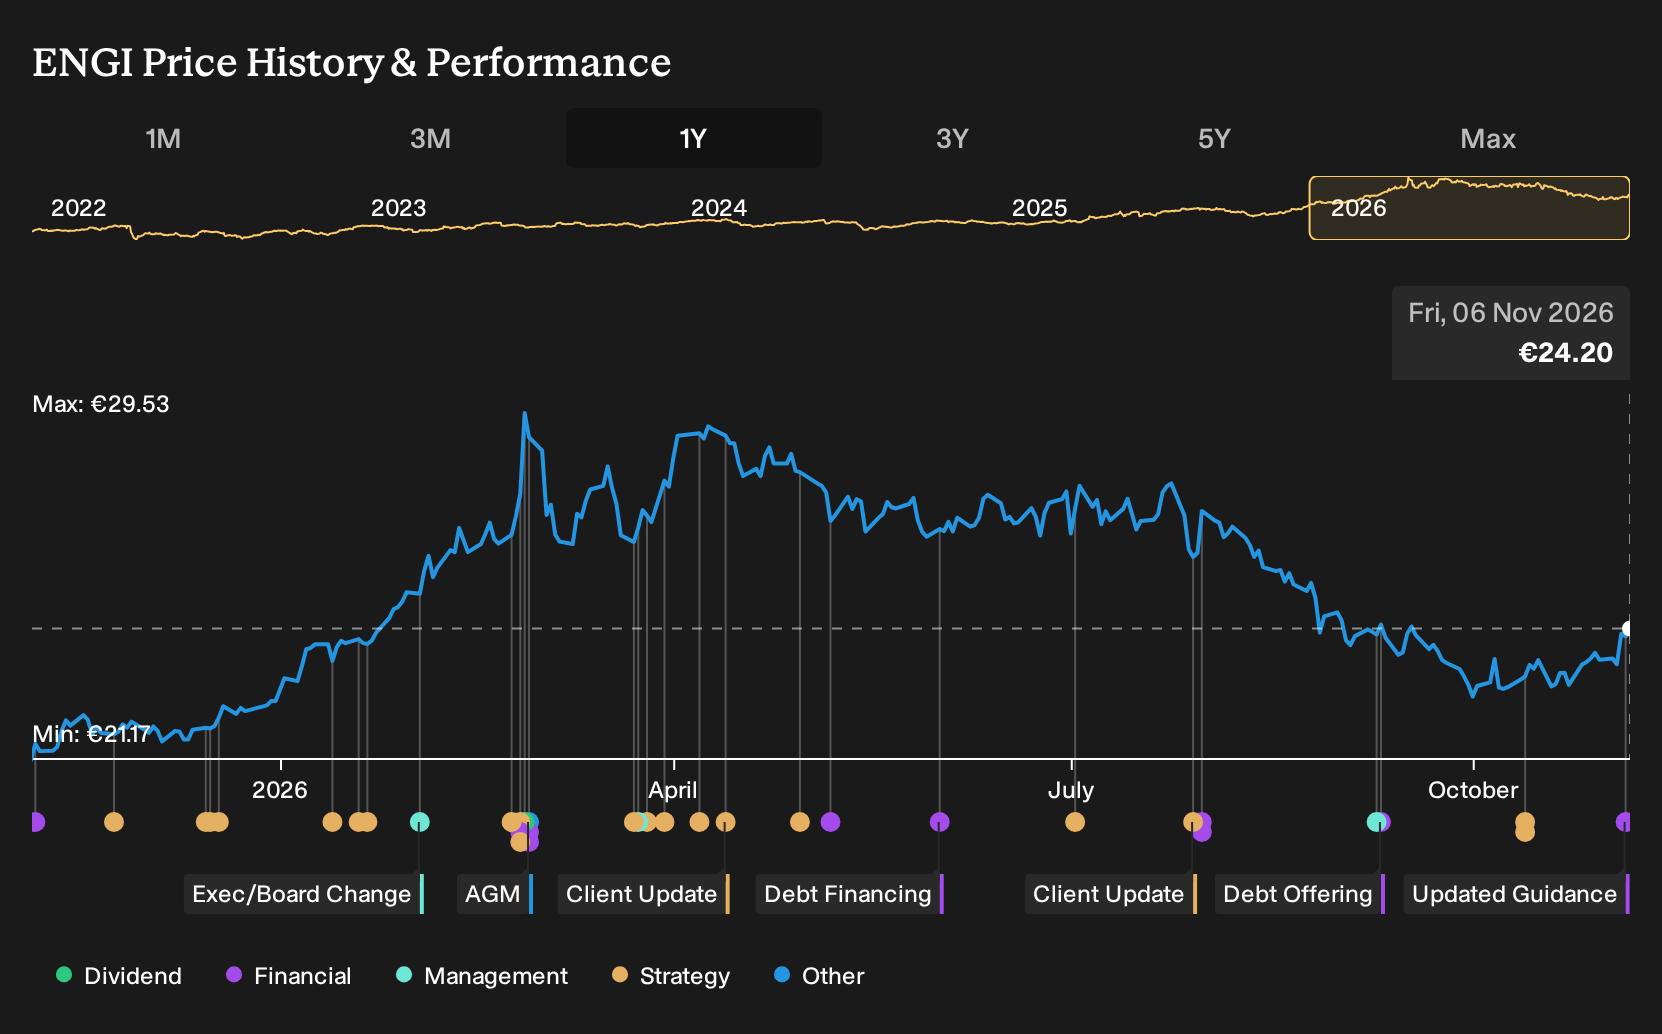
- Engie announced that for the first nine months of 2026, Net Recurring Income Group share and EBIT excluding nuclear are now expected near the upper end of prior guidance ranges of €4.9b to €5.5b and €9.2b to €10.2b respectively.
- This shift toward the top of guidance indicates that Engie’s operational engine, from regulated networks to renewables and storage, is tracking ahead of the earlier internal expectations embedded in those ranges.
- We will now look at how Engie’s investment narrative could be reshaped by the higher 2026 earnings guidance toward the top of the range.
Scan how Engie’s updated guidance compares with peers by reviewing the hand picked 225 high quality undervalued stocks, which combines earnings power with balance sheet support.
Engie Investment Narrative Recap
To own Engie, you need to believe its mix of regulated networks, renewables and storage can turn a large, complex group into a steadier earnings machine. The guidance shift toward the upper end of 2026 ranges supports that view in the near term. The key short term catalyst remains operational delivery from these assets as they move from build to full contribution.
The biggest risk still sits on the balance sheet. Economic net debt of about €60b and leverage of 4.2x EBITDA leave less room for disappointment if the planned uplift from UK Power Networks and renewables underwhelms. The updated guidance does not remove that concern. It just gives Engie a little more benefit of the doubt.
The UK Power Networks acquisition is the announcement that matters most relative to this guidance update. Management flagged a March 2025 regulated asset value of £9.2b and an expected 2026 EBIT contribution of €0.6b to €0.8b. For anyone tracking Engie, the new guidance near the top of the range effectively tests whether that earnings contribution is coming through as planned.
If those regulated electricity activities keep doing the heavy lifting, they can help offset pressure in Renewables and Flex Power, where EBIT fell 5% organically in H1 2026 on weaker European capture prices and lower hydro volumes and spreads. Your call as an investor is whether execution on UK Power Networks and other regulated assets is sufficient to stabilise Engie’s overall earnings mix while renewables pricing remains under pressure.
What The Long Term Analyst Numbers Assume For Engie
Analysts sketch a long term picture for Engie that links the upgraded 2026 guidance with a later step up in earnings power by 2029. The key ingredients sit in the revenue growth, margin shift and the earnings bridge from today to the forecast period, all of which investors can pressure test against their own view of regulated networks, renewables delivery and balance sheet risk.
Consensus assumptions point to Engie's revenue rising by 8.5% a year over the next three years, with profit margins moving from 5.8% today to 6.2% by 2029. Current earnings are put at about €4.1b, with analysts expecting this to reach €5.6b in 2029, and the more optimistic forecasts going up to €6.3b. In plain terms, the base case calls for earnings to grow by roughly €1.5b from today, which is a meaningful uplift that leans on UK Power Networks integration, regulated grid expansion and renewables projects reaching full run rate.
Valuation work in the consensus takes those 2029 numbers and applies a higher P/E multiple than today. The group would need to be trading around 17.9x on the €5.6b earnings figure, compared with a current P/E of 13.6x and an industry level quoted at 15.8x for GB Integrated Utilities. On these inputs, revenues in 2029 would be €90.2b with earnings of €5.6b, and analysts apply a discount rate of roughly 6.6% to link that outcome back to today. For readers, the key question is whether that combination of higher profits, modestly better margins and a richer multiple feels realistic given Engie's leverage and the mix between regulated assets and more volatile power markets.
Engie's narrative projects €90.2b revenue and €5.6b earnings by 2029. This setup assumes 8.5% yearly revenue growth and an earnings increase of about €1.5b from current earnings of roughly €4.1b.
Uncover how Engie's fair value indicates a 26% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One more upbeat angle on Engie puts the nuclear exit and balance sheet capacity at center stage. The most optimistic analysts were already sketching €117.6b of revenue and €6.3b of earnings by 2029 before this guidance news. You can treat today’s shift as a fresh test of those bolder assumptions and consider where you position yourself within that range.
Explore 3 other Engie fair value estimates, including one that suggests as much as 26% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Engie research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Engie. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Engie's overall financial health at a glance.
Looking for more investment ideas beyond Engie?
If Engie has sharpened your interest in regulated assets and earnings quality, it can help to line it up against other opportunities that match different risk and income profiles using the Simply Wall St Screener.
- For investors who want resilience first and volatility second, start with a 207 resilient stocks with low risk scores that filters for businesses scoring well on risk metrics.
- If balance sheet strength is non negotiable for you, scan the list of solid balance sheet and fundamentals (192 results) and focus on companies with funding profiles that help support their fundamentals.
- Income focused readers who care about dependable cash returns can review a 228 dividend fortresses and see which stocks currently pair higher yields with underlying stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com