


EN
Should Services And Wealth Growth Require Action From Citi (C) Investors?
- Citigroup has recently issued a series of senior unsecured callable notes across multiple maturities, including zero coupon paper due 2056 and fixed rate bonds ranging from 5.30% to 6.70%, alongside changes in its equities leadership team.
- The fresh fixed income issuance sits alongside Services and Wealth Management earnings engines, highlighting how Citigroup is pairing funding activity with fee based and interest driven business lines.
- The focus now is on how Citigroup's Services and Wealth performance might reshape its investment narrative.
Scan how Citigroup's latest funding moves compare to peers by reviewing a curated list of solid balance sheet and fundamentals (25 results) that are also leaning on fee income and interest driven businesses.
Citigroup Investment Narrative Recap
An investor in Citigroup needs to believe the bank can keep turning its global Services and Wealth engines into consistent returns, while using technology and simplification to protect margins. The recent wave of callable fixed income issuance, including long dated zero coupon notes, appears more like routine balance sheet management than a major shift in the near term story.
The more immediate swing factor still sits in how Services revenue, digital payments and AI efficiency work together with capital returns to support earnings quality. The biggest risk remains a regulatory or conduct setback, or rising competition in cross border payments that eats into the fee pool Citigroup depends on.
The most relevant fresh data point is the cluster of new senior unsecured callable notes, with coupons ranging from 5.30% to 6.70% and maturities out to 2046, plus the zero coupon notes due 2056. This mix extends Citigroup’s funding curve and provides flexibility around when to call and refinance, which is important for an asset sensitive balance sheet.
For you as a shareholder, that funding profile feeds directly into how Citigroup can support Services growth, Wealth expansion and its capital return plans while managing higher regulatory capital needs and deposit costs. Execution risk lies in keeping funding stable and efficient so that the potential benefits from AI, tokenization and the planned Banamex IPO are not diluted by higher interest expense.
Citigroup's narrative projects US$108.8b revenue and US$22.4b earnings by 2029. That profile assumes 9.3% yearly revenue growth and an earnings increase of about US$4.5b from the current US$17.9b base.
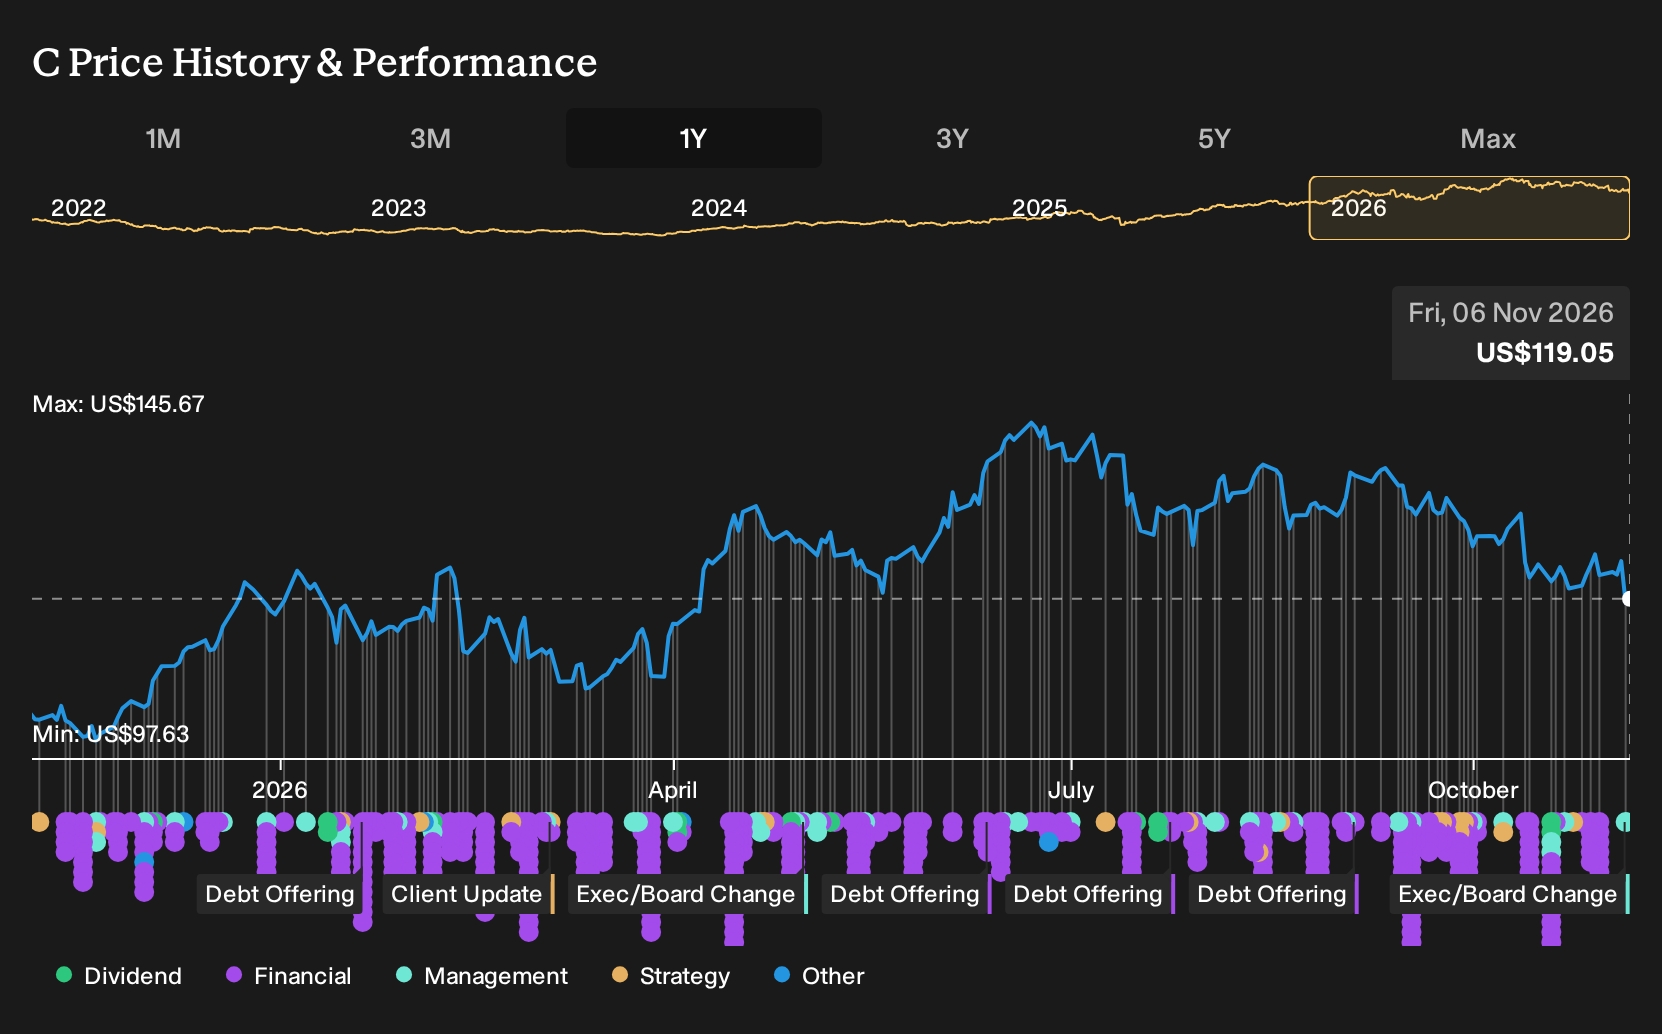
Discover how Citigroup's fair value indicates a 27% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on new bond issuance and more on Citigroup’s simplification plans. They were already assuming revenue of about US$112.8b and earnings of US$25.2b by 2029, well above the consensus US$108.8b and US$22.4b. Those views were formed before this funding news, so you may see opinions shift as fresh information lands.
Explore 4 other Citigroup fair value estimates, including one that suggests as much as 69% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Citigroup research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Citigroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Citigroup's overall financial health at a glance.
Looking for more Citigroup sized investment ideas?
If the Citigroup story has sharpened your thinking but you want to pressure test your approach across a wider watchlist, the Simply Wall St Screener can help you quickly surface companies that fit very different risk and return profiles.
- For investors hunting for potential mispricings, use the 38 high quality undervalued stocks as a starting pool to stress test against your own valuation work.
- If capital preservation matters just as much as upside, focus on resilience first and scan a curated 31 resilient stocks with low risk scores to see which businesses clear your risk bar.
- When you want staying power and robust finances, broaden your research beyond Citigroup by running through a list of solid balance sheet and fundamentals (25 results) that can support long term compounding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com