


EN
Did Earnings Jump Just Shift UDR's (UDR) Investment Narrative?
- UDR reported third quarter 2026 revenue of US$428.08 million and net income of US$216.09 million, with diluted earnings per share from continuing operations of US$0.67. The company also reported nine month 2026 net income of US$474.96 million and diluted earnings per share from continuing operations of US$1.45.
- Profitability for UDR moved in a different direction to top line activity, with net income and earnings per share rising despite relatively flat sales and revenue over both the quarter and the first nine months of 2026.
- The next step is to consider how UDR's investment narrative is influenced by this sharp net income increase alongside largely unchanged revenue.
Compare UDR's sharp earnings jump on steady revenue with peers by scanning our hand picked list of 38 high quality undervalued stocks that are also pairing strong fundamentals with disciplined balance sheets.
UDR Investment Narrative Recap
To own UDR, you need to be comfortable with a story built around stable apartment demand, data driven operations and disciplined capital recycling rather than fast revenue expansion. The sharp swing in net income and earnings per share on broadly steady sales underscores how much current results depend on non recurring items and margin behaviour, not top line growth.
In the near term, the key swing factor is how effectively UDR manages pressure in Sunbelt rents while keeping occupancy and resident retention resilient. The biggest risk remains that elevated supply and regulatory or legal headwinds compress same store revenue and net operating income, making recent earnings power hard to repeat.
The latest quarterly report is the most relevant update to that thesis. Management reported third quarter 2026 revenue of US$428.08 million and net income of US$216.09 million, with diluted earnings per share from continuing operations of US$0.67. For the first nine months, revenue was US$1.28b and net income reached US$474.96 million, with diluted earnings per share of US$1.45.
These figures sit alongside prior commentary that Sunbelt lease rates have been under pressure and that interest costs are not comfortably covered by earnings. For readers tracking catalysts, the question is whether UDR can keep extracting efficiency and fee income while cycling past large one off gains, funding dividends of 4.76% and reallocating capital without letting earnings drift toward the declines analysts have flagged.
UDR's narrative projects US$1.8b revenue and US$182.4 million earnings by 2029. This rests on 1.0% yearly revenue growth and an earnings decline of about US$334.9 million from US$517.3 million today.
Uncover why UDR's fair value indicates an 8% potential upside to its current price that could narrow quickly.
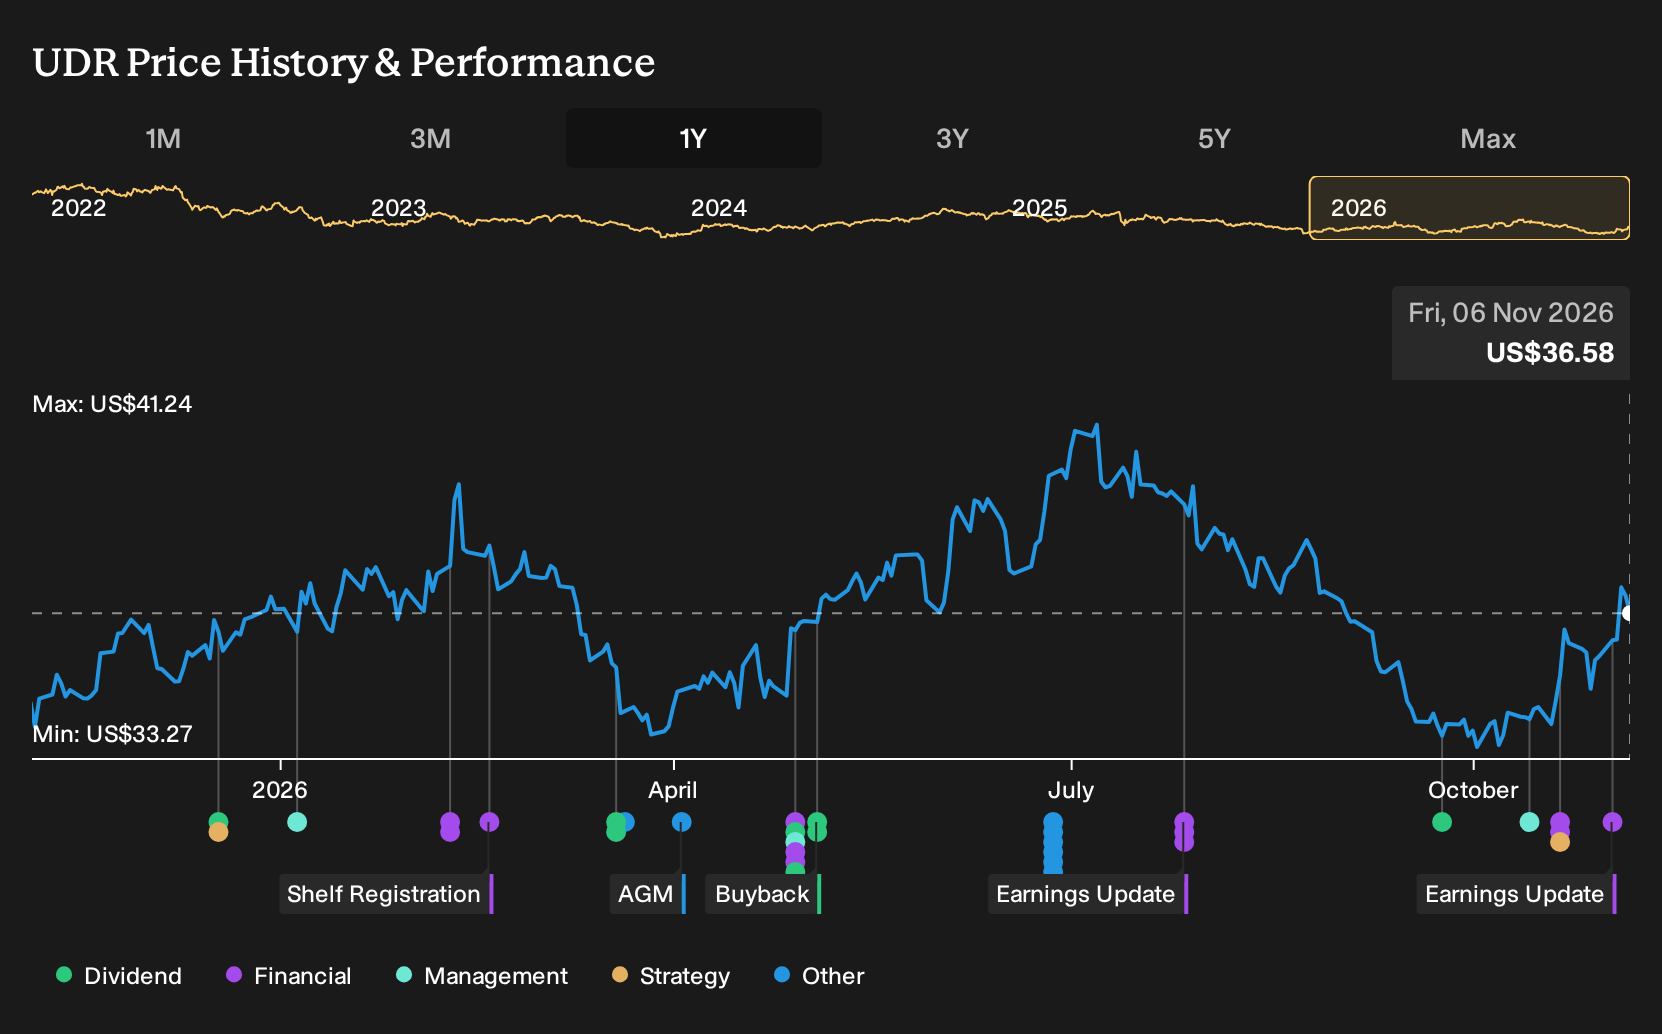
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$39.64 to US$59.05, which is a wide band for a single REIT like UDR. That spread reflects real business tension around Sunbelt rent pressure, regulatory cases and capital recycling. Use these contrasting opinions to test your own UDR thesis.
Explore another UDR fair value estimate, including one that suggests it could be worth just $39.64.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your UDR research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for UDR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UDR's overall financial health at a glance.
Looking for more investment ideas beyond UDR?
Once you have a view on UDR, it often helps to widen the lens and see how other businesses stack up on value, income and balance sheet strength. The Simply Wall St Screener lets you do that quickly by filtering stocks using the same data driven framework used throughout this analysis.
- For investors who want potential value combined with quality fundamentals, scan a curated group of 38 high quality undervalued stocks and see which businesses fit your return and risk preferences.
- If reliable income is a priority, focus on companies that aim to support regular payouts by reviewing a targeted set of 7 dividend fortresses and assess whether their yields and coverage look sustainable to you.
- When capital preservation matters most, narrow your search to financially resilient businesses by using the 31 resilient stocks with low risk scores and compare how their balance sheets and risk scores align with your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com