


EN
What Vodafone Idea Shareholders Got Right
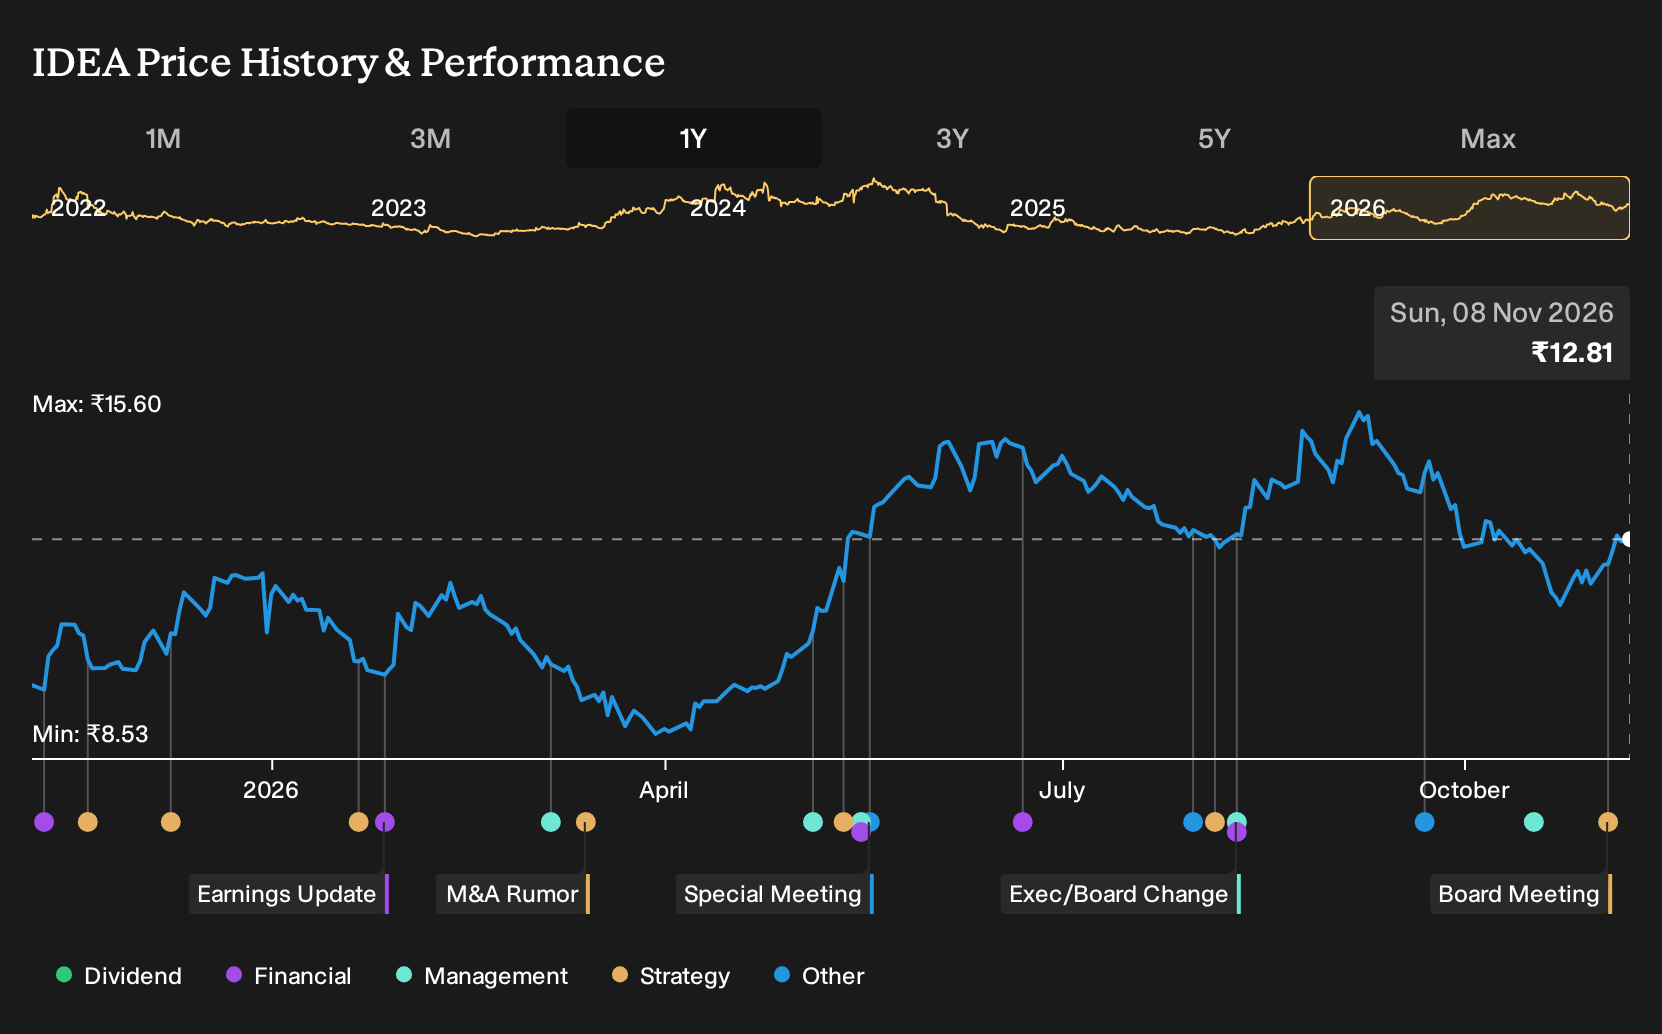
Investors who held Vodafone Idea over the past year are up 33.3%, including dividends. That outcome looks straightforward on a chart, but the decision on 8 November 2025 was not. If you had put money in then, you would have been weighing bullish arguments about 5G rollouts and digital services against warnings on heavy debt, funding risk, and subscriber churn. Which of those pressure points felt more convincing at the time?
The easy part of this move is behind Vodafone Idea. Zero in on 225 high quality undervalued stocks for companies trading below our estimates.
The Two Vodafone Idea Stories Investors Were Choosing Between
The shares cost ₹9.61 at the start of the period, and Vodafone Idea sat between two very different but plausible stories about where 5G and digital expansion might lead.
The bullish camp argued that rapid 4G and 5G rollouts plus a richer Vi App ecosystem could reshape the business. Their Fair Value was ₹15.3, a price they felt matched a scenario where subscriber gains, digital services and enterprise contracts supported stronger earnings.
The cautious view still saw 5G and digital services helping but focused more on heavy borrowings and funding delays. This group worked with a Fair Value of ₹7.11 and treated the assumed shift from very deep losses toward a 17.9% profit margin as a fragile outcome if debt and spectrum costs stayed demanding.
What The Results Changed For The Vodafone Idea Debate
The clearest fresh fact was the Q1 2027 result. Vodafone Idea reported revenue of ₹116,820m, up from ₹110,080m a year earlier, and the loss narrowed from ₹66,081m to ₹37,540m as net margin improved from a loss of 60.0% to a loss of 32.1%. Profitability remained negative, so the period supported the optimistic story on direction but did not fully settle the cautious concerns.
The key lesson is to pin big narratives about turnarounds to blunt metrics. When you see a bullish profit-margin claim, track whether reported net margin is actually climbing toward that target, not just whether revenue is growing.
What Vodafone Idea's Current Price Already Assumes
Vodafone Idea now trades at ₹12.81. The selected Narrative frames its Fair Value below that level and treats the current quote as already baking in a lot of execution success.
That reading leans on one big tension: a buyer today needs to judge whether rising ARPU and cash EBITDA can consistently outrun churn and heavy spectrum commitments.
"The current numbers on churn, long dated spectrum dues and ambitious cash EBITDA targets imply that the share price already discounts successful execution, leaving limited room for error. Although Vodafone Idea is committing INR 45,000 crores of capex over FY '27 to FY '29 to expand 4G and roll out 5G, base churn of about 4.3% per month that is already significantly higher than others risks persisting if network quality and customer perception do not improve enough."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Beyond Vodafone Idea's 5G Push
Watching Vodafone Idea, you are really watching a bigger question. Where does the demand for faster connections ripple out next?
Mobile users and enterprises do not just want coverage. They also want reliable broadband, secure networks and enough capacity for heavy data workloads.
One large telecom player is leaning into that need. It is wiring up fiber routes, fixed wireless links and connectivity for large computing projects.
The same hunger for speed that shapes Vodafone Idea is shaping this business differently. Your next research step might be one layer away from the tower.
One Narrative has already put a figure on it. → Uncover the company trading 23% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com