


EN
Liberty Energy Stock After A Revenue Gain And Net Loss Has The Bull Case Changed?
- Liberty Energy reported Q3 2026 results with higher revenue but a net loss, raising fresh questions about the economics of its completions and power build out businesses.
- The company’s plan to deploy roughly 3 GW of distributed power for data centers now faces closer scrutiny, as investors weigh capital intensity against near term earnings pressure.
- We will now assess how Liberty Energy’s higher revenue but loss making quarter could reshape the investment narrative around its power expansion.
Scan beyond Liberty Energy and pressure exposed oilfield services by reviewing the hand picked 41 power grid technology and infrastructure stocks that could benefit from the same data center and grid demand story.
Liberty Energy Investment Narrative Recap
To stay in Liberty Energy, you need to believe the completions business can carry the weight of a heavier capex program until the 3 GW power portfolio starts contributing. The recent quarter showed higher revenue but a loss, so the key near term swing factor is whether pricing and utilization in frac hold up well enough to protect cash generation.
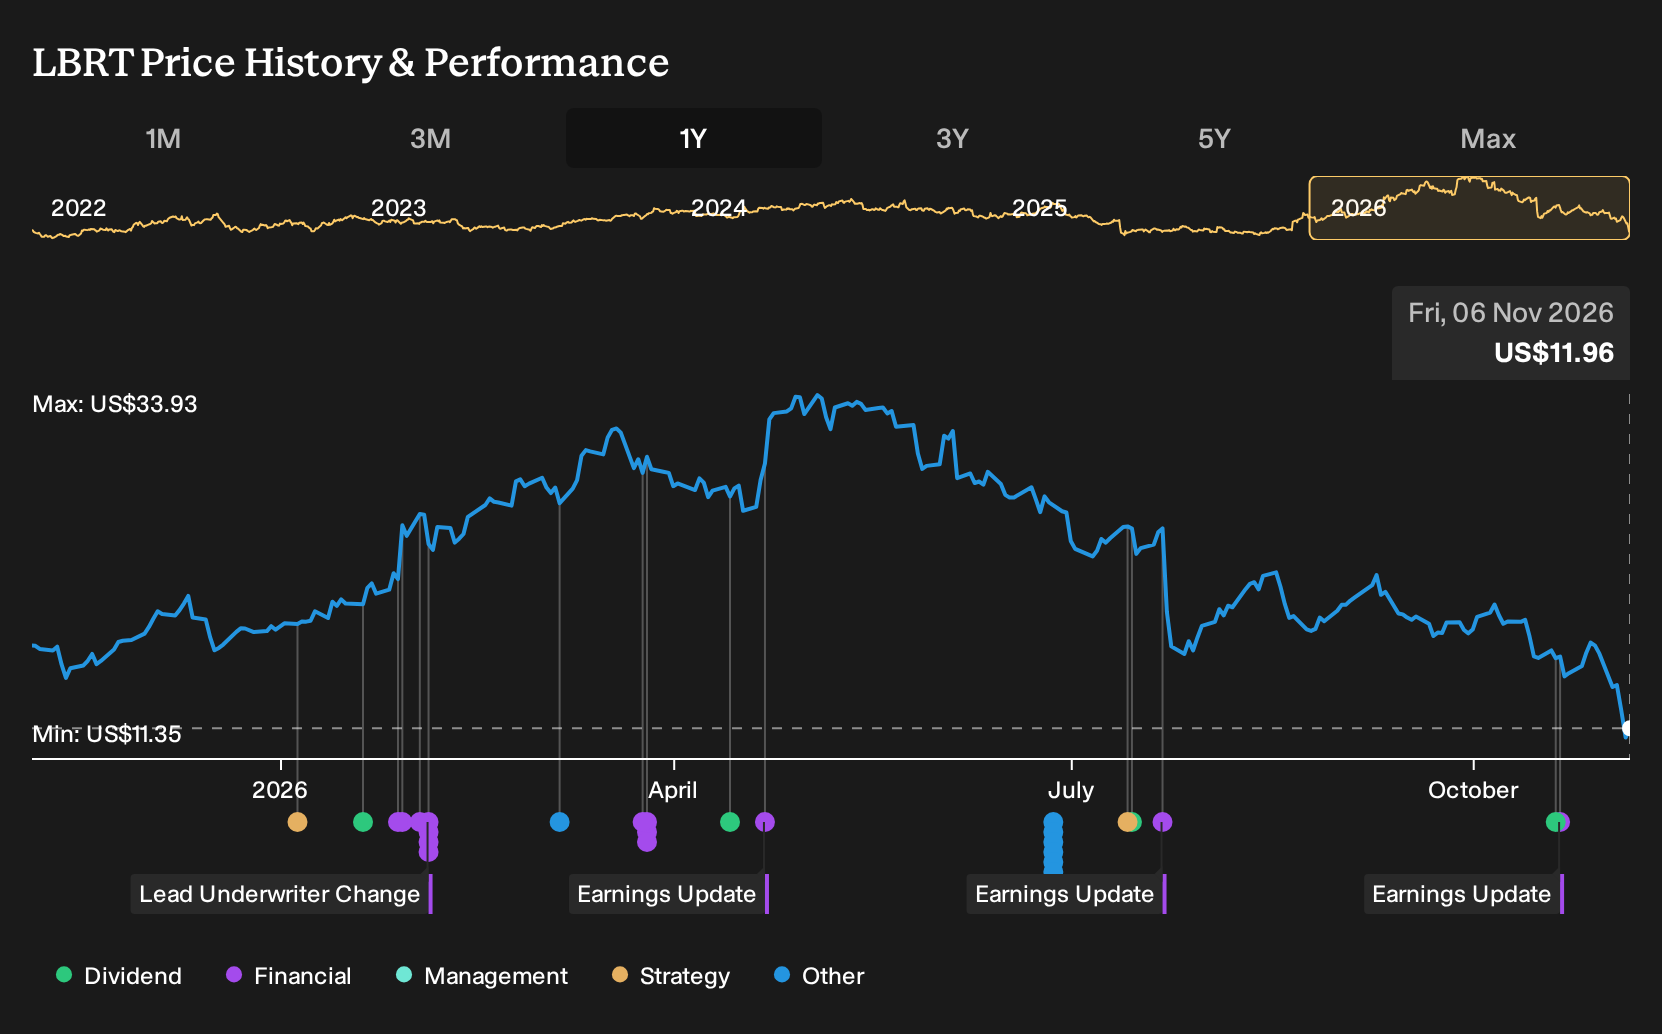
The biggest risk right now sits in the mismatch between US$1.5b of planned 2026 spending and the delayed earnings profile of the power assets. The stock’s 2026 year to date decline and weaker net margin leave less room for execution missteps or prolonged margin pressure in completions.
The appearance at the Denver CIO Executive Leadership Summit underlines how central the data center and IT customer angle has become for Liberty Energy. A VP of IT presenting at a CIO focused event sends a clear message. Power, digital tools and reliability are part of the pitch to prospective counterparties, not just traditional frac customers.
For you as an investor, the relevance is practical. Data centers are a core demand pillar behind the 3 GW distributed power plan. Any indication that Liberty is deepening relationships with CIOs and infrastructure decision makers ties directly back to the main catalyst, securing long term power offtake that can eventually support more stable earnings from the new segment.
Liberty Energy's current revenue trajectory is anchored by analyst assumptions of 12.0% yearly growth, with earnings today at about US$40.3 million and consensus expectations reaching US$575.2 million by 2029. This implies an increase of roughly US$535 million in profit, while the wider narrative points to forecast revenues of US$6.2 billion and earnings of US$575.2 million in 2029 as the key test for whether the investment case holds up.
Uncover how Liberty Energy's fair value indicates a 126% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate story around Liberty Energy focuses less on data center upside and more on the risk that its 3 GW power build ties up cash for years. The most cautious analysts were working off slower 7.7% annual revenue assumptions and about US$5.5b in 2029 sales, which frames a much more muted outlook. Those estimates were set before the Denver CIO summit and Q3 loss. You should expect opinions to move as new information lands and compare several viewpoints before deciding how this fits your portfolio.
Explore 4 other Liberty Energy fair value estimates, including one that suggests as much as 25% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Liberty Energy research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Liberty Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liberty Energy's overall financial health at a glance.
Looking for more investment ideas beyond Liberty Energy?
Once you have a view on Liberty Energy, it can help to zoom out and compare it with other opportunities that fit different objectives, whether you care most about value, resilience, or balance sheet strength.
- If you want potential value combined with quality fundamentals, use the 38 high quality undervalued stocks to see companies that analysts have filtered for both financial strength and pricing support.
- For readers who care most about capital preservation and steadier profiles, the 31 resilient stocks with low risk scores can help you focus on businesses with lower overall risk scores.
- When balance sheet strength matters more than anything else, start with the list of solid balance sheet and fundamentals (25 results) and filter for companies where debt, liquidity, and core fundamentals are front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com