


EN
MakeMyTrip (MMYT) Earnings Leave Valuation Debate Wide Open
MakeMyTrip (MMYT) has drawn fresh attention after releasing earnings for the second quarter and six months to September 30, 2026, with revenue higher year over year but six month net income lower than the prior period.
At a share price of $51.1, MakeMyTrip has seen a sharp 7 day share price return of 19.73% and a 30 day gain of 14.24%. However, the 90 day share price return is down 16.11% and the year to date move is lower by 37.60%, while the 1 year total shareholder return is down 34.52% against a still positive 3 year total return of 22.90% and 5 year total return of 52.17%. This suggests that recent momentum has picked up after a weaker stretch, but the longer record remains mixed.
Scan how MakeMyTrip’s latest swing compares with other travel and consumer services stocks by checking out the hand picked 19 high quality undiscovered gems in this space.
MakeMyTrip now trades well below the average analyst target even after this rebound, while its own value score looks harsh. Is the market rightly cautious, or has sentiment swung too far given the recent earnings mix?
Most Popular Narrative: 24.5% Undervalued
Against the latest close at $51.1, the most followed narrative pegs MakeMyTrip’s fair value at $67.7. This frames analyst enthusiasm around travel demand, AI spending and the planned India listing in a single valuation anchor.
The current valuation implies the market is pricing MakeMyTrip below what a bullish narrative would view as the full value of its market position, AI investments and planned India listing.
The confidential filing for an initial public offering and listing of MakeMyTrip India, along with the stated plan to use net proceeds for long term growth, inorganic opportunities and repurchases of various securities, can increase financial flexibility and, if executed as described, support future revenue growth and earnings per share.
See why 10 investors see MakeMyTrip as 25% undervalued.
Result: Fair Value of $67.7 (UNDERVALUED)
Still, pressure on air travel and the sizeable US$1.6b zero coupon convertible bond stack could challenge the bullish MakeMyTrip narrative if conditions stay tough.
Find out about the key risks to this MakeMyTrip narrative.
Another View: What Multiples Say About MakeMyTrip
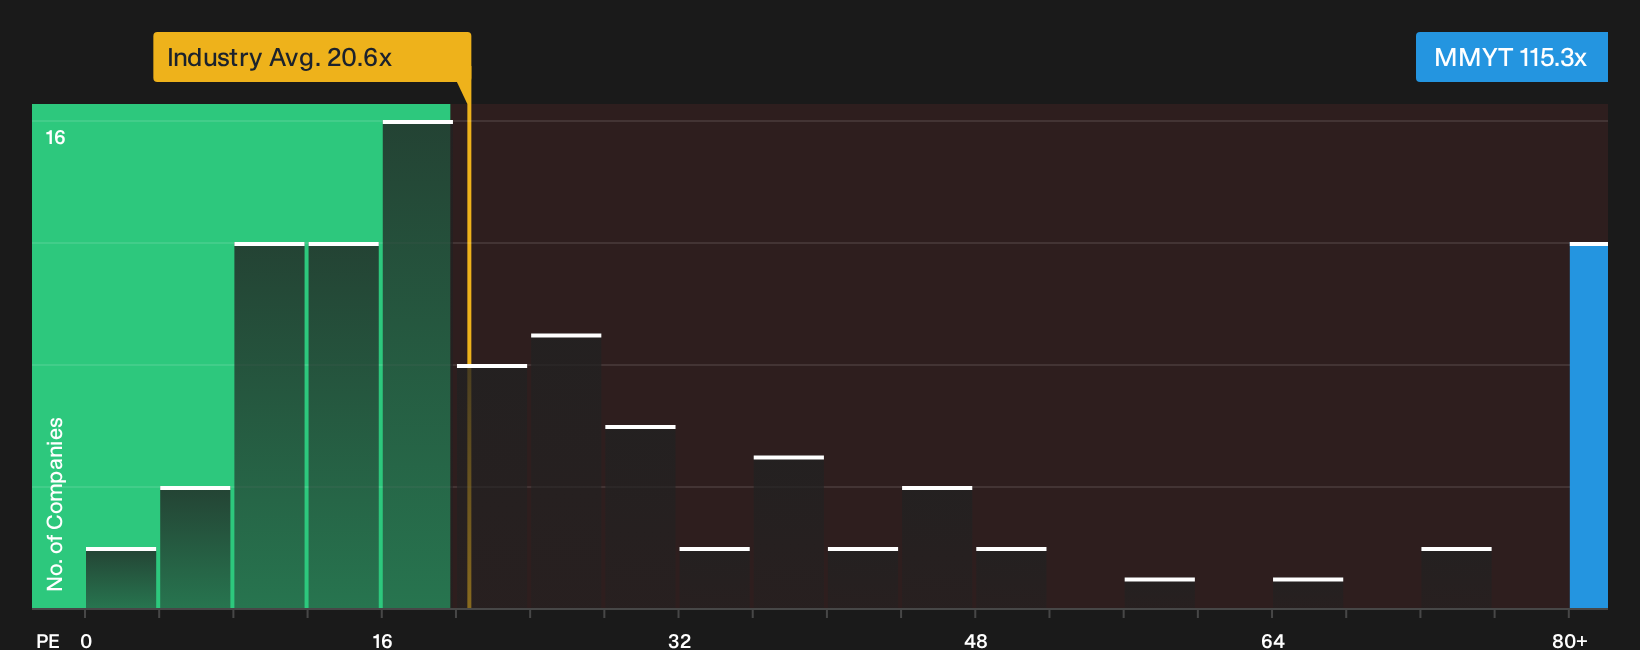
The story changes once you step away from fair value narratives and look at plain P/E math for MakeMyTrip. The stock trades on roughly 115x earnings, while the fair ratio is 61x and the US Hospitality group averages about 21x. That is a wide gap, and it leans toward valuation risk rather than obvious upside. So which signal do you trust more: the narrative discount or the rich earnings multiple?
To see how this earnings multiple picture fits into the wider valuation workup, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sitting between a cautious multiple and a bullish fair value story, MakeMyTrip gives you plenty of conflicting signals to weigh. If you want the full context before deciding how you feel about the stock, it helps to see both sides of the argument through the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MakeMyTrip?
If you stop at MakeMyTrip, you only see part of the opportunity set. Let the data surface ideas you might never spot on your own.
- Target potential upside in overlooked corners of the market by scanning the 19 high quality undiscovered gems that quietly pair strong fundamentals with less attention.
- Prioritise resilience over drama by reviewing the 31 resilient stocks with low risk scores that score well on financial strength and lower risk profiles.
- Anchor your watchlist in quality by using the list of solid balance sheet and fundamentals (25 results) to focus on businesses with sturdier finances and cleaner balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com