


EN
Tennant (TNC) Could Be 19% Undervalued On Q3 Results And Higher Dividend
Tennant (TNC) is back in focus after third quarter 2026 results, with higher sales, improved quarterly net income, reaffirmed full year guidance and a raised cash dividend drawing fresh investor attention.
Those quarterly headlines arrived after a choppy period for Tennant’s investors, with the 1-month share price return of 8.45% and 7-day gain of 7.62% helping to offset a year-to-date share price decline of 3.33% and a 1-year total shareholder return that is down 2.47%.
Scan Tennant’s latest move against a curated group of industrial peers by reviewing list of solid balance sheet and fundamentals (25 results), which have also kept investing while returning cash to shareholders.
Tennant now trades at a double discount, both to analyst targets and to one estimate of fair value, even after the post earnings bounce. Is that caution earned, or has the market moved too slowly?
Most Popular Narrative: 19% Undervalued
Tennant’s most followed narrative pegs fair value at $87.75 for a stock that last closed at $71.50. The gap to that anchor remains clear even after the recent rebound.
Accelerated adoption of autonomous mobile robots and equipment-as-a-service programs is still expanding Tennant's potential recurring revenue base. The company now targets robotics revenue of about US$250 million in 2028, supported by 10 planned product launches and recent 56% year-over-year growth in first half 2026 robotics sales, which is likely to matter most for long-term revenue and earnings quality.
See why 12 investors see Tennant as 19% undervalued.
Result: Fair Value of $87.75 (UNDERVALUED)
Still, Tennant’s North American ERP rollout issues and competitive pricing pressure in regions like EMEA could both weaken margins and challenge this undervaluation narrative.
Find out about the key risks to this Tennant narrative.
Another View: Tennant’s Rich Earnings Multiple
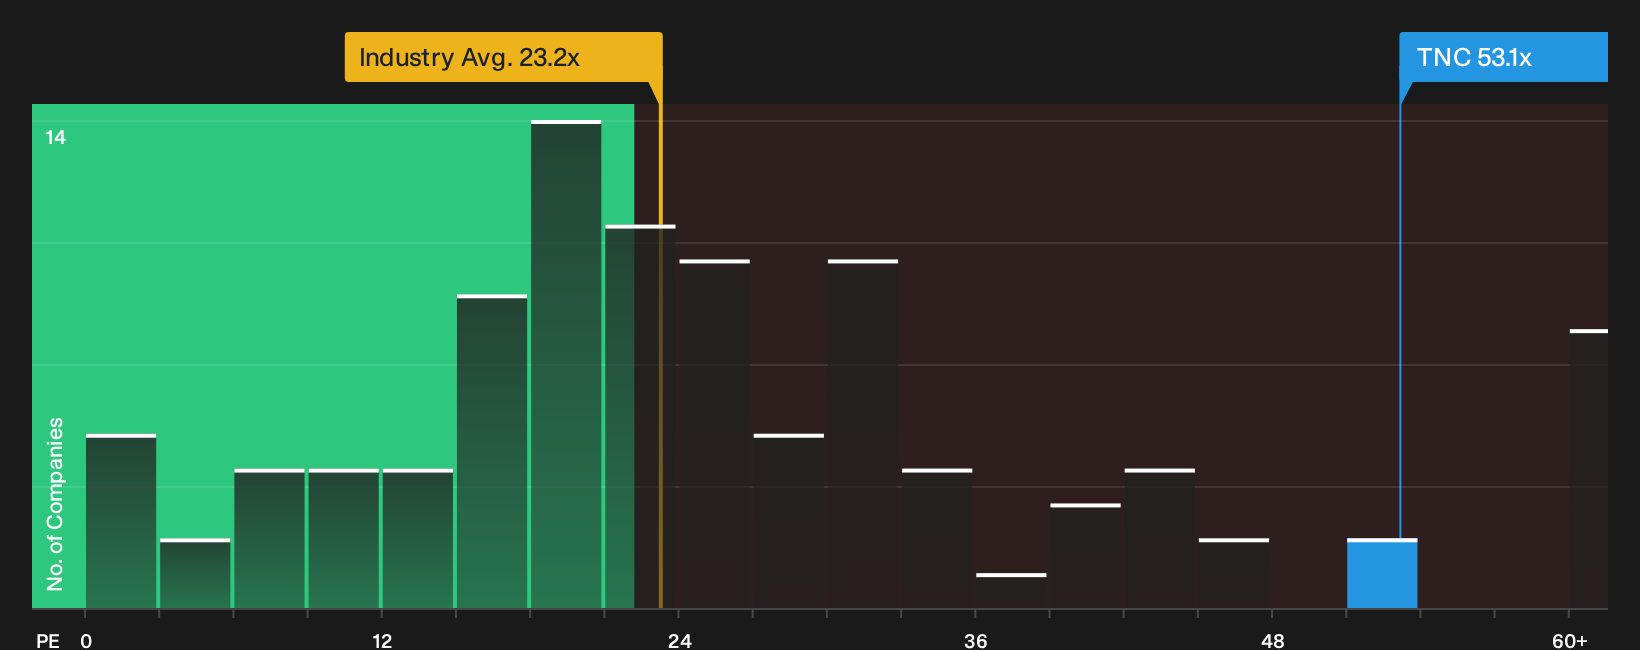
The DCF work points to Tennant as undervalued, yet the P/E picture tells a very different story. The stock trades on 53.1x earnings, above the US Machinery industry at 23.2x and ahead of peer averages at 39.3x, while the fair ratio sits lower at 46.7x. That premium raises a simple question for investors: Is the robotics story strong enough to justify paying up on earnings today?
To see how this earnings multiple risk fits into the broader valuation picture, including how price could shift if the P/E drifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Tennant is clearly mixed, with both risks and rewards on the table. Act while the data is fresh and pressure test the thesis for yourself with 3 key rewards and 3 important warning signs
Looking for more Tennant investment ideas?
Before moving on from Tennant, use this moment of fresh insight to widen your watchlist with a few focused idea lists built from the same data engine.
Spot potential mispricings by scanning a curated set of 38 high quality undervalued stocks that combine quality fundamentals with what could be appealing entry prices.
Strengthen your income stream by reviewing a hand picked pool of 7 dividend fortresses that aim to balance payout size with business resilience.
Dial down portfolio stress by filtering for 31 resilient stocks with low risk scores that may offer more defensive profiles when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com