


EN
What Agilysys (AGYS)'s Raised Guidance Means For Shareholders
- Agilysys reported second quarter fiscal 2027 results with revenue of US$93.36 million and net income of US$13.18 million, alongside higher earnings per share than the prior year period.
- Management also raised full year 2027 revenue guidance to a range of US$374 million to US$378 million, pointing to at least 34% subscription revenue growth year over year as a key driver.
- The focus now turns to how Agilysys' investment narrative evolves as higher full year revenue guidance interacts with its subscription-heavy hospitality platform.
Scan how Agilysys' raised guidance fits into the wider software opportunity by reviewing hand-picked enterprise and tech platforms on the 19 high quality undiscovered gems.
Agilysys Investment Narrative Recap
To own Agilysys, you need to be comfortable with a hospitality focused software platform that leans heavily on recurring subscription contracts. The raised full year 2027 revenue outlook and at least 34% expected subscription growth point to that model becoming more central. The near term swing factor remains execution on large rollouts while keeping implementation and service quality tight.
The biggest current risk is still end market exposure. A slowdown in travel or a softer casino and gaming cycle could make bookings choppy, especially in international markets that have already seen uneven demand. The latest earnings and guidance update do not remove that cyclicality, but they do suggest the operating playbook is holding together for now.
The most relevant recent announcement for this story is Agilysys lifting fiscal 2027 revenue guidance to US$374 million to US$378 million and raising its subscription growth expectation to at least 34%. That update anchors the key near term catalyst, which is whether the hospitality experience cloud and PMS centric stack keep pulling more properties and modules per customer.
Higher guidance also sharpens the execution bar. To live up to those targets, the business needs consistent order patterns in international and gaming verticals and enough pricing power to offset competitive pressure on gross margins. For you as an investor, the focus is on whether that subscription mix and implementation efficiency translate into steadier earnings without masking rising operational risk.
Agilysys' current analyst narrative points to forecast revenue of US$557.0 million and earnings of US$104.5 million by 2029, built on assumed yearly top line growth of 17.4% and an earnings increase of about US$60.1 million from US$44.4 million today.
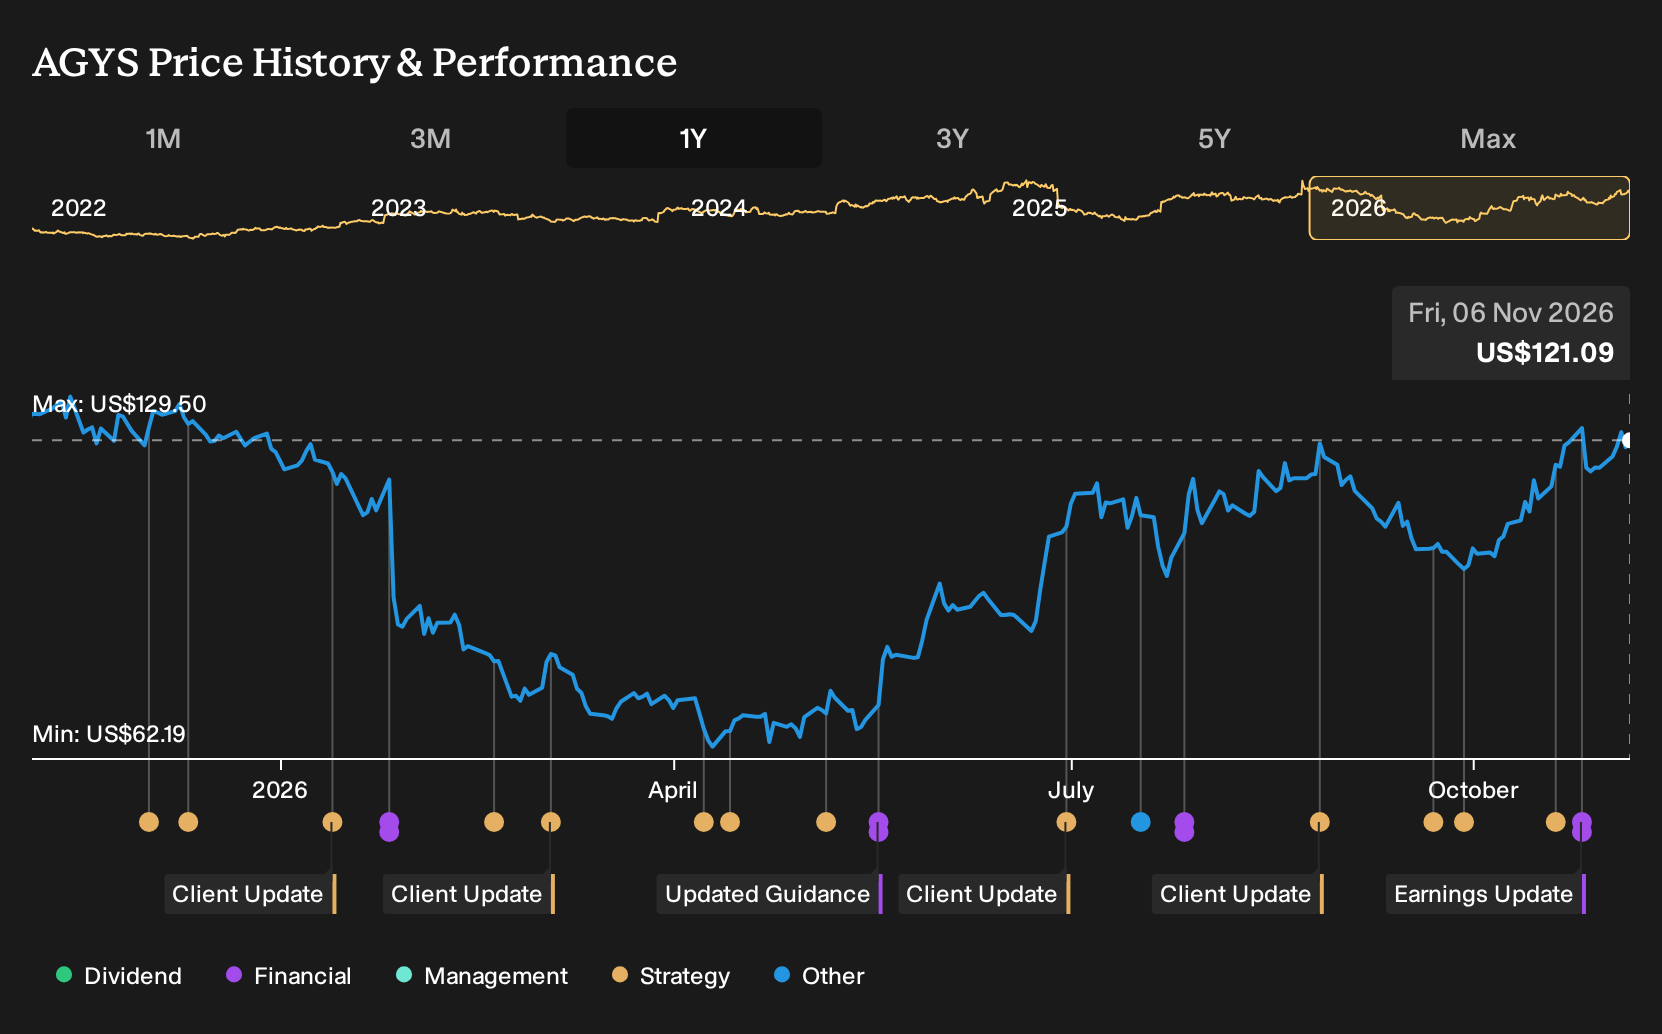
Uncover why Agilysys' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Agilysys leans heavily on margin risk. The most cautious analysts worry that cybersecurity, compliance and infrastructure costs could keep profitability tight, even with raised revenue guidance. Before this earnings release, they were pencilling in about US$532.5 million of revenue and US$106.3 million of earnings for 2029, so their story may shift meaningfully from here.
Explore 4 other Agilysys fair value estimates, including one that suggests as much as 84% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Agilysys research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agilysys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agilysys' overall financial health at a glance.
Looking For More Ideas Beyond Agilysys?
If the Agilysys story has sharpened how you think about recurring revenue and execution risk, you can use that same lens to look across a broader watchlist. Filtering the wider market with focused screeners can help you quickly spot other businesses that fit your preferred mix of quality, balance sheet strength and return potential.
- For investors who want a margin of safety and solid fundamentals, start with a curated set of financially robust opportunities through the 38 high quality undervalued stocks.
- If balance sheet resilience matters most to you, narrow your search to companies with low leverage and strong financial foundations by using the list of solid balance sheet and fundamentals (25 results).
- For readers who prefer income on top of potential price gains, focus on cash generating businesses paying higher yields via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com