


EN
How Investors Are Reacting To Leidos Stock AI Product Launch
- Leidos Holdings reported third quarter 2026 sales of US$4,630 million and net income of US$410 million, completed a US$504 million share repurchase program, raised its quarterly dividend to US$0.45 per share, and introduced HeadWay Dispatch to govern AI agents across vendors.
- Alongside earnings and capital returns, Leidos Holdings is deepening work on long range cruise missiles and cyber mission platforms for U.S. defense customers, which ties AI governance, munitions production and cyber operations into a broader push toward higher value federal programs.
- We will look at how Leidos Holdings' investment narrative is affected by the HeadWay Dispatch AI governance launch and related defense wins.
Compare Leidos Holdings' AI governance and defense focus with hand picked peers by scanning 40 profitable AI stocks that aren't just burning cash that are moving on real contracts and tangible earnings, not just headlines.
Leidos Holdings Investment Narrative Recap
To own Leidos Holdings, you need to believe the mix of higher value defense tech, AI platforms and energy work can stay front and center while health margins and federal budgets remain manageable risks. The latest quarter showed higher sales and earnings, but management trimmed 2026 revenue guidance, which keeps contract timing and funding a live question.
Right now the key near term swing factor is execution on large federal programs, particularly in defense and digital modernization, given earnings forecasts already look cautious. The biggest risk remains concentration in U.S. government spending. The recent results and guidance tweak do not radically change that equation, but they do keep attention on award flow and backlog quality.
Among the recent news, HeadWay Dispatch matters most for this AI governance story. The platform gives customers visibility into which agents are running, what they can access and where human approval is required. That directly links Leidos Holdings’ software presence to real policy needs in defense, intelligence and civil agencies that are under pressure to govern AI use.
HeadWay Dispatch also connects back to catalysts in cyber operations and federal AI spending. The product is designed to work across multiple vendors, create tamper evident records and keep credentials out of agents, which speaks to operational risk management rather than hype. If agencies lean on it to meet OMB AI governance and portability requirements, that could reinforce Leidos’ position in higher value contracts around cyber and mission software.
Leidos Holdings Consensus Setup Through 2029
Analysts are effectively tying the Leidos Holdings AI governance story and defense exposure to a long glide path that runs out to 2029. The working assumption is that revenue grows by 4.4% a year for the next few years, while profit margins edge slightly lower from 7.8% today to 7.7% in 3 years. That creates a picture where the business is larger and still profitable, but not dramatically more profitable on each incremental dollar of sales.
On the earnings side, the consensus view is for net income to move from US$1.4b today to US$1.5b by around 2029, with analysts split between roughly US$1.3b at the low end and US$1.9b at the high end. That is an increase of about US$100m from current earnings, which is a modest step up for a company already generating over US$1b of profit. The forecast also bakes in a gradual reduction in share count of 1.85% per year over the next 3 years, which would mechanically lift earnings per share if profit holds anywhere near the consensus level.
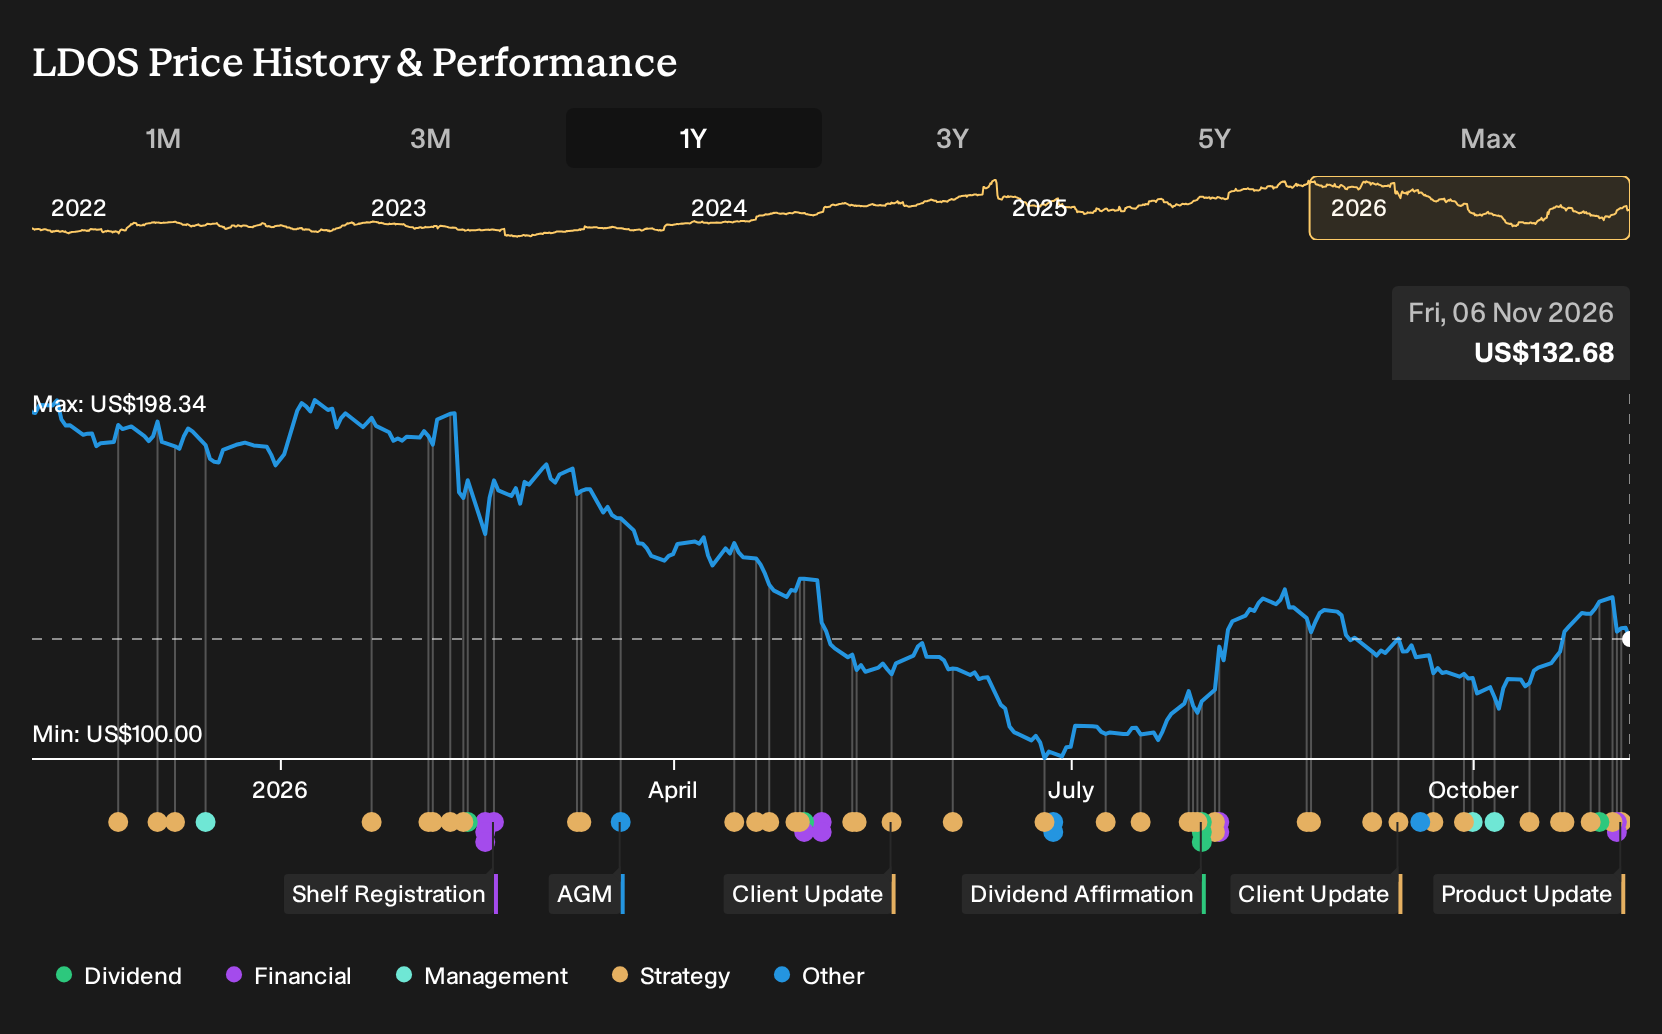
Valuation work in these reports connects that earnings path to a P/E of 14.9x on the projected 2029 profit, compared with about 11.0x today. Analysts are also using an implied 2029 revenue figure of US$20.0b and earnings of US$1.5b to support a consensus price target of US$151.73, using a discount rate a bit above 8%. Those inputs sit against a current share price of US$120.59. The gap between today’s quote and the analyst target is material, even if the range of individual price targets from US$127 to US$225 shows that there is real disagreement on how the AI and defense mix ultimately plays out.
Leidos Holdings is therefore framed as a company where modest revenue growth, relatively stable but slightly lower margins, and incremental buybacks need to work together. The long term narrative assumes federal customers continue to award contracts in areas like AI governance, cyber mission platforms and munitions, while the business converts those awards into earnings that roughly match the US$1.5b consensus. Any change in contract timing, budget decisions or program execution could move those numbers, but the key moving pieces are already visible in the current order book and the AI governance push around HeadWay Dispatch.
Leidos Holdings' narrative projects US$20.0b revenue and US$1.5b earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about US$100m from US$1.4b today.
Uncover why Leidos Holdings' fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster around US$151.73 at the low end and stretch to US$267.96 at the top, so opinion on Leidos Holdings is already wide even before factoring in HeadWay Dispatch, missile programs, buybacks and dividend moves. Use that spread as a prompt to explore several contrasting Community viewpoints.
Explore 2 other Leidos Holdings fair value estimates, including one that suggests it could be worth just $151.73.
Reach Your Own Conclusion
Disagree with existing narratives? Some investors believe that extraordinary investment returns rarely come from following the herd, so you may choose to go with your own instincts.
- A great starting point for your Leidos Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Leidos Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leidos Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Leidos Holdings?
If you want to balance your view on Leidos Holdings with fresh opportunities, it helps to scan for companies that match the kind of traits you care about most, whether that is value, resilience or future potential.
- For investors who focus on resilient balance sheets and fundamentals, start by reviewing our list of solid balance sheet and fundamentals (25 results) to see which businesses currently screen strongest on financial strength.
- If your priority is potential value, compare Leidos Holdings with companies that look attractively priced on quality and cash flow using the 38 high quality undervalued stocks and build a watchlist from there.
- For those searching for less crowded ideas, scan the 19 high quality undiscovered gems and see which under followed stocks still show solid fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com