


EN
EDP (ENXTLS:EDP) Lifts 2026 Outlook Again, Is The Upside Already Priced In?
EDP (ENXTLS:EDP) just raised its 2026 guidance for the third time, alongside publishing third quarter and nine month results that showed higher sales and net income and underlined liquidity coverage through 2029.
Those stronger earnings and the upgraded 2026 outlook are landing at a time when EDP’s share price has quietly been grinding higher. A 30 day share price return of 4.19% and an 11.96% gain over 90 days feed into a 24.88% year to date move and a 34.44% 1 year total shareholder return.
Scan other utilities that may be showing similar guidance upgrades and earnings momentum with our curated 41 power grid technology and infrastructure stocks
EDP now has upgraded guidance, higher recent earnings and a share price that is already up strongly over the past year. Does the current valuation still leave enough upside to justify fresh risk?
Most Popular Narrative: 4% Undervalued
Against a last close of €5.00, the most followed narrative for EDP pegs fair value at about €5.21, which implies only a small gap between price and modelled worth and puts the focus firmly on whether the medium term plan is executed cleanly.
The main thing that has to go right is that EDP continues to execute its large grid and renewables capex and asset rotation plan while holding OpEx discipline so that targeted EBITDA, net profit and net debt outcomes for 2026 to 2028 remain within guided ranges.
The current valuation implies EDP is fairly valued on the basis that the market already prices in the planned €12b of 2026 to 2028 investments, the expected €1b net debt reduction and the reduced earnings sensitivity to power prices.
See why 49 investors see EDP as 4% undervalued.
Result: Fair Value of €5.21 (UNDERVALUED)
Still, the EDP story can crack if asset rotation gains soften, or if Brazilian FX and severe weather events hit reported earnings harder than analysts currently model.
Find out about the key risks to this EDP narrative.
Another View On EDP: P/E Ratio Sends A Different Signal
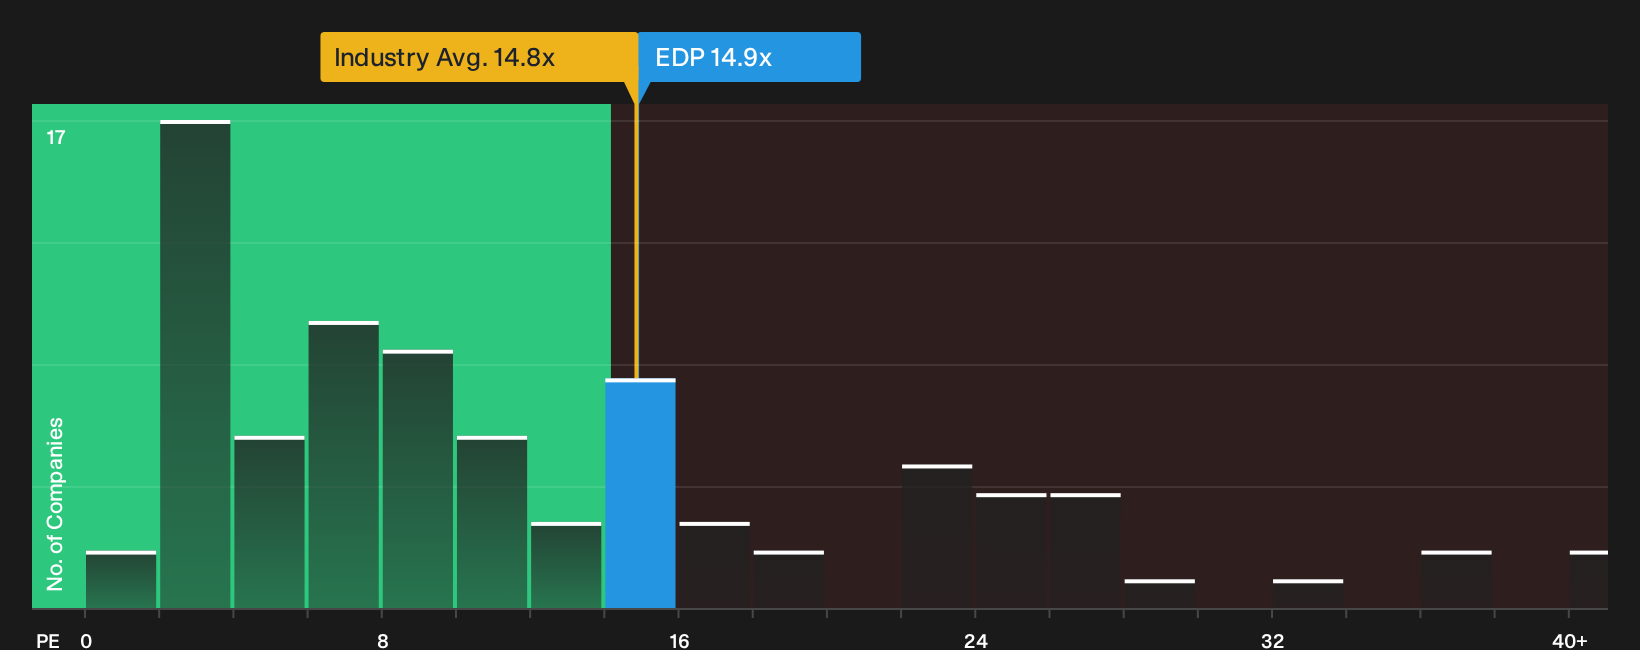
That narrative driven fair value of €5.21 suggests EDP is only modestly undervalued. The simple P/E math tells a tougher story. At 14.9x earnings, the stock trades slightly above the European electric utilities average of 14.8x and well below its own fair ratio of 20.6x.
This mix of being a touch expensive versus the wider industry but much cheaper than its fair ratio points to a trade off. Investors are paying a small premium for EDP relative to peers, while leaving a sizeable gap to what the market could move towards if those earnings assumptions hold. Is that gap a safety margin or a signal that expectations are already full?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on EDP so far. If you want a clearer view before sentiment shifts again, consider both sides of the story in the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond EDP?
If EDP has your attention but you also want fresh opportunities, use targeted screeners to quickly surface stocks that match the risk and return profile you prefer.
- Target underpriced quality by scanning companies that combine strong fundamentals with room for a rerating using the 225 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with sturdy finances through the list of solid balance sheet and fundamentals (192 results).
- Spot early opportunities by tracking lesser known stocks with robust metrics via the 578 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com