


EN
Will Earnings And Buyback Change Align Technology Stock Narrative
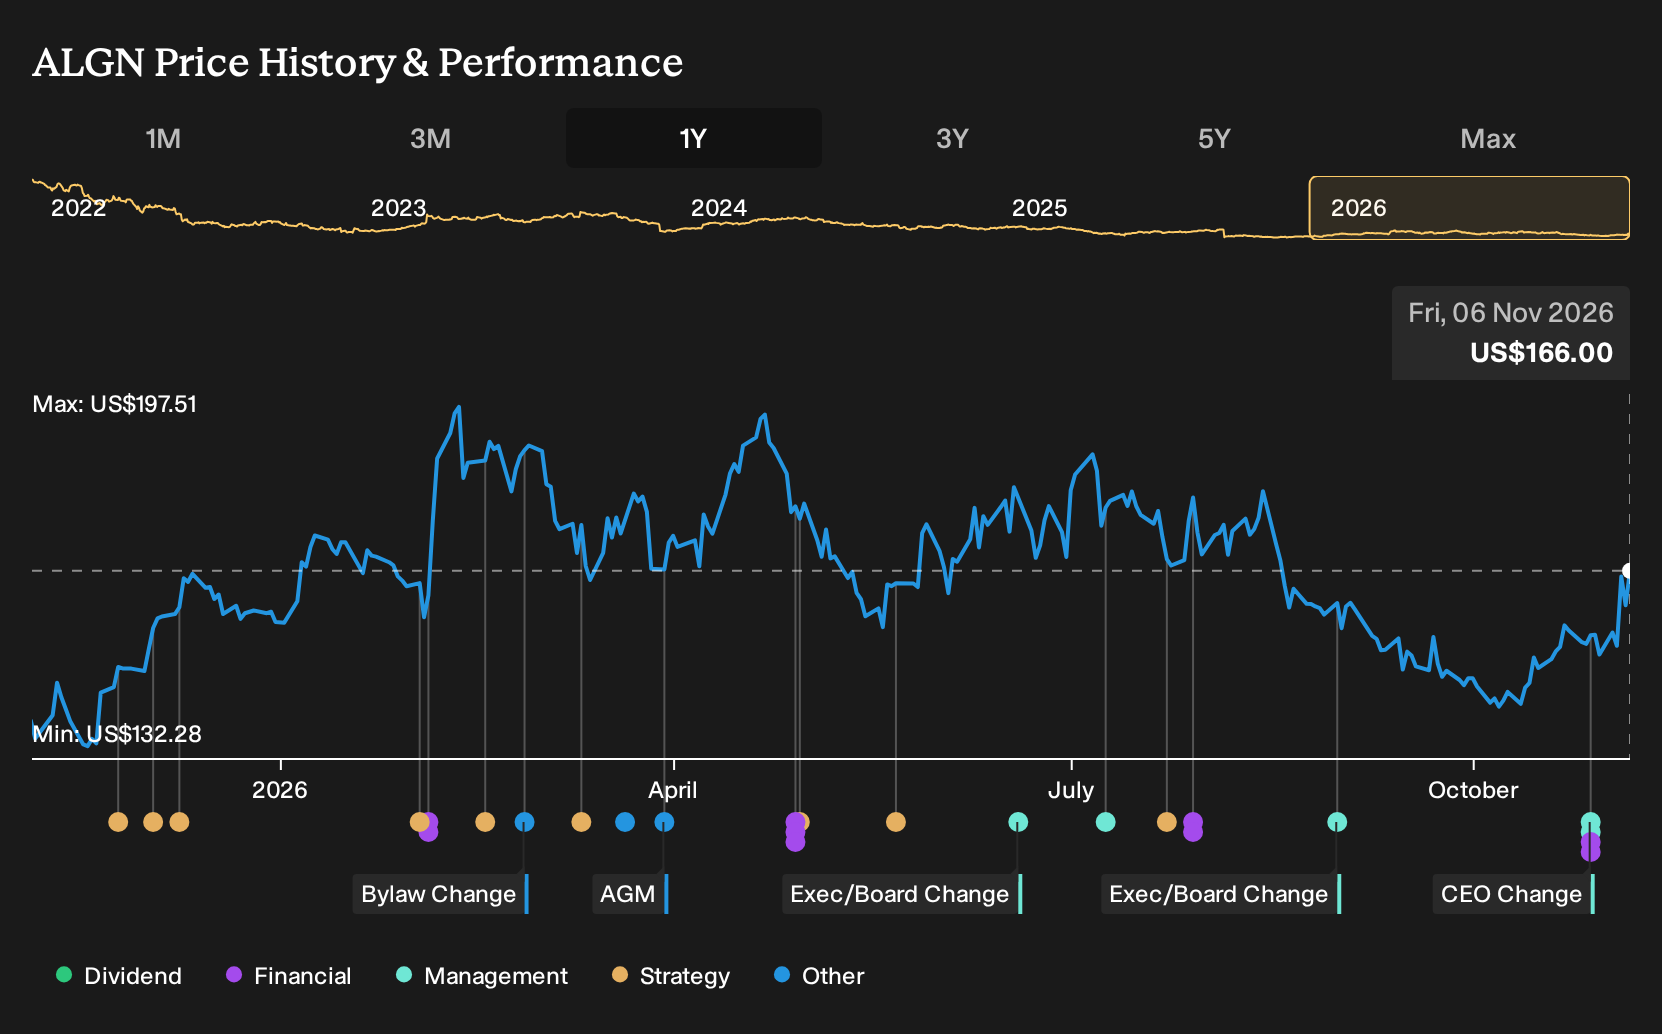
- Align Technology reported third quarter 2026 sales of US$1,014.76 million and net income of US$135.04 million, reaffirmed fourth quarter and full year 2026 guidance, and announced a US$270 million accelerated share repurchase funded with cash on hand.
- The combination of confirmed revenue and margin guidance with a sizeable buyback indicates that Align Technology is prioritizing operating consistency and disciplined capital return while managing a planned CEO transition to healthcare veteran Jennifer L. Davis.
- Next, the focus shifts to how Align Technology's confirmed 2026 guidance and accelerated share repurchase could reshape the existing investment narrative.
Align Technology Investment Narrative Recap
To own Align Technology, you need to be comfortable with a clear aligner and scanner business that leans heavily on international adoption, DSO partners and consistent execution on digital workflows. The confirmed 2026 revenue and margin guidance keeps that thesis intact in the near term. The key short term swing factor still looks like clear aligner case volumes, especially where North America retail demand has been softer.
The biggest operational risk remains mix and pricing pressure in Systems and Services, where lower up front scanner models can weigh on reported revenue even if placements grow. Recent results and guidance do not fundamentally change that risk. They simply show management is running against it with a tight focus on margins and cost discipline.
The most relevant announcement for this setup is the appointment of Jennifer L. Davis as CEO and President, effective December 31, 2026, with a defined handover period from Joseph Hogan. For you as a shareholder, that decision matters because Align Technology is trying to push international Invisalign adoption, expand DSO relationships and execute on scanner subscription models while also targeting higher operating margins.
A planned transition, with Davis joining as CEO elect and director on November 2, 2026 and Hogan staying as advisor into mid 2027, gives the incoming leader time to absorb the existing playbook. That continuity could help maintain focus on current catalysts such as APAC and EMEA volume growth, China opportunities and the margin expansion plan, while still leaving room to refine how the firm handles regulatory and legal headwinds over time.
Align Technology's current analyst setup points to revenues of US$4.7b and earnings of US$750.6 million by 2029, based on assumed 4.5% yearly revenue growth and an earnings increase of about US$337 million from US$413.6 million today.
Uncover why Align Technology's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a very different take, focus on the bullish catalyst around Align Technology’s digital platform. The most optimistic analysts, before this CEO news and updated guidance, were already modeling 4.8% annual revenue growth and earnings of about US$817.8 million by 2029. You can see how opinions diverge sharply and decide which assumptions feel more realistic to you.
Explore 5 other Align Technology fair value estimates, including one that suggests potential upside of up to 200% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Align Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Align Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Align Technology's overall financial health at a glance.
Looking for more investment ideas beyond Align Technology?
If the Align Technology story has sharpened your thinking and you want to broaden your watchlist, the Simply Wall St Screener can help you quickly surface other opportunities that fit very different risk and return profiles.
- Target dependable cash generators and focus on resilience under pressure with a 31 resilient stocks with low risk scores that may suit a more cautious approach.
- Hunt for quality businesses trading on what could be appealing valuations by scanning a 38 high quality undervalued stocks that filters for both fundamentals and pricing.
- Aim to balance income needs with balance sheet strength by reviewing a 7 dividend fortresses that focuses on higher yielding companies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com